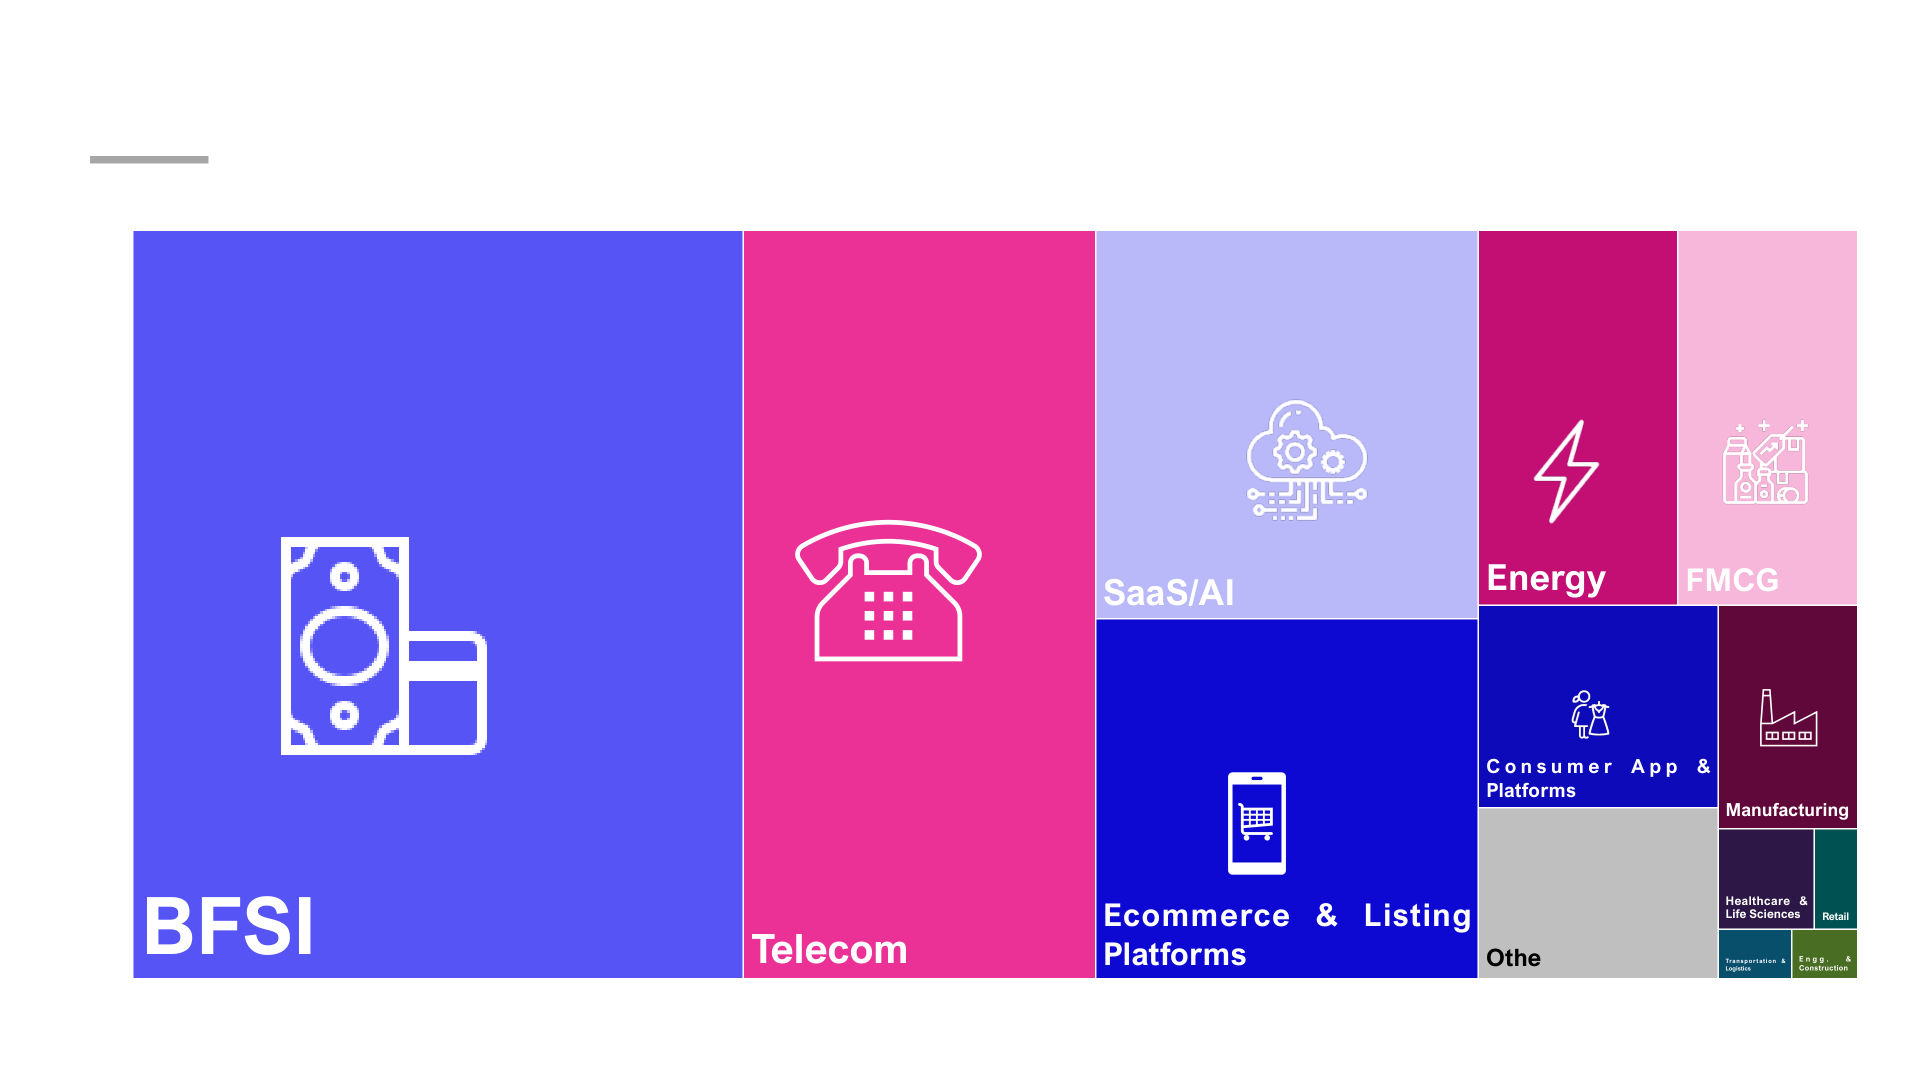
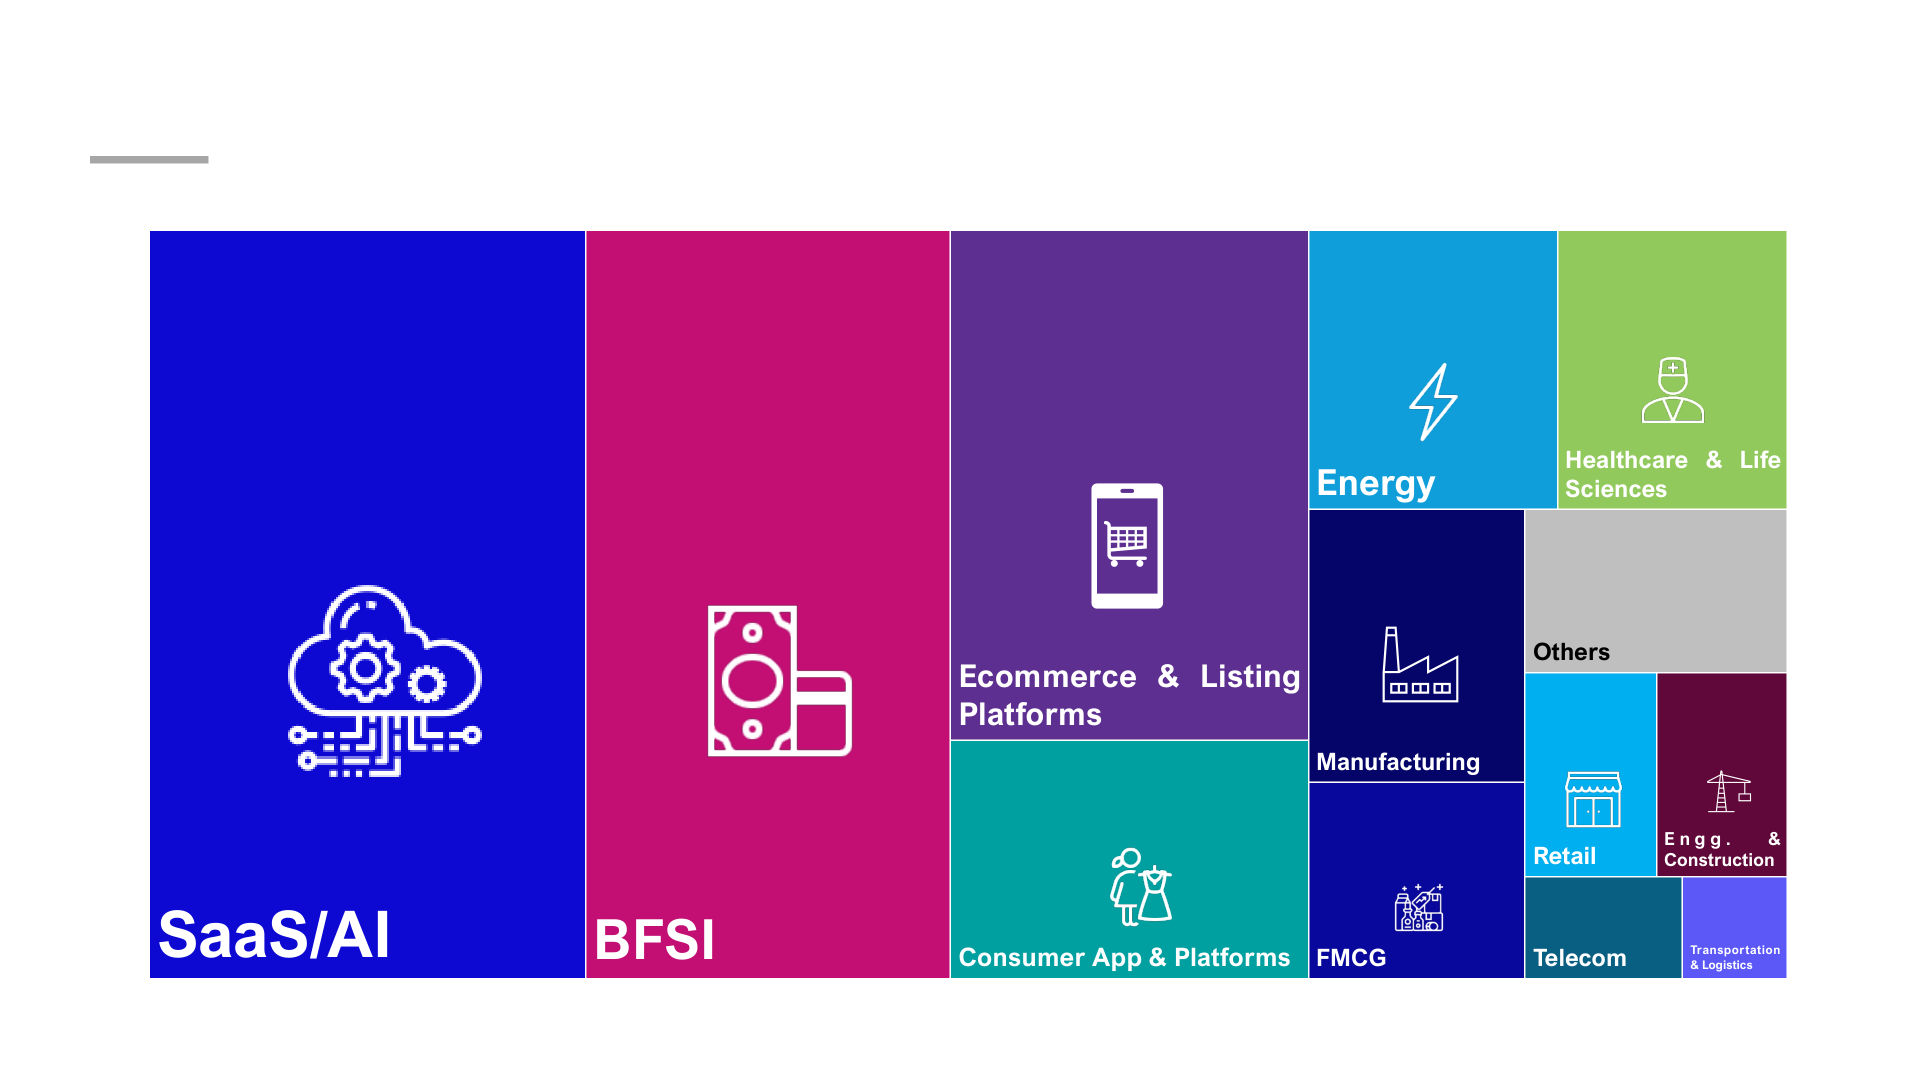
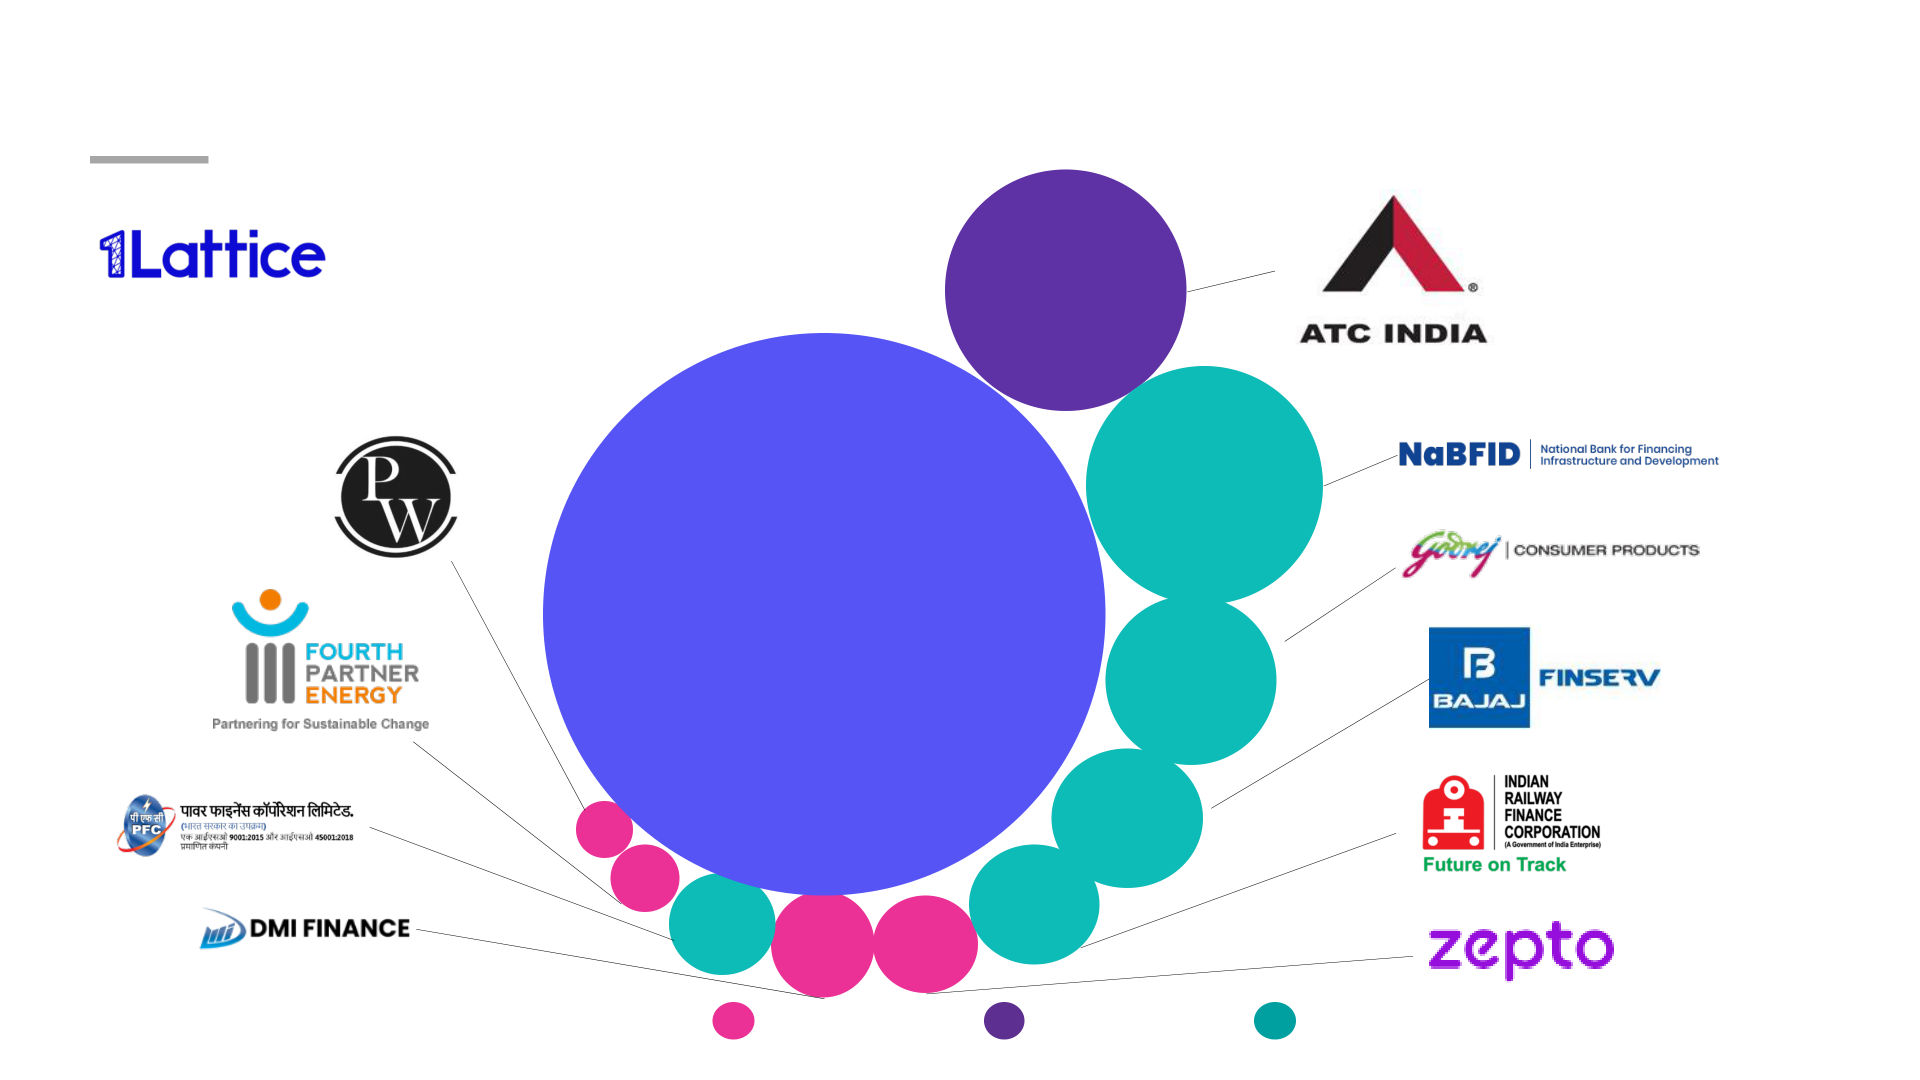
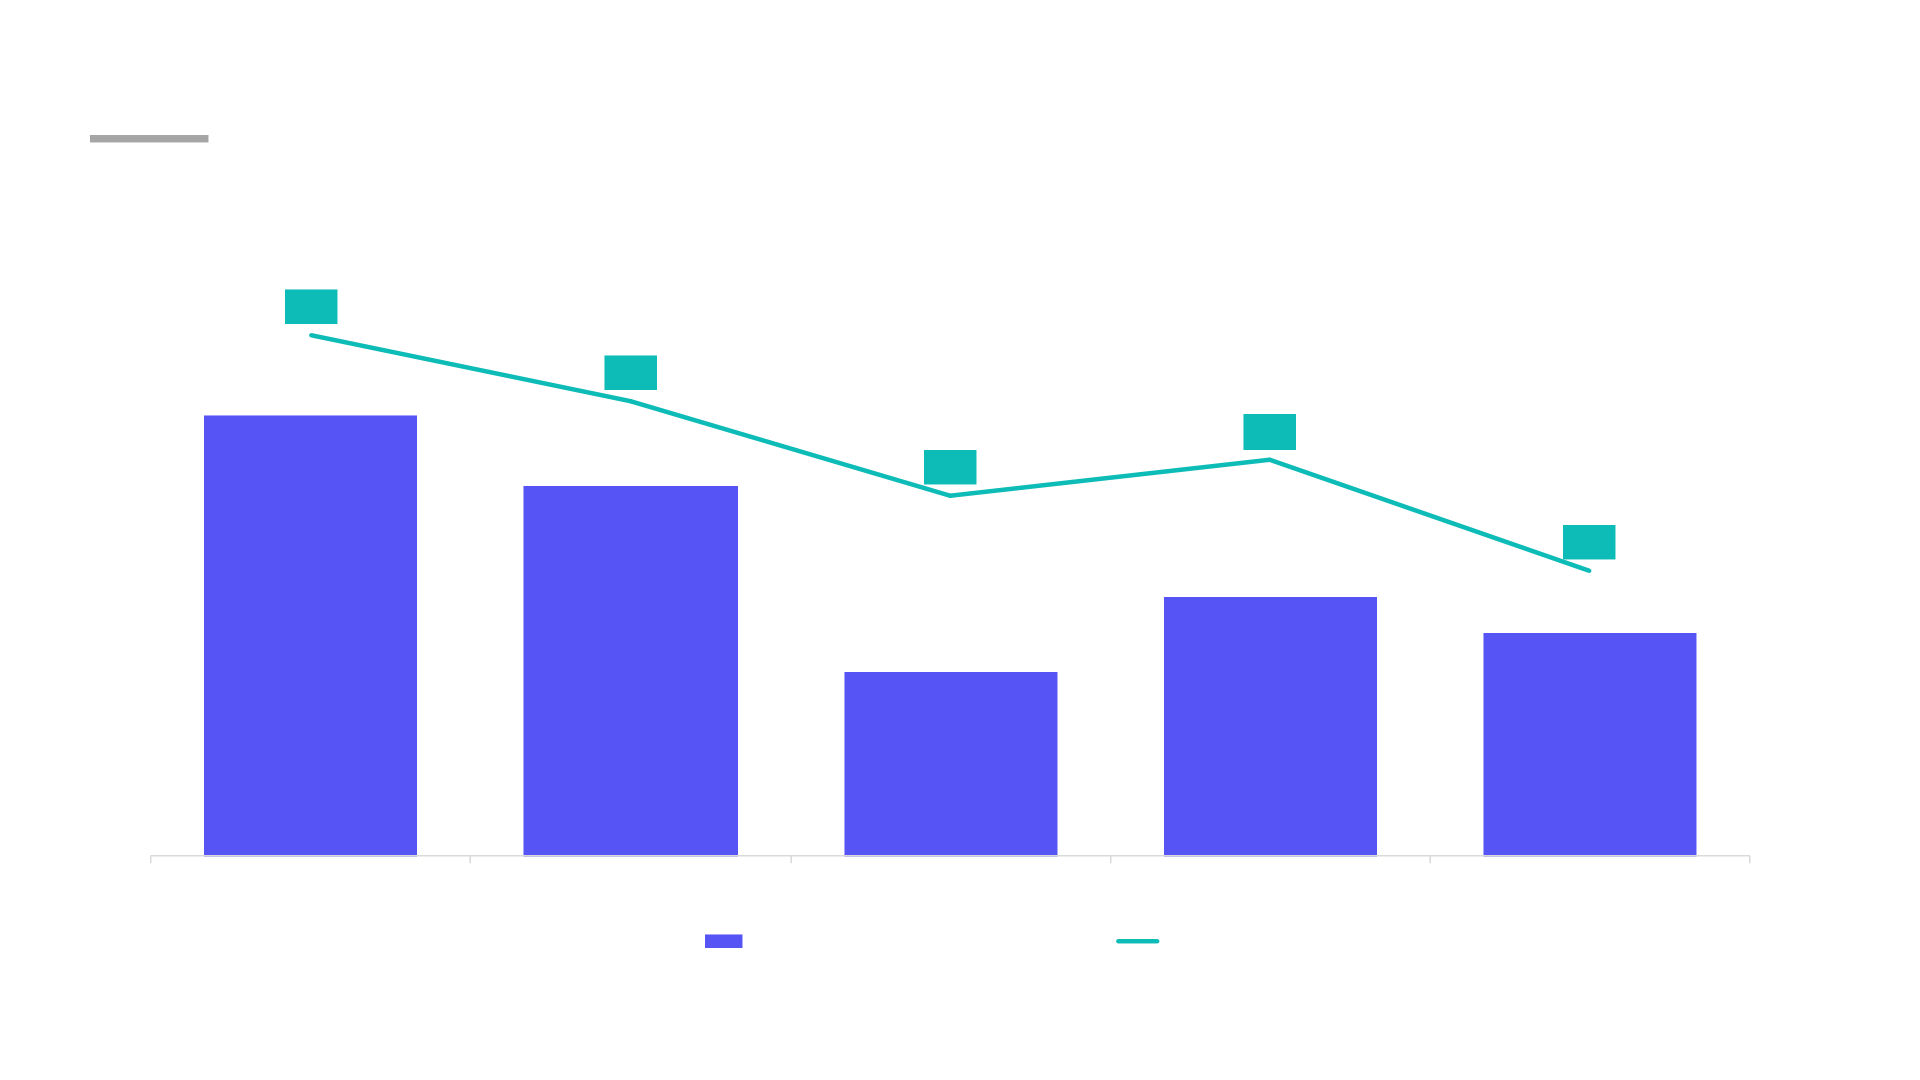
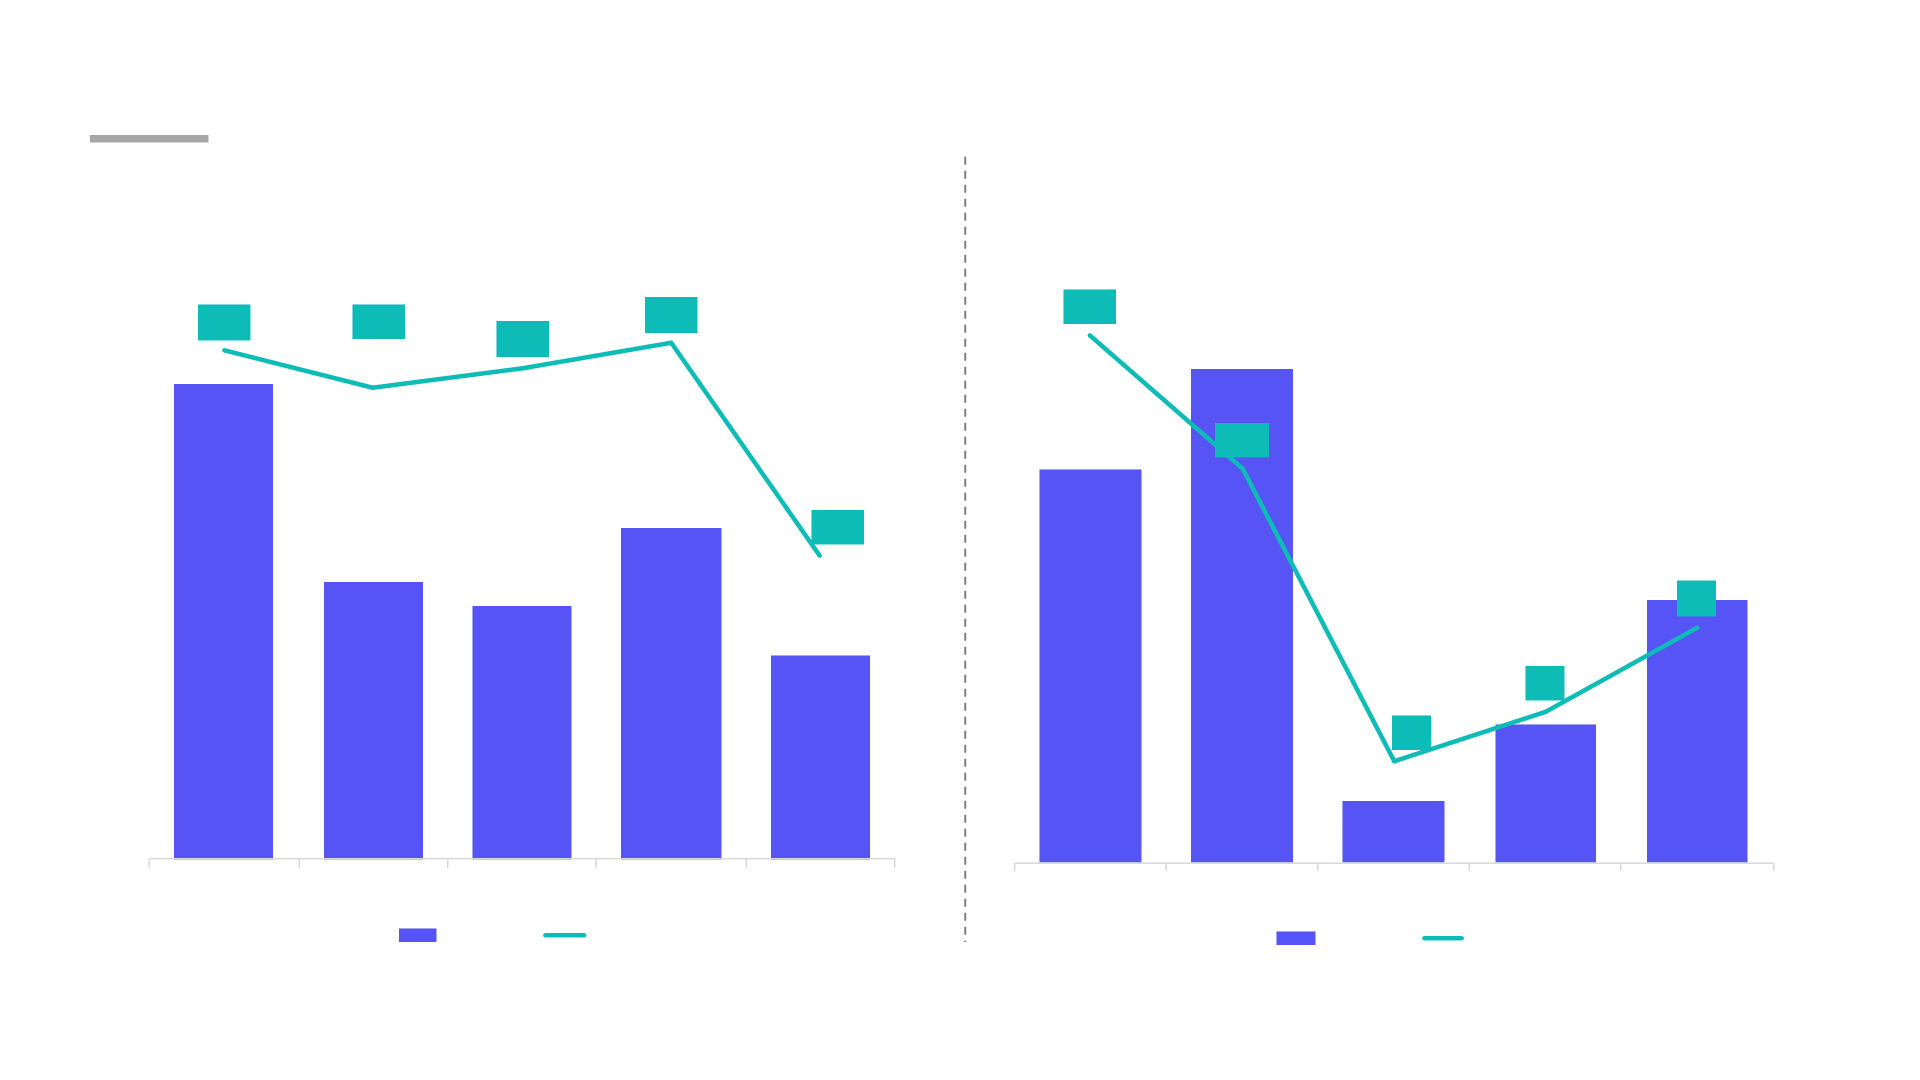
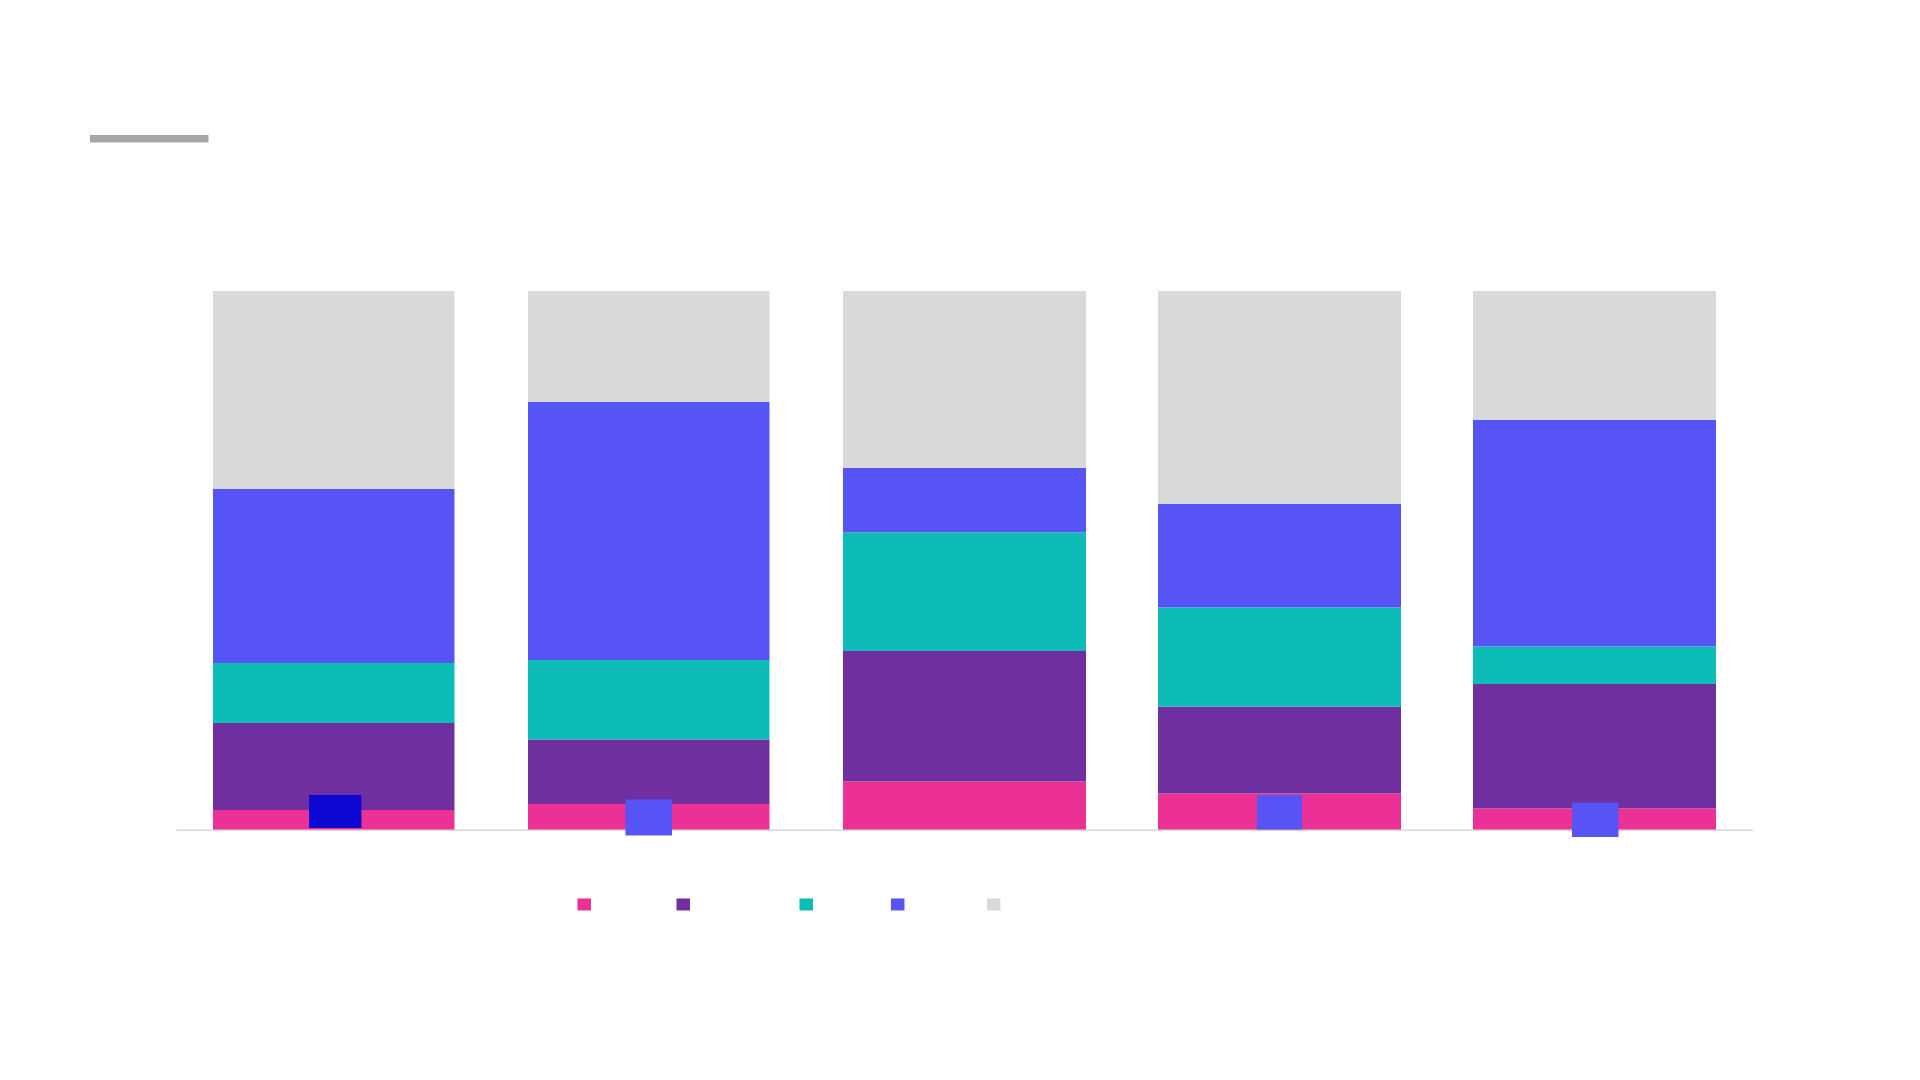
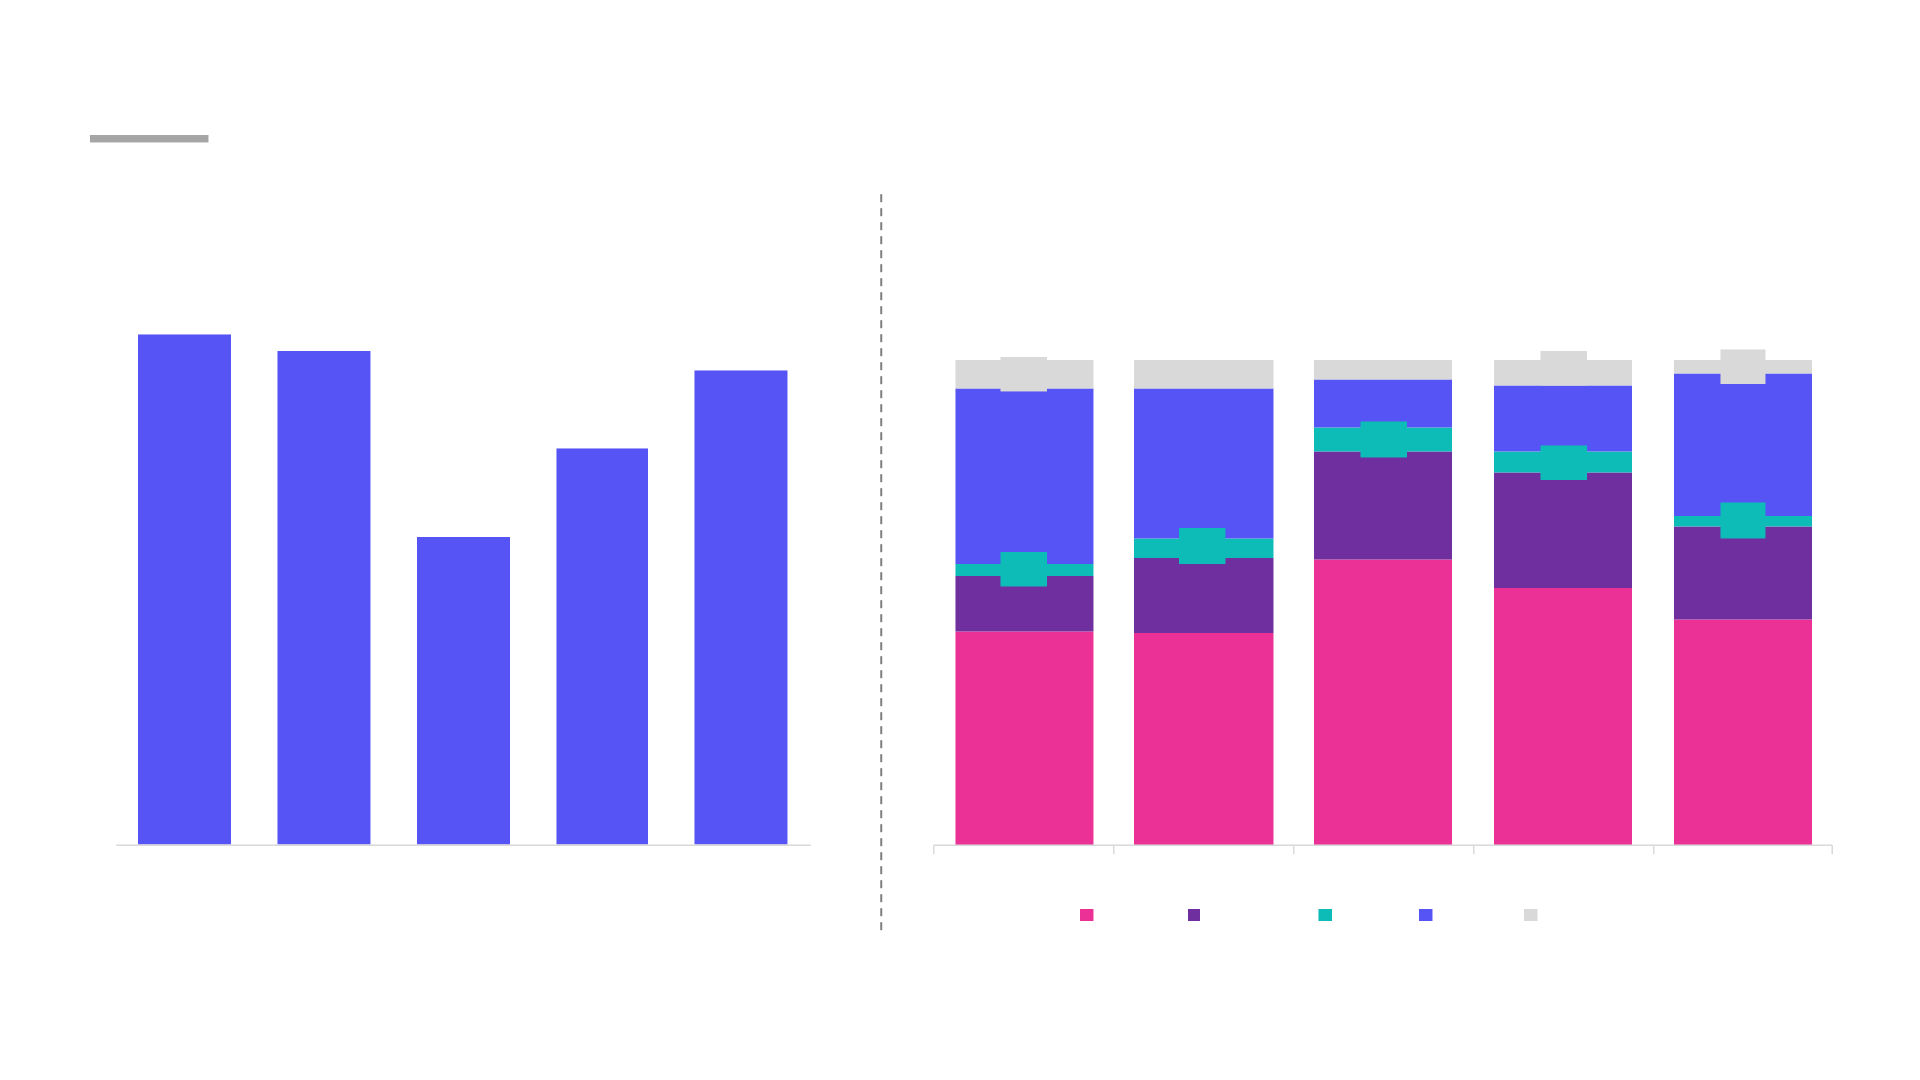
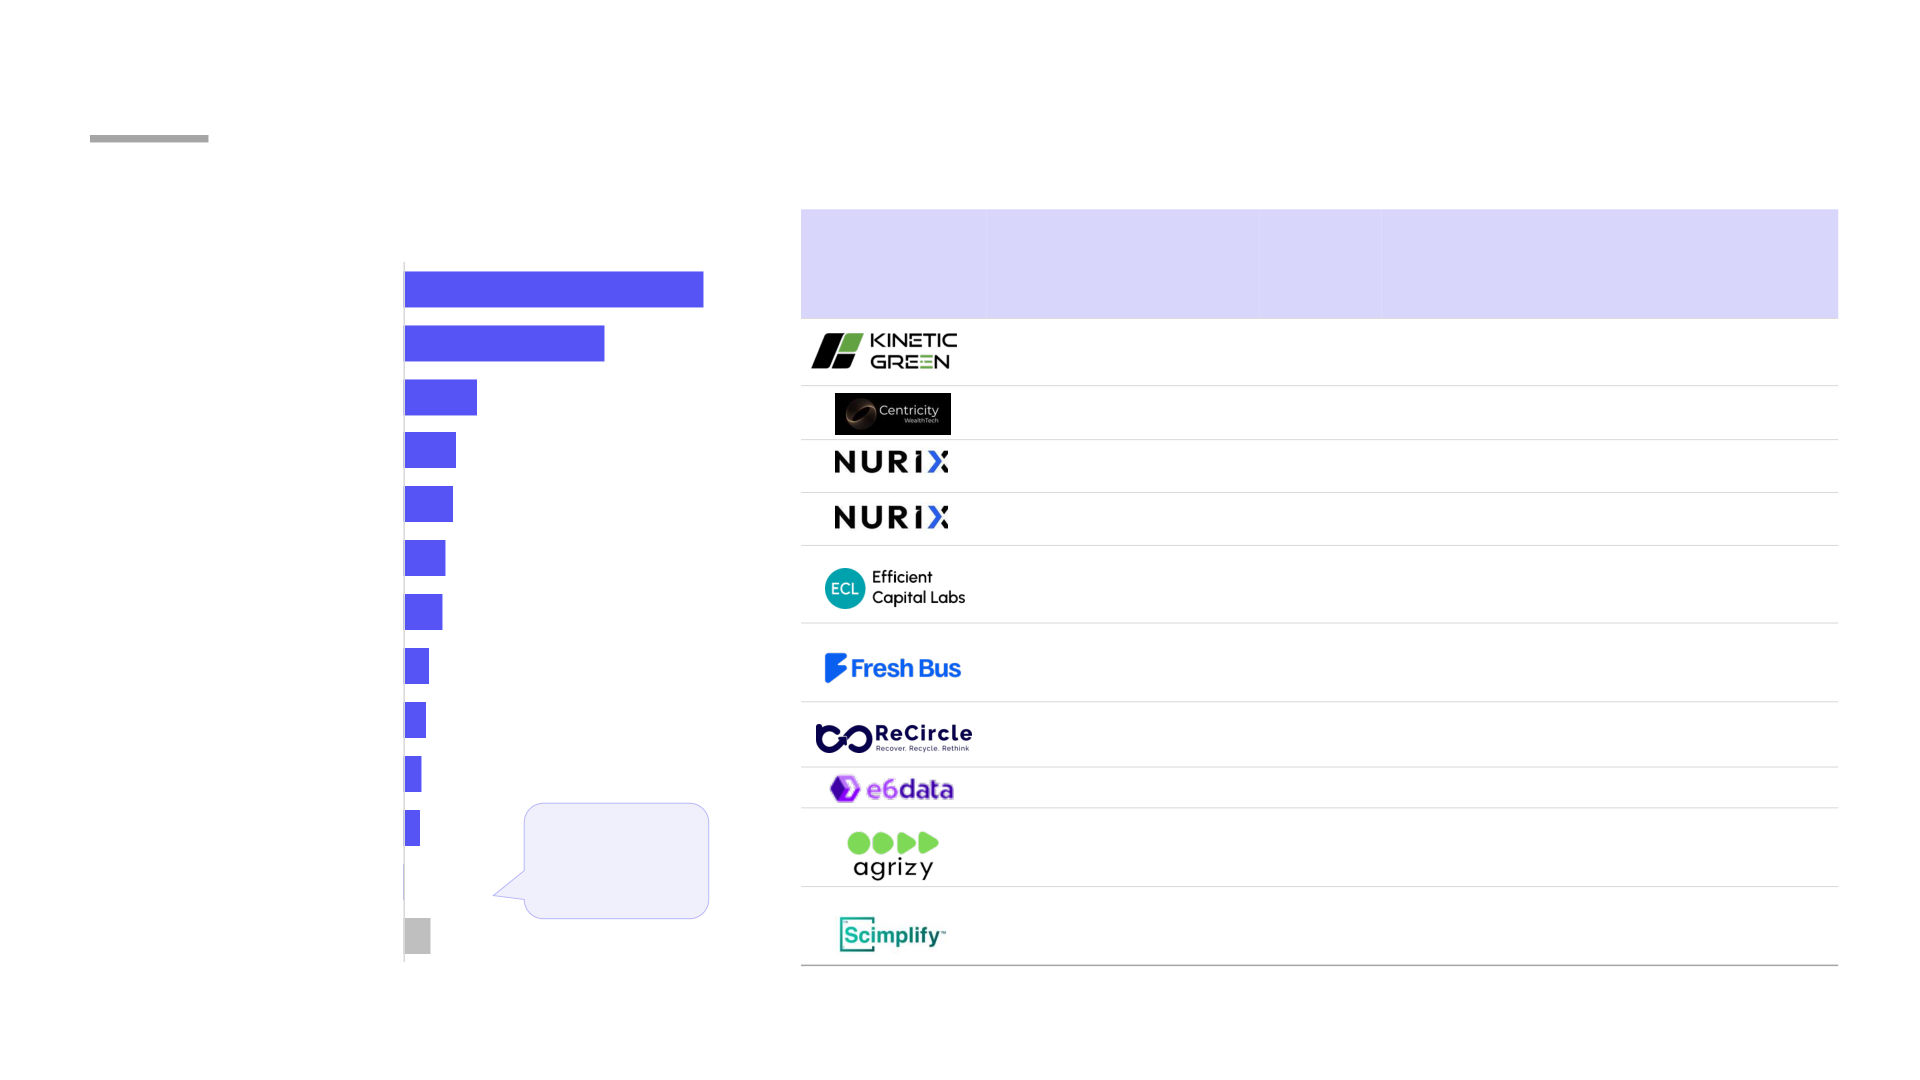
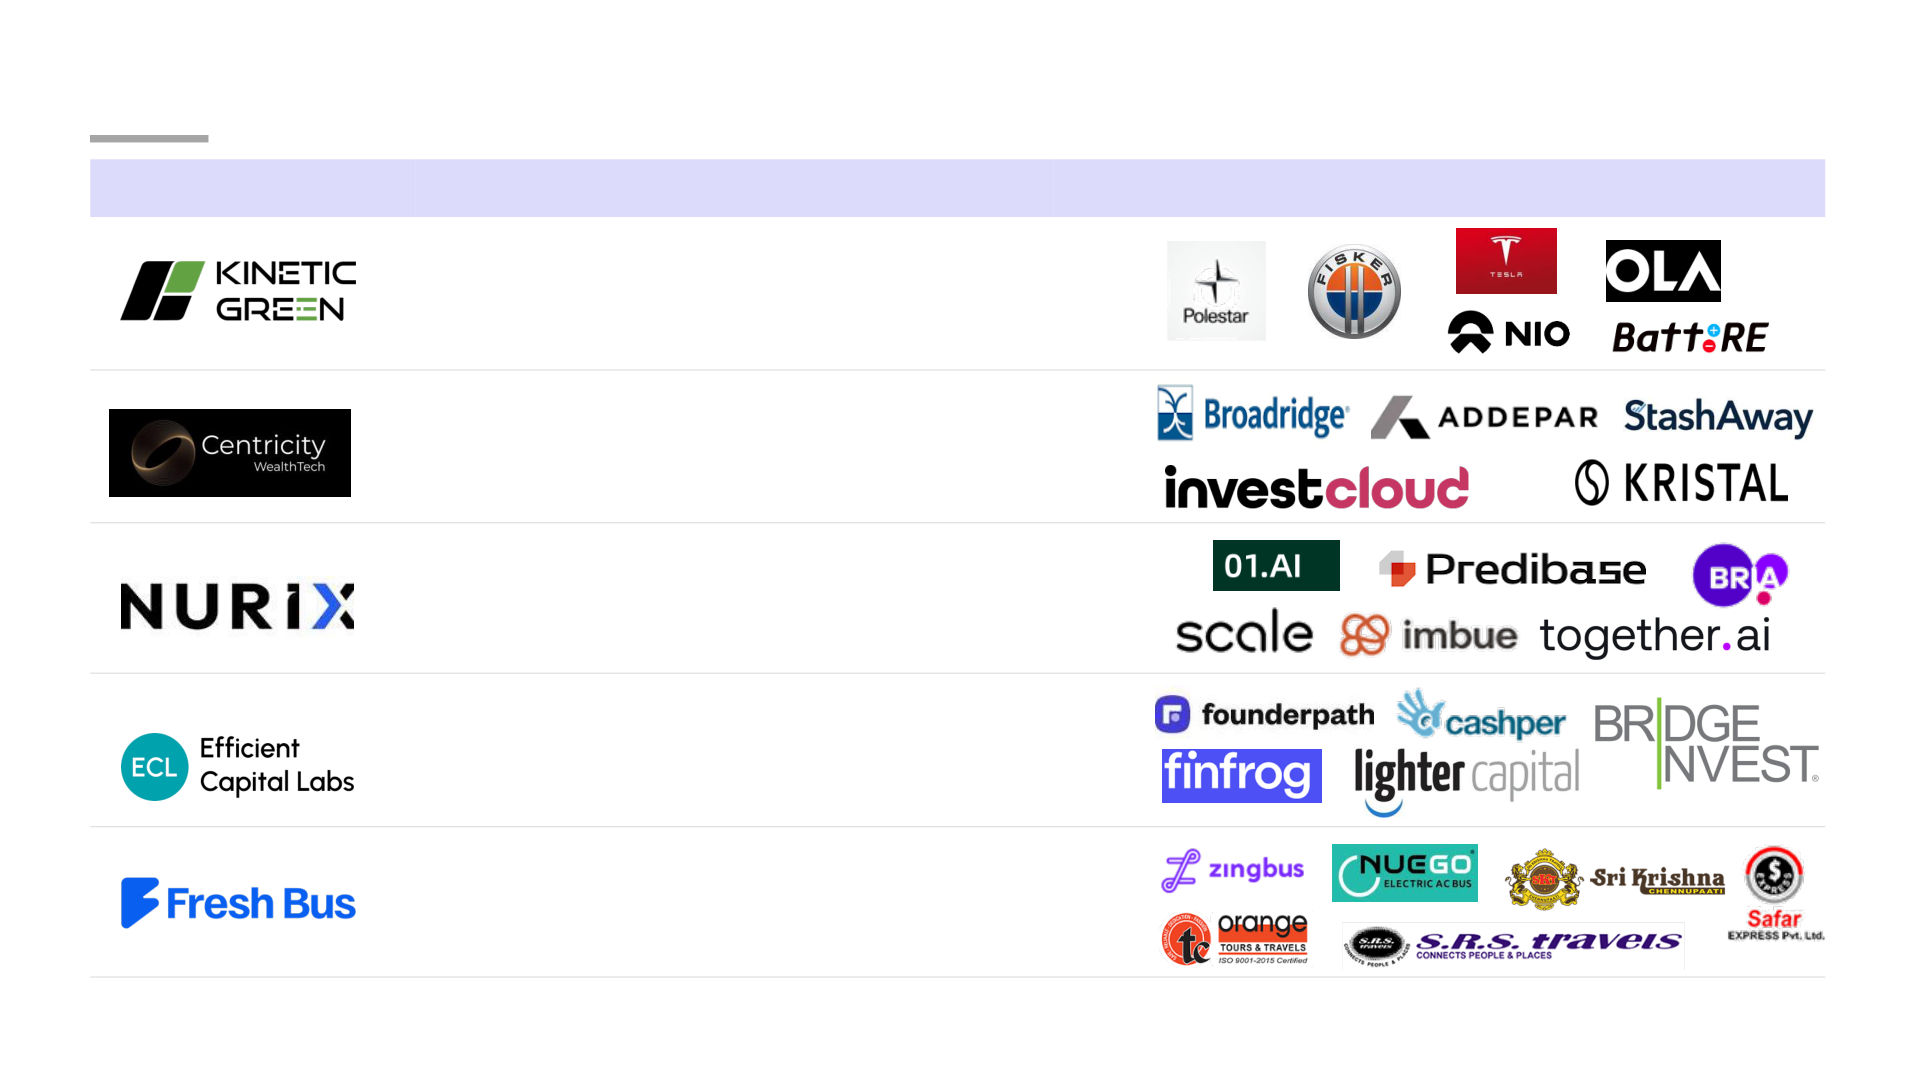
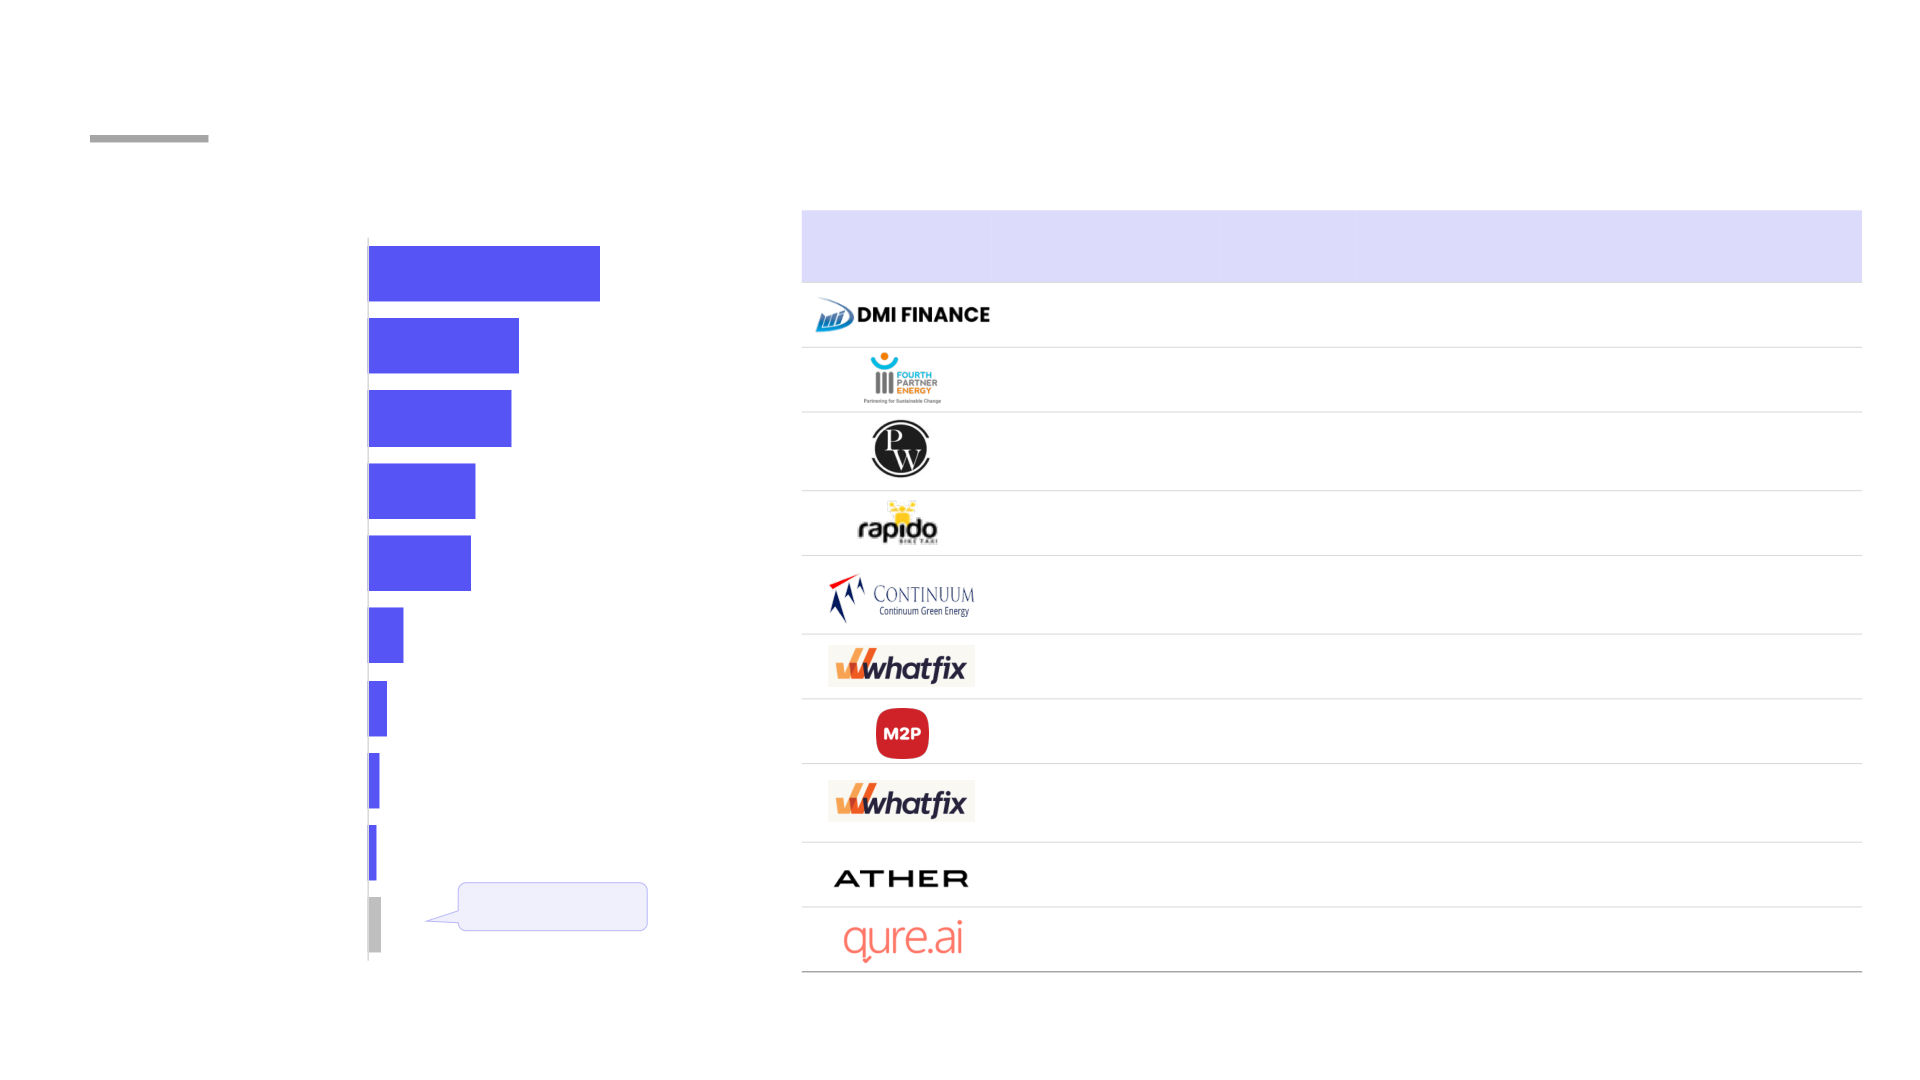
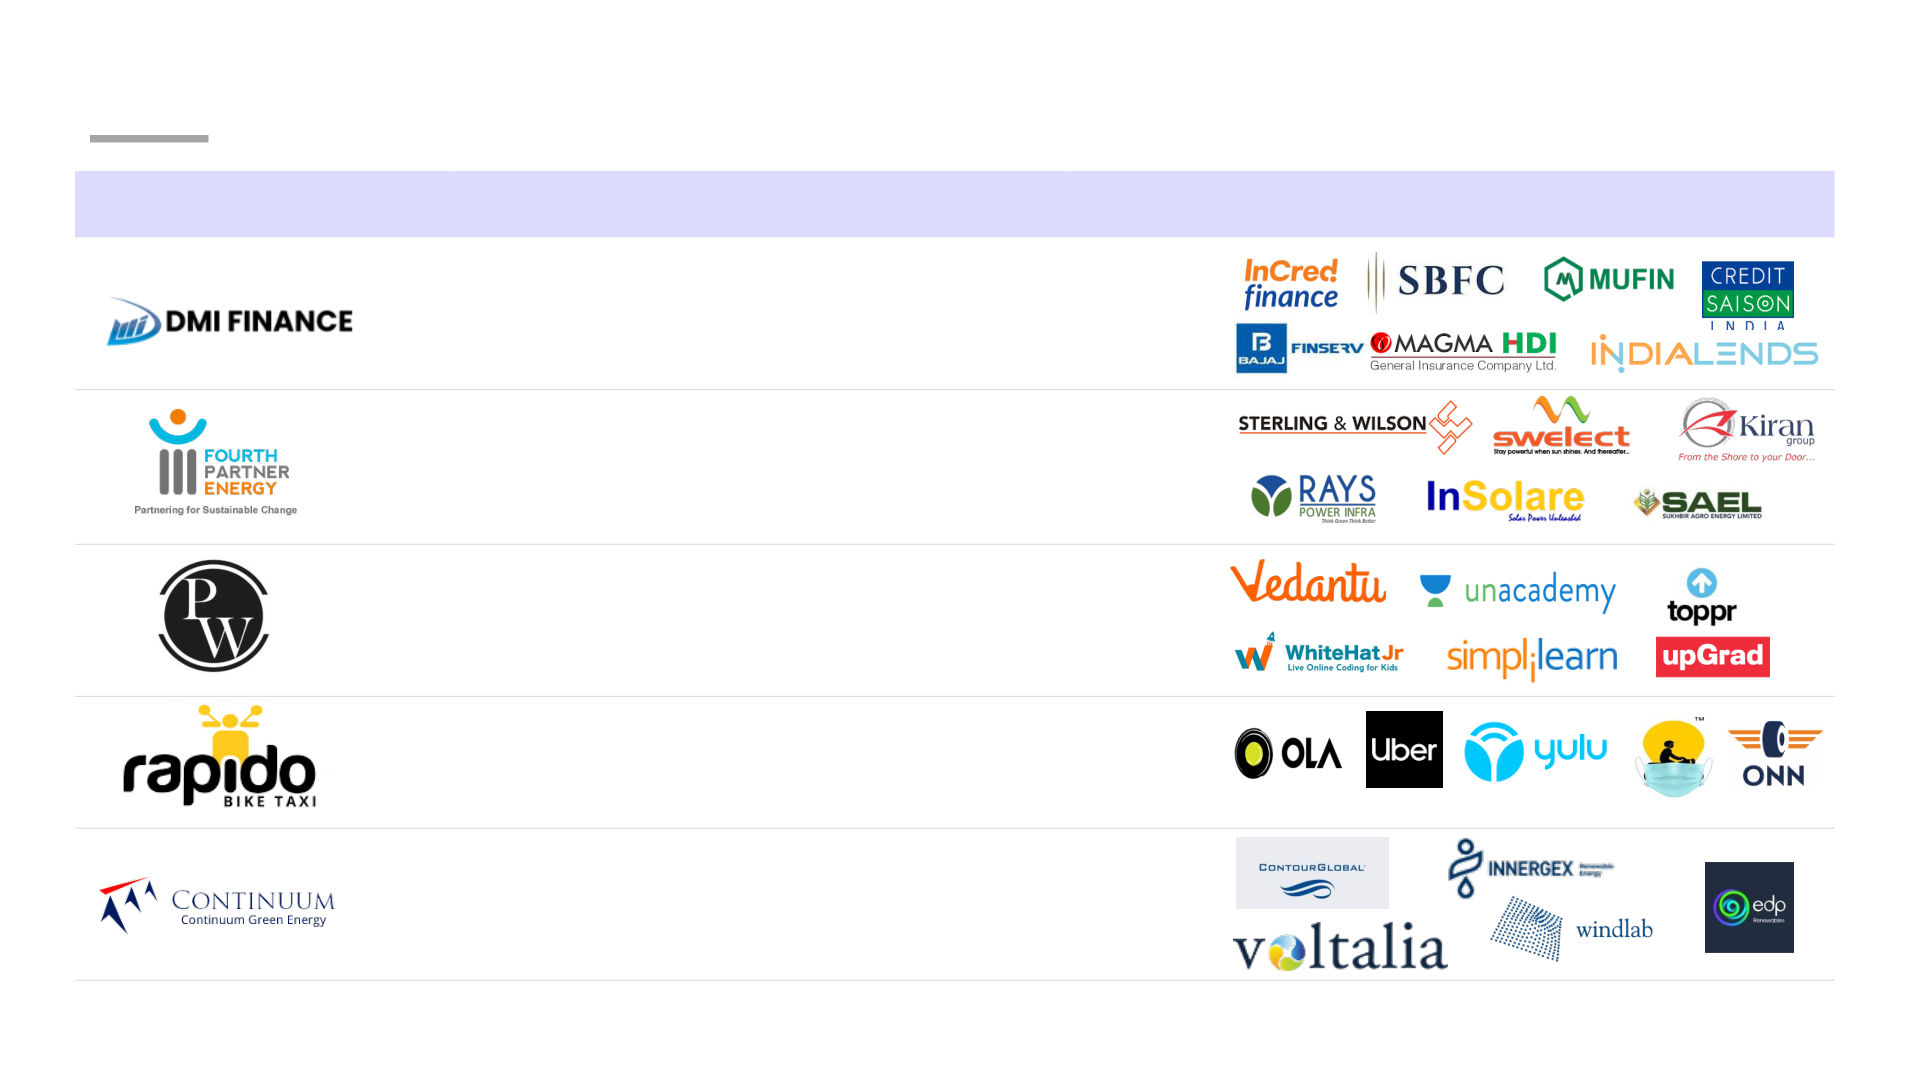
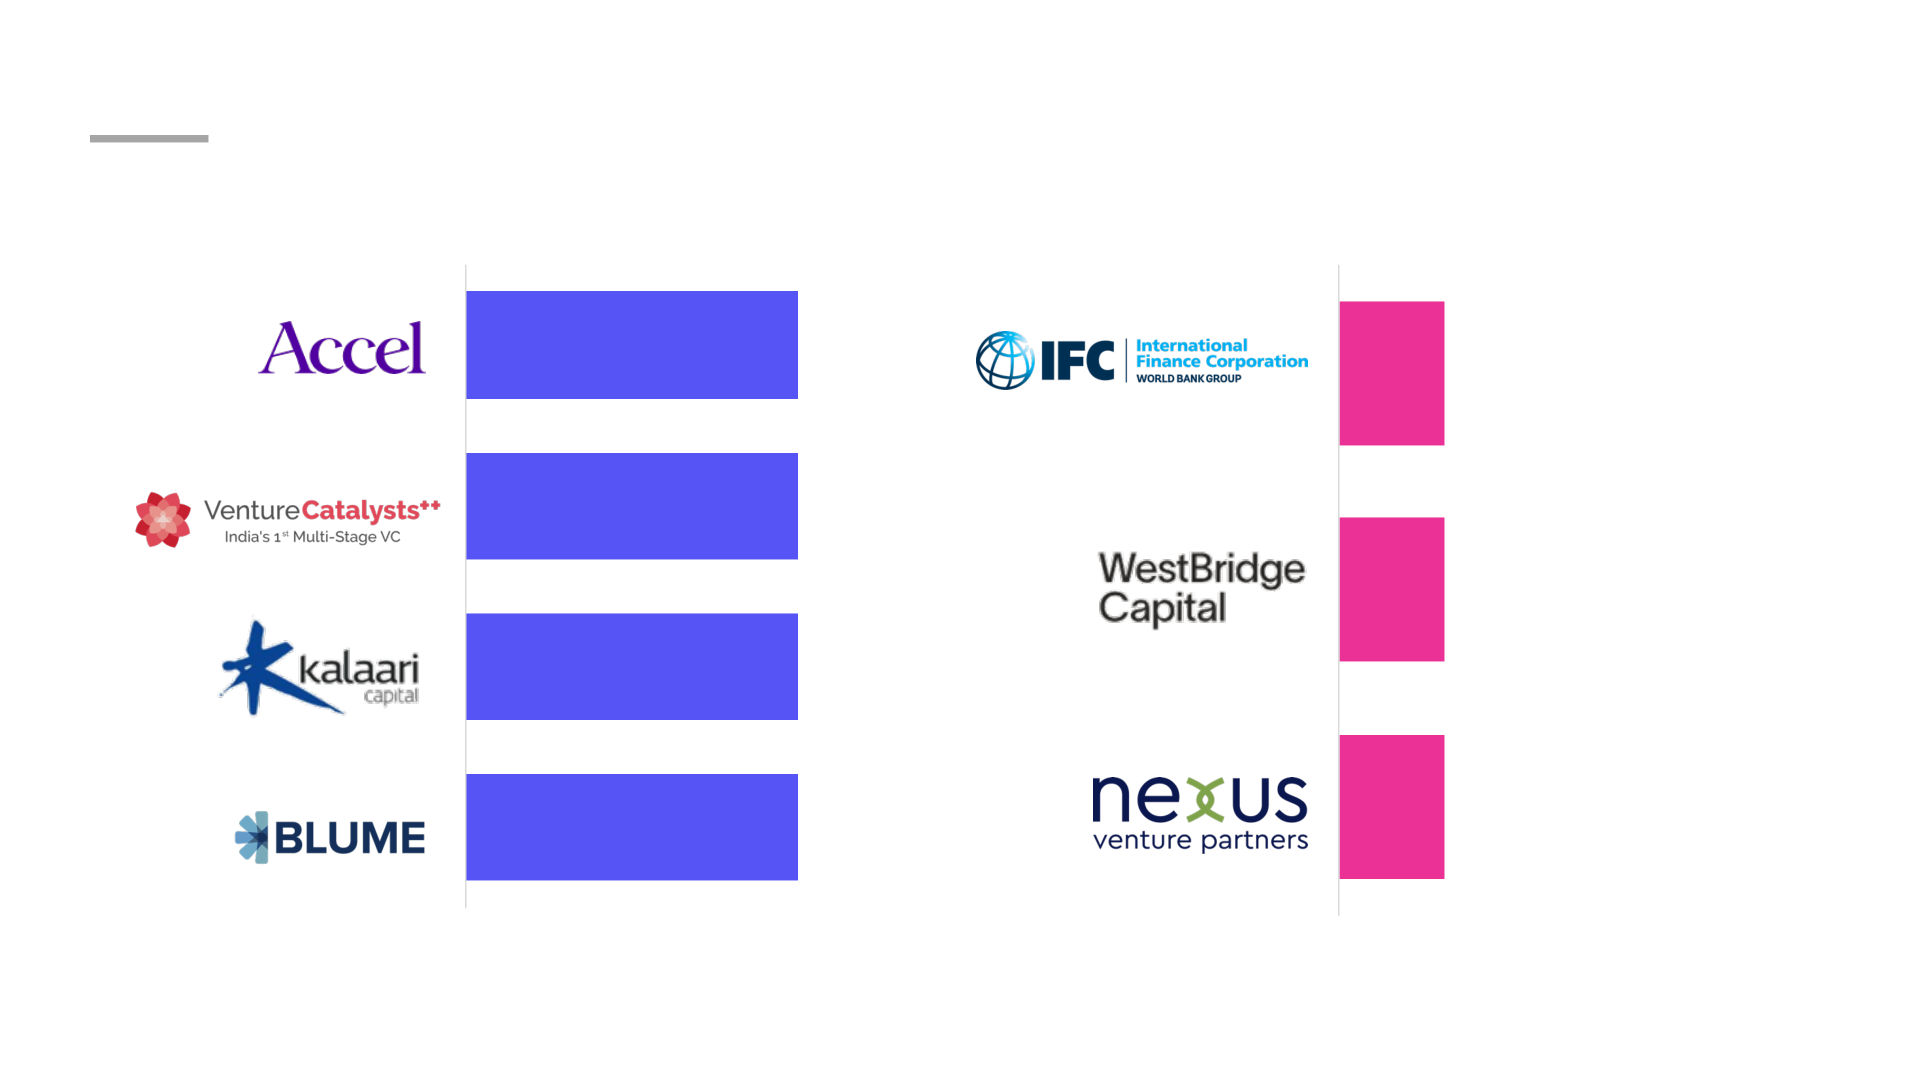
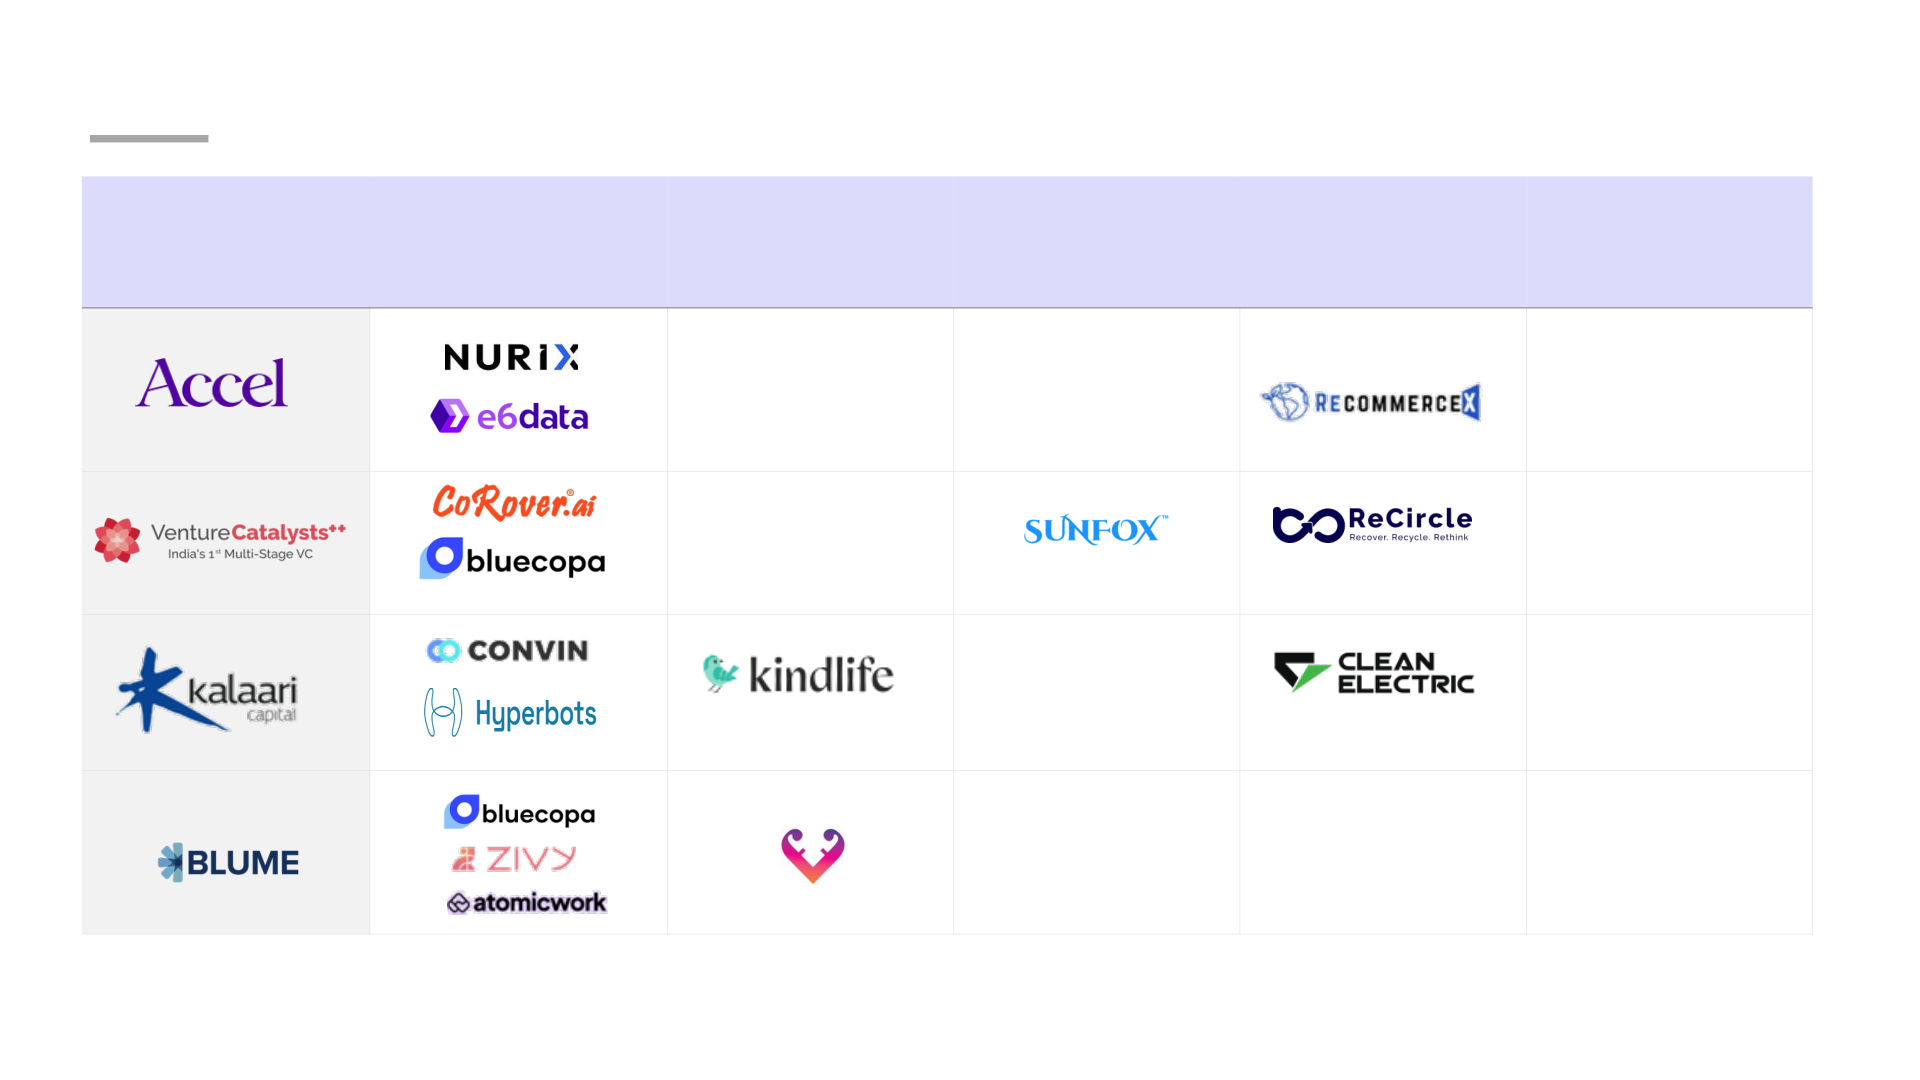
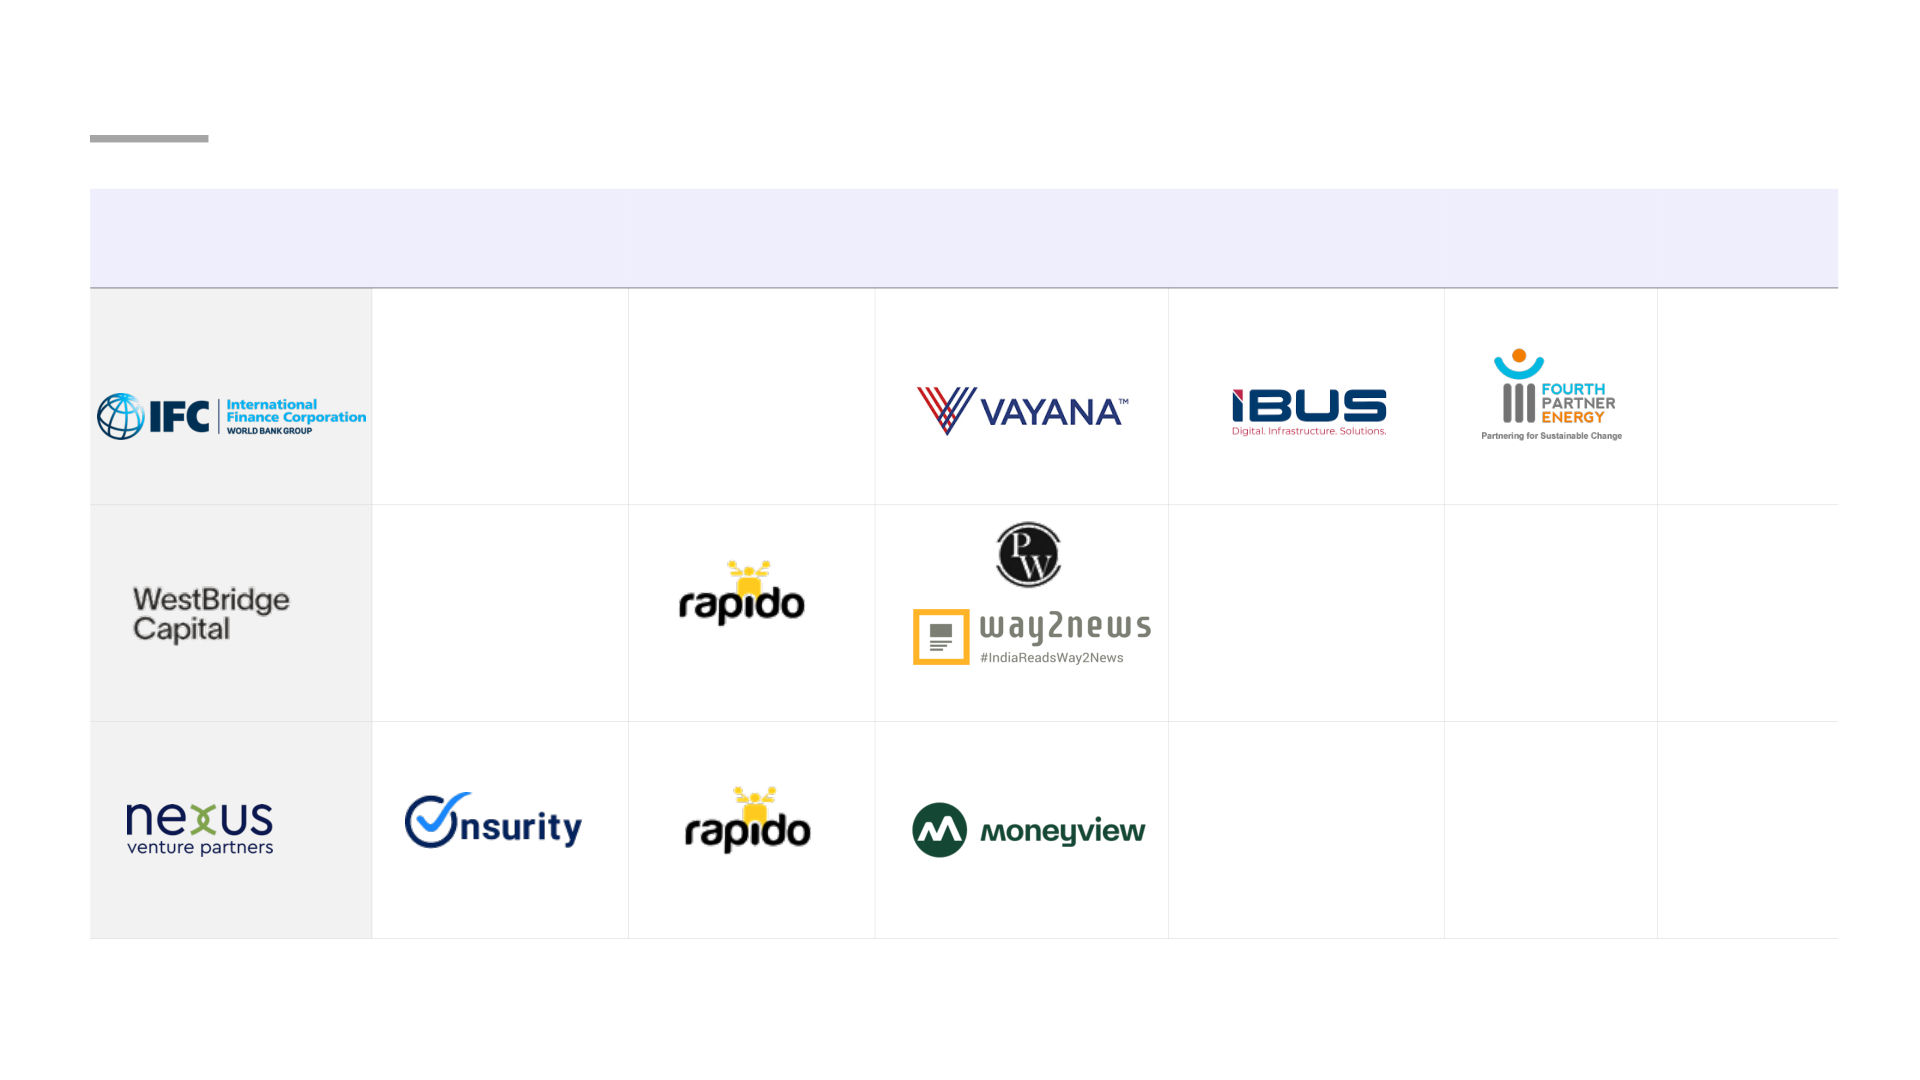
INDIA QUARTERLY INVESTMENT ANALYSIS Q3 CY 2024 October 2024 Foreword Projected to reach US $ 10 T economy by 2032 , India’s economy remains resilient, fueled by reforms that improve the business landscape . Its strategic geopolitical position enhances its appeal as an investment Praneet Singhal hub . Initiatives such as 'Make in India,' 'Startup India’, and Production Linked Incentive (PLI) schemes strengthen its manufacturing capabilities . India is on track to surpass major economies like the U . S . A . , Director China, Germany, South Korea, and Japan in manufacturing . However, in Q 3 CY 2024 , dealmaking activity Financial Investors & fell by 13 - 14 % from the previous quarter, indicating cautious investor sentiment . 1Alpha In equity investments, growth - stage funding has led the funding landscape, representing ~ 25 % of total funding rounds, particularly in sectors like SaaS/AI and Energy . Startups with solid fundamental metrics, mature operating metrics, and sustainable growth characteristics are well - positioned for expansion, supported by a strong user base and brand identity . Despite a positive long - term outlook, Q 3 has seen a ~ 30 % decline in deal volume, coupled with a ~ 20 % Abhilasha Jaju increase in average deal size, signaling a shift toward high - ticket deal - making in quality assets . Overall, debt Director has gained traction, contributing ~ 40 % to total deal amounts . Startups with proven business models and an Financial Investors and established customer base are well placed to benefit from this trend, as investors seek to support category Banking, Financial leaders with scalable models and reasonable growth projections . Services, & Insurance In addition to a strengthening economy, supportive government policies and continuous infrastructure improvements enhance the investment climate in India . The relentless focus on technological advancement and innovation, fueled by startups, remains a key catalyst for growth . This report aims to uncover some of the key trends during Q 3 CY 2024 . At 1 Lattice, we hold an optimistic outlook, believing that this report will provide valuable insights . We eagerly anticipate the opportunity to Devmalya Mukherjee engage in an open dialogue with our partners across diverse industries, as we exchange notes and delve deeper into these matters while closely monitoring the evolving situation . Director Financial Investors © 1Lattice | 2 Product in Spotlight - Pulse This report was curated using our cutting - edge product, DealPulse DealPulse provides comprehensive visibility into your industry benchmarks and best practices. From tracking macro indicators and government regulations to specific operating metrics and best practices of your peers, from monitoring pricing strategies to evaluating brand reputation through sentiment analysis and social listening, DealPulse covers all bases to help you adapt your strategies for beating the industry standards. This report offers invaluable insights into India's robust economy, driven by ongoing reforms that enhance the business environment. In this report, DealPulse empowered our expert team with comprehensive research tools to analyze the overall funding landscape, investor behavior patterns, and deal sizes. By leveraging DealPulse , we gained a detailed understanding of the factors driving investment trends and the opportunities they present. This comprehensive approach allowed us to present a thorough analysis of the current investment landscape in India, offering you the insights needed to navigate and capitalize on emerging opportunities. Equip your business with the intelligence provided by DealPulse to stay ahead in today's competitive market, consistently outperform industry standards, and achieve sustainable success. Key highlights Funding Deal v olume Average ticket size US$ 43.6M US $ 10 B 229 SNAPSHOT Q3 CY 2024 Top funded sector Most funded stage* Total equity funding BFSI Growth US$ 5.8B Note(s): *Most funded stage is within equity investments Key takeaways Funding landscape and investment dynamics • Startups raised US $ 10 B across 229 deals in Q 3 CY 24 , signaling a decline in total funding (~ 15 % ) on a Q - on - Q basis ; Deal volume decreased from 318 to 229 deals ( ~ 30 % ) compared to Q 2 CY 24 • BFSI sector received the highest funding of US $ 3 . 5 B, followed by Telecom sector receiving a funding of US $ 2 B, and SaaS/AI sector receiving funding of US $ 1 . 2 B − Investments across early stage experienced a decrease in volume by ~ 5 % compared to Q 2 • Early - stag e deal volume slightly decreased from ~ 55 % to ~ 45 % and debt deals volume increased from 15 % to ~ 30 % ; indicating that the VC/PE firms are looking to be more interested in safer options due to continuing global uncertainty and geopolitical tensions • Average deal size increased by ~ 20 % to US $ 43 . 6 M compared to previous quarter Sectoral focus and key deals • Highest investments in Q 3 CY 24 were for ATC India (Telecom) and * NaBFID (BFSI) with funding of US $ 2 B and US $ 599 M respectively • For the current quarter, SaaS/AI was the most attractive sector for early - stage (US $ 142 M) and growth - stage investments (~US $ 650 M) • Late - stage investments were mainly driven by the Ecommerce & Listing Platforms sector (~US $ 650 M) • Accel, Venture Catalyst, Kalaari Capital, and Blume Ventures were the most prominent investors for early - stage investments in Q 3 CY 24 with 4 deals each • IFC, WestBridge Capital, and Nexus Venture Partners were the most prominent investors for growth stage investments in Q 3 CY 24 with 3 deals each Note(s): * NaBFID – National Bank for Financing Infrastructure and Development Funding market by funding round Debt (US$ 4.1B) and Buyout round (US$ 2B) funding were the highest contributors to overall funding raised in Q3 CY24 Funding market round wise break - up (US$ B, Q3 CY24) Total funding size: US$ 10B 0.7 0.9 Series G Series E 4.1 2.0 Debt Buyout 0.4 0.7 0.6 Series D PIPE Series B 0.2 0.2 0.2 Seed Series A Series C Source(s): Statistical reports, industry reports, secondary research, 1Lattice analysis © 1Lattice | 6 Funding market by sectors BFSI (US$ 3.5B) saw the most interest from investors, followed by Telecom (US$ 2B) in Q3 CY24 Funding market segment wise break - up (US$ B, Q3 CY24) Total funding size: US$ 10B 1.2 0.6 0.5 2.0 3.5 0.2 0.4 1.1 0.3 0.03 0.1 0.03 0.03 * Note(s): *Others include mining, restaurants, education, etc. © 1Lattice | 7 Source(s): Statistical reports, industry reports, secondary research, 1Lattice analysis Funding market by sectors SaaS/AI sector saw the highest deal volume from investors (~61 deals), followed by BFSI (~51 deals) in Q3 CY24 Funding market segment wise break - up (#, Q3 CY24) Total deal volume: 229 13 12 34 61 51 8 11 * 5 5 16 8 3 2 Note(s): *Others include mining, restaurants, education, etc. Source(s): Statistical reports, industry reports, secondary research, 1Lattice analysis © 1Lattice | 8 Top 10 highest funded companies ATC India has received the highest investment (~US$ 2B), followed by NaBFID (~US$ 600M) in Q3 CY 2024 2,000* 599** Top 10 highest funded companies of Q3 453** CY 2024 (US$ M) 410** 210 275 360** 333** 334 340 Note(s): 1 – *Buyout deal; **Debt deal - Equity deals - Buyout deals - Debt deals © 1Lattice | 9 Source(s): 1Lattice Deals Database Agenda Deal landscape in Q3 CY24 Key deals and investment themes Key investors Investment amount and # deals Investments in Q3 CY24 have declined, breaking the trend from Q1 CY24 to Q2 CY24 Investment amount (US$ B) and # deals (Q3 CY23 – Q3 CY24) 25.0 450 419 400 366 20.0 350 318 290 300 15.0 229 250 200 10.0 19.7 150 16.5 11.6 100 5.0 10.0 8.2 50 0.0 0 Q3 CY23 Q4 CY23 Q1 CY24 Q2 CY24 Q3 CY24 Amount Deals Note(s): Chart includes early (Pre - seed, seed, pre - series and Series A), growth (Series B, C, D and E), late (Series F onwards) stage inv estments, PIPE, Buyout and debt (Conventional, Venture, etc.) Source(s): 1Lattice Deals Database © 1Lattice | 11 Equity vs debt investments Equity investments saw a drop from previous quarters to US$ 5.8B, while there was a surge in debt deals to US$ 4.2B in Q3 CY24 Equity investments (US$ B) and # deals Debt investments (US$ B) and # deals (Q3 CY23 – Q2 CY24) (Q3 CY23 – Q3 CY24) 150 275 271 251 261 112 162 67 7.9 13.5 6.3 43 9.4 7.9 4.2 7.2 29 5.8 2.2 1.0 Q3 CY23 Q4 CY23 Q1 CY24 Q2 CY24 Q3 CY24 Q3 CY23 Q4 CY23 Q1 CY24 Q2 CY24 Q3 CY24 Amount Deals Amount Deals Note(s):Equity includes early (Pre - seed, seed, pre - series and Series A), growth stage (Series B, C, D and E), late (Series F onw ards) stage investments, others (PIPE and buyout) and debt includes conventional debt, venture debt, etc. Source(s): 1Lattice Deals Database © 1Lattice | 12 Stage - wise investments Debt deals grew from ~US$ 2.2B to ~US$ 4.2B compared to the previous quarter: Growth stage deals amounted to ~US$ 2.3B in Q3 CY24 Investment amount ( US$ B , Q3 CY23 – Q3 CY24) N = 419 366 290 318 229 3.4 2.4 2.7 7.2 4.5 1.0 7.9 4.2 2.2 6.3 1.8 2.1 0.7 2.2 2.4 2.0 2.3 1.9 3.2 2.0 0.7 0.7 0.8 0.8 0.4 Q3 CY23 Q4 CY23 Q1 CY24 Q2 CY24 Q3 CY24 Early Growth Late Debt Others (PIPE & Buyout) Note(s): Chart includes early (Pre - seed, seed, pre - series and Series A), growth (Series B, C, D and E), late (Series F onwards) stage inv estments, others (PIPE and buyout) and debt (Conventional, Venture, etc.); *Number of deals Source(s): 1Lattice Deals Database © 1Lattice | 13 Average deal size Average deal size rose to ~US$ 44M from ~US$ 36M with total deals dropping to 229, down from 318 in Q2 CY24 Deal volume by stage Average deal size (%, Q3 CY23 – Q3 CY24 ) (US$ M, Q3 CY23 – Q3 CY24 ) 46.9 45.3 419 366 290 318 229 43.6 3% 5% 4% 6% 6% 10% 14% 36.4 5% 29% 30% 4% 36% 22% 28.3 2% 24% 4% 2% 19% 15% 12% 59% 53% 47% 44% 43% Q3 CY23 Q4 CY23 Q1 CY24 Q2 CY24 Q3 CY24 Q3 CY23 Q4 CY23 Q1 CY24 Q2 CY24 Q3 CY24 Early Growth Late Debt Others* Note(s): Stage of investment here is decided by the round of investment. Pre - seed, seed, pre - series and Series A are classified as Early, Series B, C, D and E are classified as Growth, Series F onwards are classified as Late, © 1Lattice | 14 Debt includes deals with Conventional, Venture, etc. *Others include deals with undisclosed round, PIPE, Buyout etc. Source(s): 1Lattice Deals Database Agenda Deal landscape in Q3 CY24 Key deals and investment themes Key investors Top 10 investments in Q2 CY24 Top 10 investments in Q3 CY24 Top 10 investments in Q3 CY24 Amount Company Sector Funding stage Key Investors (US$ M) 2,000 Buyout Data Infrastructure Trust Telecom BFSI 599 Debt Others FMCG 453 Debt Others BFSI 410 Debt Others BFSI 360 Debt Others General Catalyst Partners, Dragon Capital, Epiq Capital, Ecommerce & listing platforms 340 Late StepStone Group, Lightspeed Venture Partners, DST Global, Contrary Capital BFSI 334 Growth MUFG Bank BFSI 333 Debt Others Energy 275 Growth IFC, DEG, Asian Development Bank Hornbill Capital, WestBridge Capital, Lightspeed Venture Consumer app & platforms 210 Growth Partners, GSV Ventures © 1Lattice | 16 Source(s): 1Lattice Deals Database Early - stage investments SaaS/AI received the highest funding of ~US$ 142M among early - stage investments; Kinetic Green received the highest funding within the sector Top 10 early - stage investments in Q3 CY24 Early - stage investments by sector (US$ M, Q3 CY24) Amount Company Sector Key Investors (US$ M) SaaS/AI 142 Ecommerce & listing Ecommerce & listing platforms 95 25 Greater Pacific Capital platforms Energy 34 Lightspeed Venture Partners, Paramark SaaS/AI 20 Ventures BFSI 25 SaaS/AI 15* Accel, General Catalyst Partners Healthcare & Life Sciences 23 SaaS/AI 13* Accel, General Catalyst Partners Consumer app & platforms 20 QED Investors, 645 Ventures, Eudemian BFSI 11 Ventures, Generalist, Riverside Ventures Manufacturing 18 Alteria Capital, Moniv Mobility, Shell Ventures, Transportation & logistics 11 FMCG 12 River Walking holdings Transportation & logistics 11 Energy 11** Venture catalysts Retail 9 SaaS/AI 10 Accel, BEENEXT Others include Engg. & Construction 8 Ecommerce & listing Accion Venture Labs, Omnivore, Capria sectors such as 10 spacetech , platforms ventures, Ankur Capital Telecom education, housing 1 services, etc. Omnivore, Bertelsmann India Investments, Manufacturing 10 Others 12 3one4 Capital, BEENEXT 0 50 100 150 Note(s): Early - stage investments include Pre - seed, Seed, Pre - series A and Series A; * Nurix has secured funding twice: $12M in seed funding and $15M in Series A; ** The deal amount has been estimated as the exact figure was undisclosed © 1Lattice | 17 Source(s): 1Lattice Deals Database Top early - stage investments Top funded early - stage startups with their competitors Company Description Competitors Offers a wide range of electric vehicles, including electric three - wheelers and two - wheelers. SaaS - based investment management platform including digital transactional capabilities for a diversified product suite AI agents for enterprise workflow management Online platform offering revenue - based loans to SaaS businesses Bengaluru - based intercity bus startup Source(s): 1Lattice Deals Database © 1Lattice | 18 Growth - stage investments SaaS/AI sector dominated growth - stage investments with funding of ~US$ 650M, followed by Energy sector with ~US$ 425M Growth - stage investments by sector Top 10 growth - stage investments in Q3 CY24 (US$ M, Q3 CY24) Amount Company Sector Key Investors (US$ M) SaaS/AI 650 BFSI 334 MUFG Bank Energy 425 Energy 275 IFC, DEG, Asian Development Bank BFSI 401 Consumer app & Hornbill Capital, WestBridge Capital, Lightspeed 210 platforms Venture Partners, GSV Ventures Consumer app & platforms 301 Ecommerce & listing WestBridge Capital, Nexus Venture Partners, Think 200 platforms Investments, Invus Financial Advisors Ecommerce & listing platforms 288 Energy 150 Just Climate Manufacturing 99 SaaS/AI 125* Warburg Pincus, SoftBank Group Healthcare & Life Sciences 52 SaaS/AI 102 Flourish Ventures, Helios Investment Partners Telecom 34 SaaS/AI 100* Warburg Pincus, SoftBank Group Retail 25 Manufacturing 72 NIIF Includes the HoReCa sector Others 35 Lightspeed Venture Partners, 360 ONE, Novo SaaS/AI 65 Holdings, Kae Capital, HealthQuad , TeamFund Note(s): Growth - stage investments include Series B, C, D and E; * Whatfix has secured funding in two tranches © 1Lattice | 19 Source(s): 1Lattice Deals Database Top growth - stage investments Top funded growth - stage startups with their competitors Company Description Competitors Provider of Consumer and SME Loans On - grid, off - grid solar solutions and solar products Online platform offering live courses for JEE, NEET, and classes App - based ride - hailing aggregator Wind farm developer Source(s): 1Lattice Deals Database © 1Lattice | 20 Late - stage investment Late - stage investments were driven by Ecommerce & Listing Platforms sector (~US$ 649.2M) Late - stage investment, by sector Top late - stage investments in Q3 CY24 (US$ M, Q3 CY24) Amount Company Sector Key Investors (US$ M) Ecommerce & listing General Catalyst Partners, Dragon Capital, 649.2 platforms Ecommerce & Epiq Capital, StepStone Group, Lightspeed 340 Venture Partners, DST Global, Contrary listing platforms Capital Ecommerce & Acumen, InCred Wealth, 175 listing platforms J&A Capital Partners I nclud es management services Others 30 Peak XV Partners, Prosus Ventures, Ecommerce & 107.2 Steadview Capital, Think Investments, listing platforms Pratithi Investments Note(s): Late - stage investments include Series F onwards rounds © 1Lattice | 21 Source(s): 1Lattice Deals Database Top late - stage investments Top funded late - stage startups with their competitors Company Description Competitors Zepto is an online grocery delivery service Provides budget - friendly accommodation options in various locations around the world Revolutionizing the fine jewelry and lifestyle segment © 1Lattice | 22 Source(s): 1Lattice Deals Database Tech investments In Q3 CY24, SaaS/AI and Ecommerce & listing platforms attracted the highest tech investments (~US$ 1.1B each), followed by Healthcare & Life Sciences (~US$ 375M) Tech investments by sector Top 10 tech investments in Q2 CY24 (US$ M, Q3 CY24) Amount Company Sector Key Investors (US$ M) SaaS/AI 1,149 General Catalyst Partners, Dragon Capital, Epiq Ecommerce & 340 Capital, StepStone Group, Lightspeed Venture listing platforms Ecommerce & listing Partners, DST Global, Contrary Capital 1,059 platforms Consumer app & Hornbill Capital, WestBridge Capital, Lightspeed 210 platforms Venture Partners, GSV Ventures Consumer app & 375 platforms Ecommerce & WestBridge Capital, Nexus Venture Partners, 200 listing platforms Think Investments, Invus Financial Advisors Healthcare & Life 65 Sciences Ecommerce & 175 Acumen, InCred Wealth, J&A Capital Partners listing platforms Telecom 34 SaaS/AI 125* Warburg Pincus, SoftBank Group Think India Opportunities Fund, Discovery Global SaaS/AI 108 Opportunity Fund, Aamara Capital, Ratnabali Energy 24 Investments Ecommerce & Peak XV Partners, Prosus Ventures, Steadview 107 BFSI 11 listing platforms Capital, Think Investments, Pratithi Investments SaaS/AI 102 Flourish Ventures, Helios Investment Partners Manufacturing 1 Includes SaaS/AI 100 Mars Growth Capital SpaceTech & education Others 9 SaaS/AI 100* Warburg Pincus, SoftBank Group Note(s): * Whatfix has secured funding in two tranches - 500 © 1Lattice | 23 Source(s): 1Lattice Deals Database Agenda Deal landscape in Q3 CY24 Key deals and investment themes Key investors Active investors Most active investors of Q3 CY24 Growth - stage investors Early - stage investors (# deals) (# deals) 4 3 4 3 4 3 4 Note(s): There are 11 late - stage investors with 1 investment each © 1Lattice | 25 Source(s): 1Lattice Deals Database Active early - stage investors Most active early - stage investors and their investment segments in Q3 CY24 Ecommerce & Healthcare & Life Investors SaaS/AI Energy Others** listing Sciences * - - - - - - - - - - Note(s): *Accel has made 2 Investments in Nurix ; **Others include sectors such as Telecom, Retail, Consumer app & platforms, BFSI, etc. Source(s): 1Lattice Deals Database © 1Lattice | 26 Active growth - stage investors Most active growth - stage investors and their investment segments in Q3 CY24 Ecommerce & Consumer app & Investors SaaS/AI Telecom Energy Others* listing platforms - - - - - - - - - - Note(s): *Others include sectors such as Retail, FMCG, Healthcare & Lifesciences, Transportation & logistics, etc. © 1Lattice | 27 Source(s): 1Lattice Deals Database 4 200+ Technology - backed business Offices in India Annual engagements support that helps you ENABLE BETTER 130+ 50+ Team members Inhouse research team DECISIONS 1,000+ 2M+ On - ground staff B2C Panel Deep on - ground insights that you can act on 4 offices, deep experience across geographies – 500K+ 300K+ India, the USA, Europe, MEA, and SEA regions B2B Panel Experts & professionals One - ness of data and people networks to harness the collective power of data, network, and technology 20% 100% Multi - faceted teams offering a stack of consulting, Cost savings Controlled output & timeline advisory, and research services At 1Lattice, we address the problem statement and serve as the one - stop platform for all your knowledge and decision support requirements (1/2) Intelligence Input Validate Execute Measure & Insights • Market assessment, TAM, SAM • PMF test / feasibility studies • Time motion studies • SOP / process audits • GTM planning • B - plan validation • Brand health track studies • M&A landscape scan • Competitive landscape & scan • B2C Qualitative research • Segmentation and personas • Campaign evaluation • Tracking panels • Customer retention and loyalty • NPS studies • B2C Quantitative research • Customer journey mapping analyses • UI / UX testing • B2B Qualitative research • Account potential assessment • Customer retention analysis • NPS health check • B2B Quantitative research • Contract benchmarking • Sales force productivity • Customer segment GTM • Retail store audits • Retail Measurement Survey • Competitive intelligence • Benchmarking • Mystery shopping • Sentiment analysis • Channel tracks • Listed companies scan • Brand tracks • Micro market assessment • Concept Validation • Go to market Approach • MM competitive intelligence • MM planning • Impact metrics • Funding GTM strategy • Program management • Impact tracking • Founder / leadership assessment • Reputation diligence • Geo analysis • Leadership assessment • Founder integrity DD • Employee NPS • IPO program management • Industry and company data • Report key messages • IPO / QIP reports • Claims data • Claim validation • Gap analysis • Certification / Attribution • ESG standards / metrics • Stakeholder feedback • Gap analysis • ESG assessment • Risk audits and tracking © 1Lattice | 29 At 1Lattice, we address the problem statement and serve as the one - stop platform for all your knowledge and decision support requirements (2/2) Input Validate Execute Measure Networks • Expert interactions • Due diligence • Short - term projects • Expert access • Expert transcript library • Fitment and turnaround • Enterprise surveys time • Vendor/target search • 1Lattice panel powered by AI • Cohort matching • Short - term projects • NPS health check • Cohort based outreach • Pre search QC • Data scraping • Sales force productivity • B2B / B2C respondent search and • Detailed QC • Retail store audits DIY engagement • Retail Survey (RMS) • Capability assessment • Globally valid certification • Compliance training academy • Compliance certification • Skill matrix benchmarking • Ongoing engagement • Sales & soft skills academy • L&D feedback • Functional skills academy • Custom trainings • Coaches and mentoring network • Role transition support • Experts for mid term projects • Engineering/Technical Due • Marketing / creative hub • Compliance • Fractional CXOs Diligence • Sales hub management • Analyst hub • Analysts on demand • Leadership hiring • Reference checks • Outplacement Support • Talent access • Mid - Level hiring • Board placement • Fitment • Internships and turnaround time • Roadshows • Cohort matching • Curated events • Cohort fitment • Fundraising campaigns • RSVP Management - Channel • Business generated appointments (distributors, franchisee, M&A targets, CXOs) • Associated reports' launch © 1Lattice | 30 We are here for you Let us know how we can meet your business requirement? Praneet Singhal Abhilasha Jaju Devmalya Mukherjee Director, Financial Investors and Banking, Director , Financial Investors & 1Alpha Director, Financial Investors Financial S ervices, & Insurance E: praneet.singhal@1lattice.com E:devmalya.mukherjee@1lattice.com E: abhilasha .jaju@1lattice.com Vansh Athwani For media queries, please contact Associate Manager, Financial Investors E: vansh.athwani@1lattice.com Vaishnav Kumar Rai Manager – Corporate Communications E: communications@1lattice.com M: +91 782 794 4925 www.1lattice.com Disclaimer: This material has been prepared by 1Lattice, which is the trade name of Lattice Technologies Private Limited (“1L att ice”, “we” or “our”) with the intent to showcase our capability and disseminate learnings to potential partners/clients. This material can be referred to by the readers on the internet but should be referenced to 1Lattice, if reused or adapted in any for m, or medium and on any forum. The frameworks, approaches, tools, analysis and opinions are solely 1Lattice’s intellectual property and are a combination of the collection of the best data we could find publicly, and the 1Lattice team’s own experie nce s and observations. Any information provided herein is only for informational purposes and you are advised to perform an independent analysis of the same before making any decision based on such information. The information does not constitute an y b usiness advice or guidance and is to be construed as a general summary based upon the publicly available information and our interpretation of the same using our resources. For this material, we may have relied upon different sour ces of information which may be primary sources, publicly available information, and relevant information available with us. We make no representation or warranty, expressed or implied, that such information is accurate or complete, and nothing conta ine d here can be construed as definitive predictions or forecasts. Before reading further, the Recipient expressly agrees that this might not address any and all risks and challenges facing the Recipient, its business, and the markets within which it operates, nor all possible market conditions. Any use of the information provided herein by the viewer shall be at the sole r is k of the viewer and 1Lattice or its business partners, affiliates, agents, officers or employees shall not be liable for any un int ended or adverse effect or outcome from the use of such information by the reader. 1Lattice does not have any duty to update or supplement any information in this document. 1Lattice shall not be responsible f or any business or commercial loss sustained by any person who relies on any information provided herein. Any and all logos of companies used in the information provided herein have been published for information purposes only and 1La ttice does not hold any liability in connection therewith. +91 976 925 3702 abhilasha.jaju@1lattice.com Delhi NCR | Mumbai | Bengaluru | UAE | KSA | Singapore