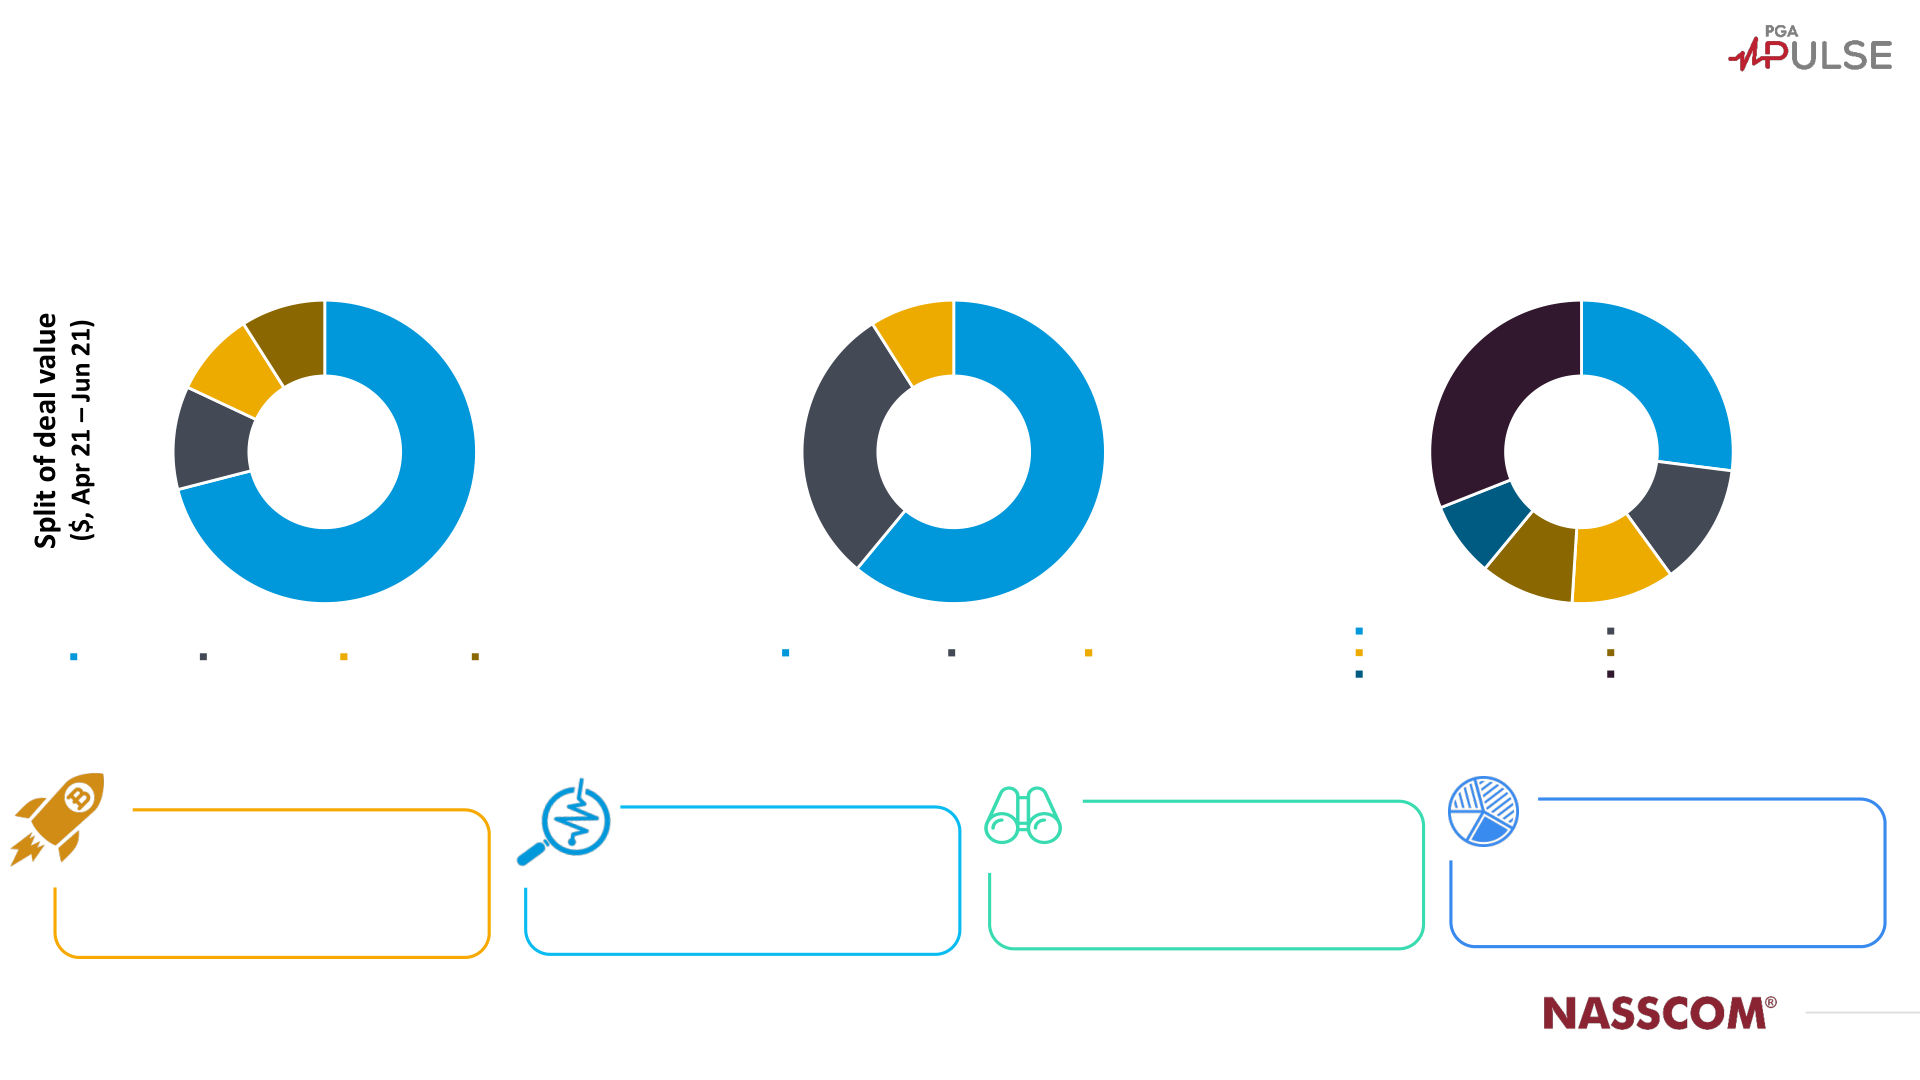
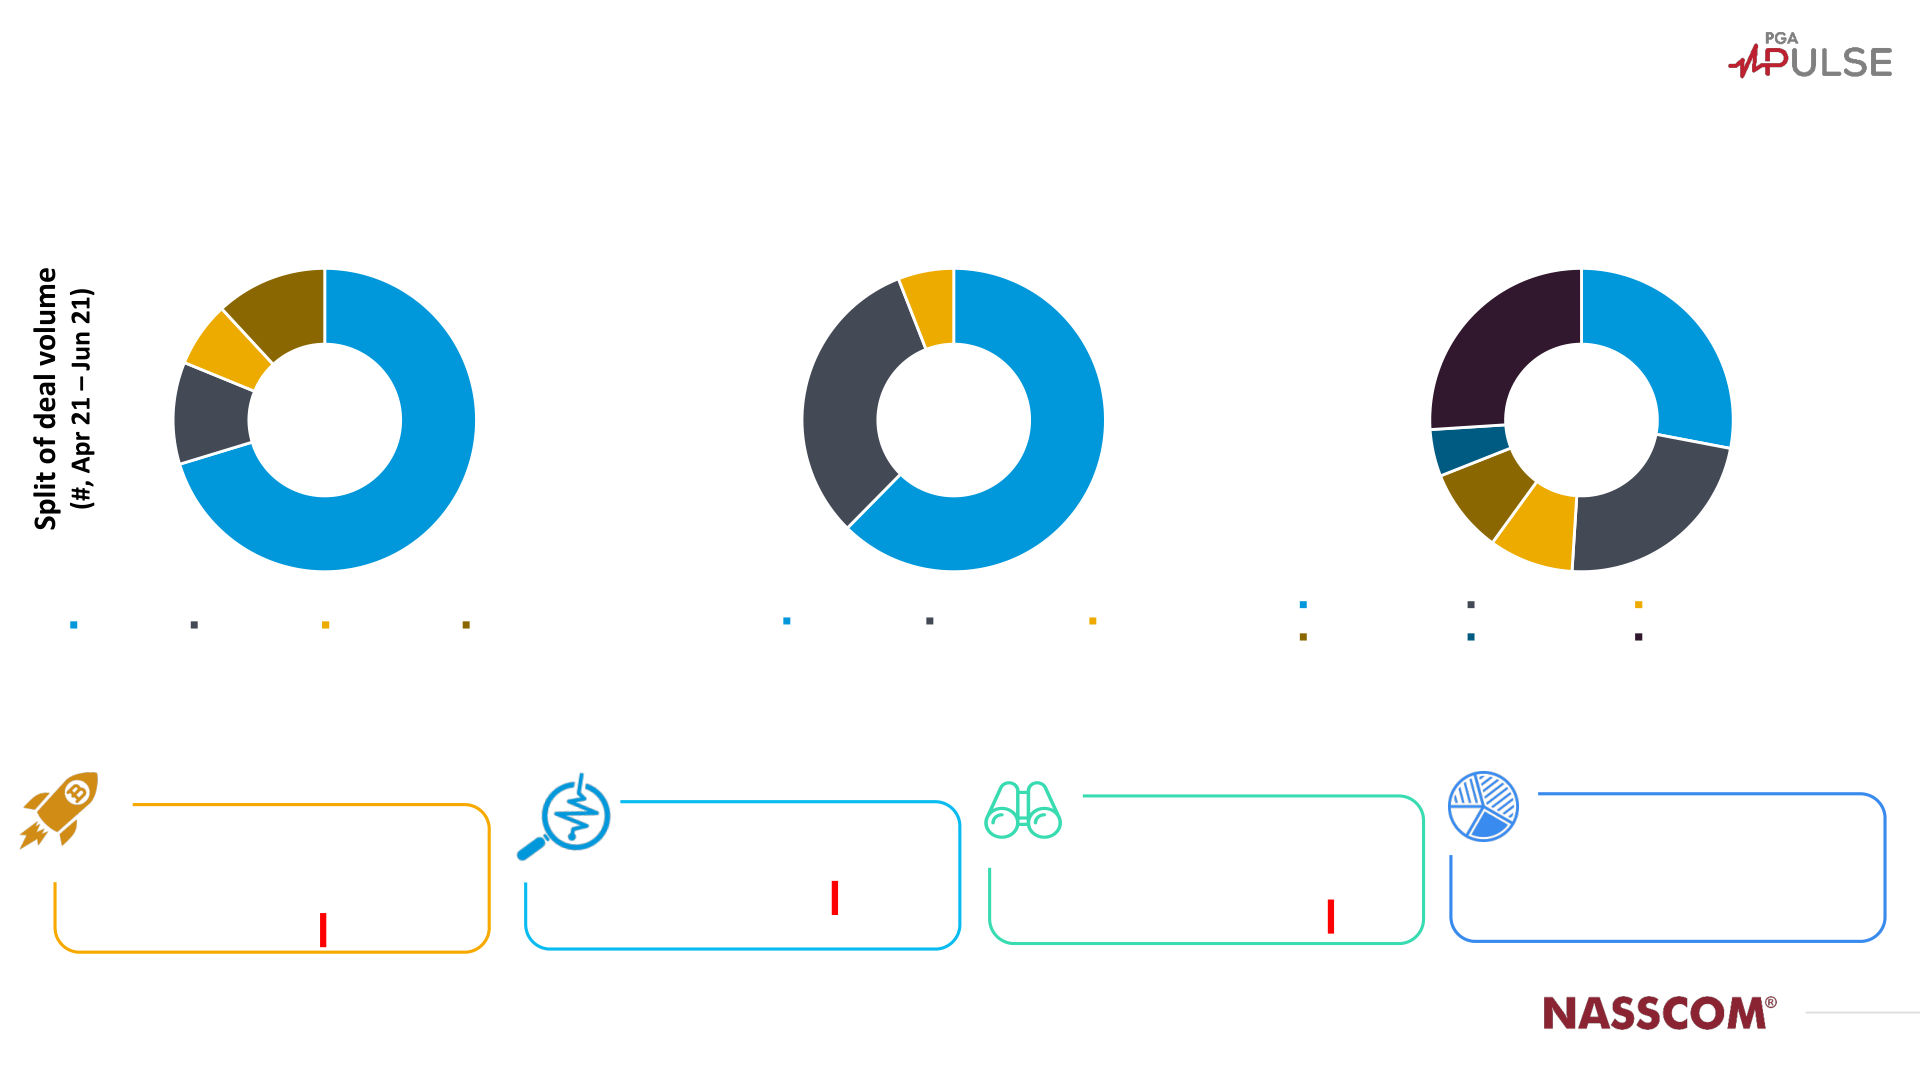
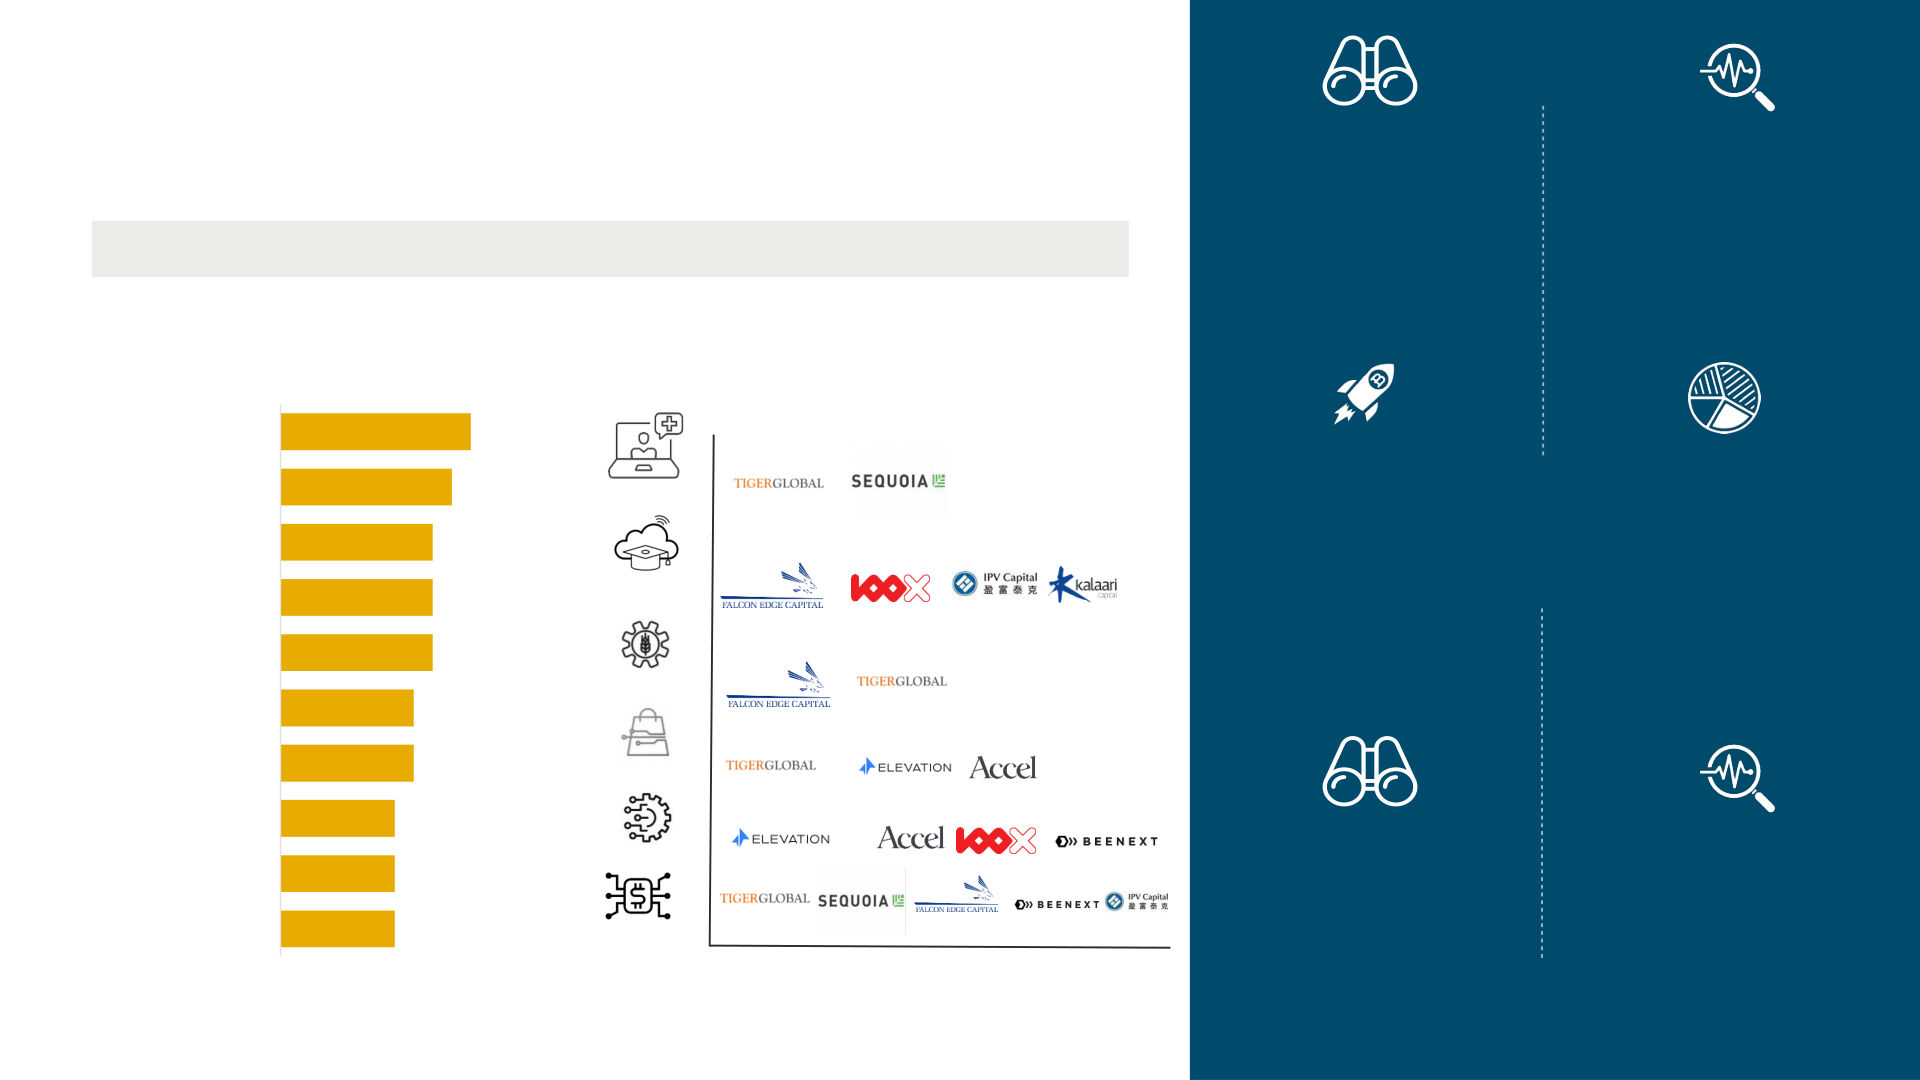
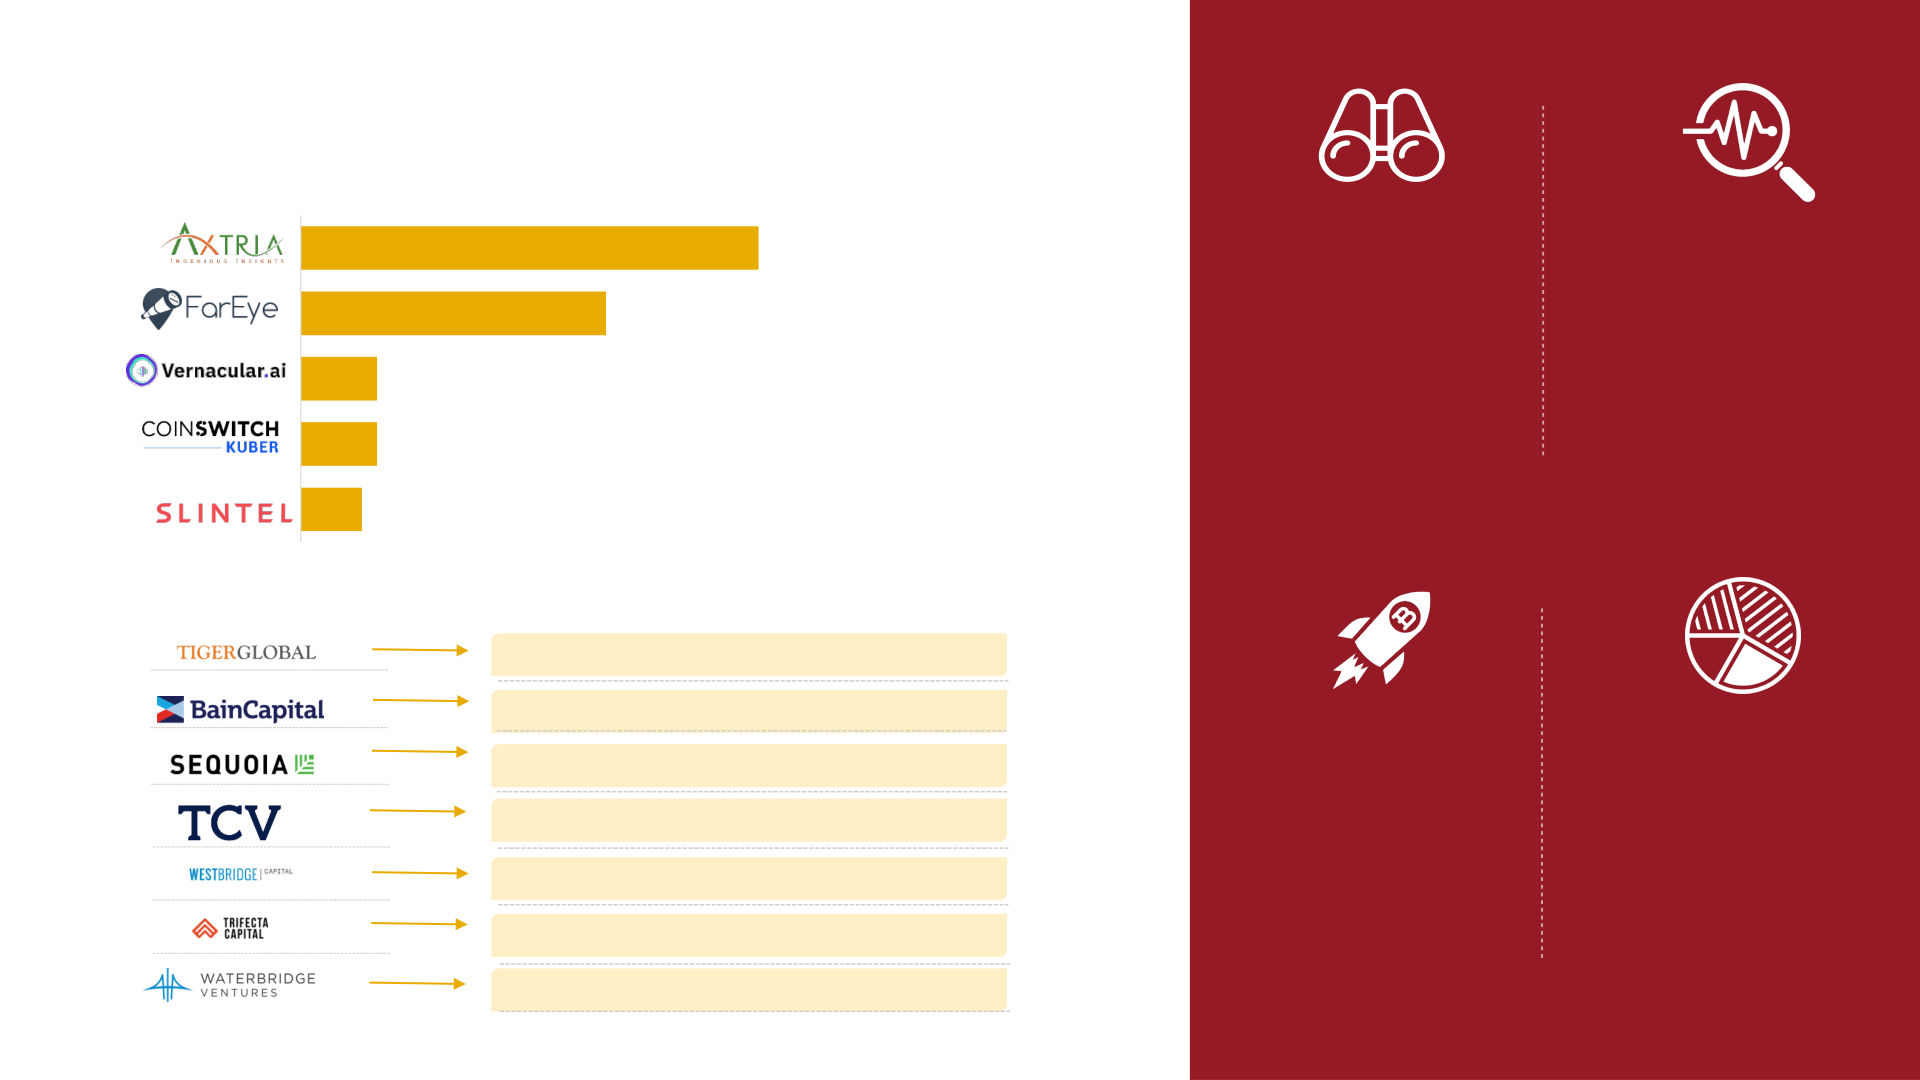
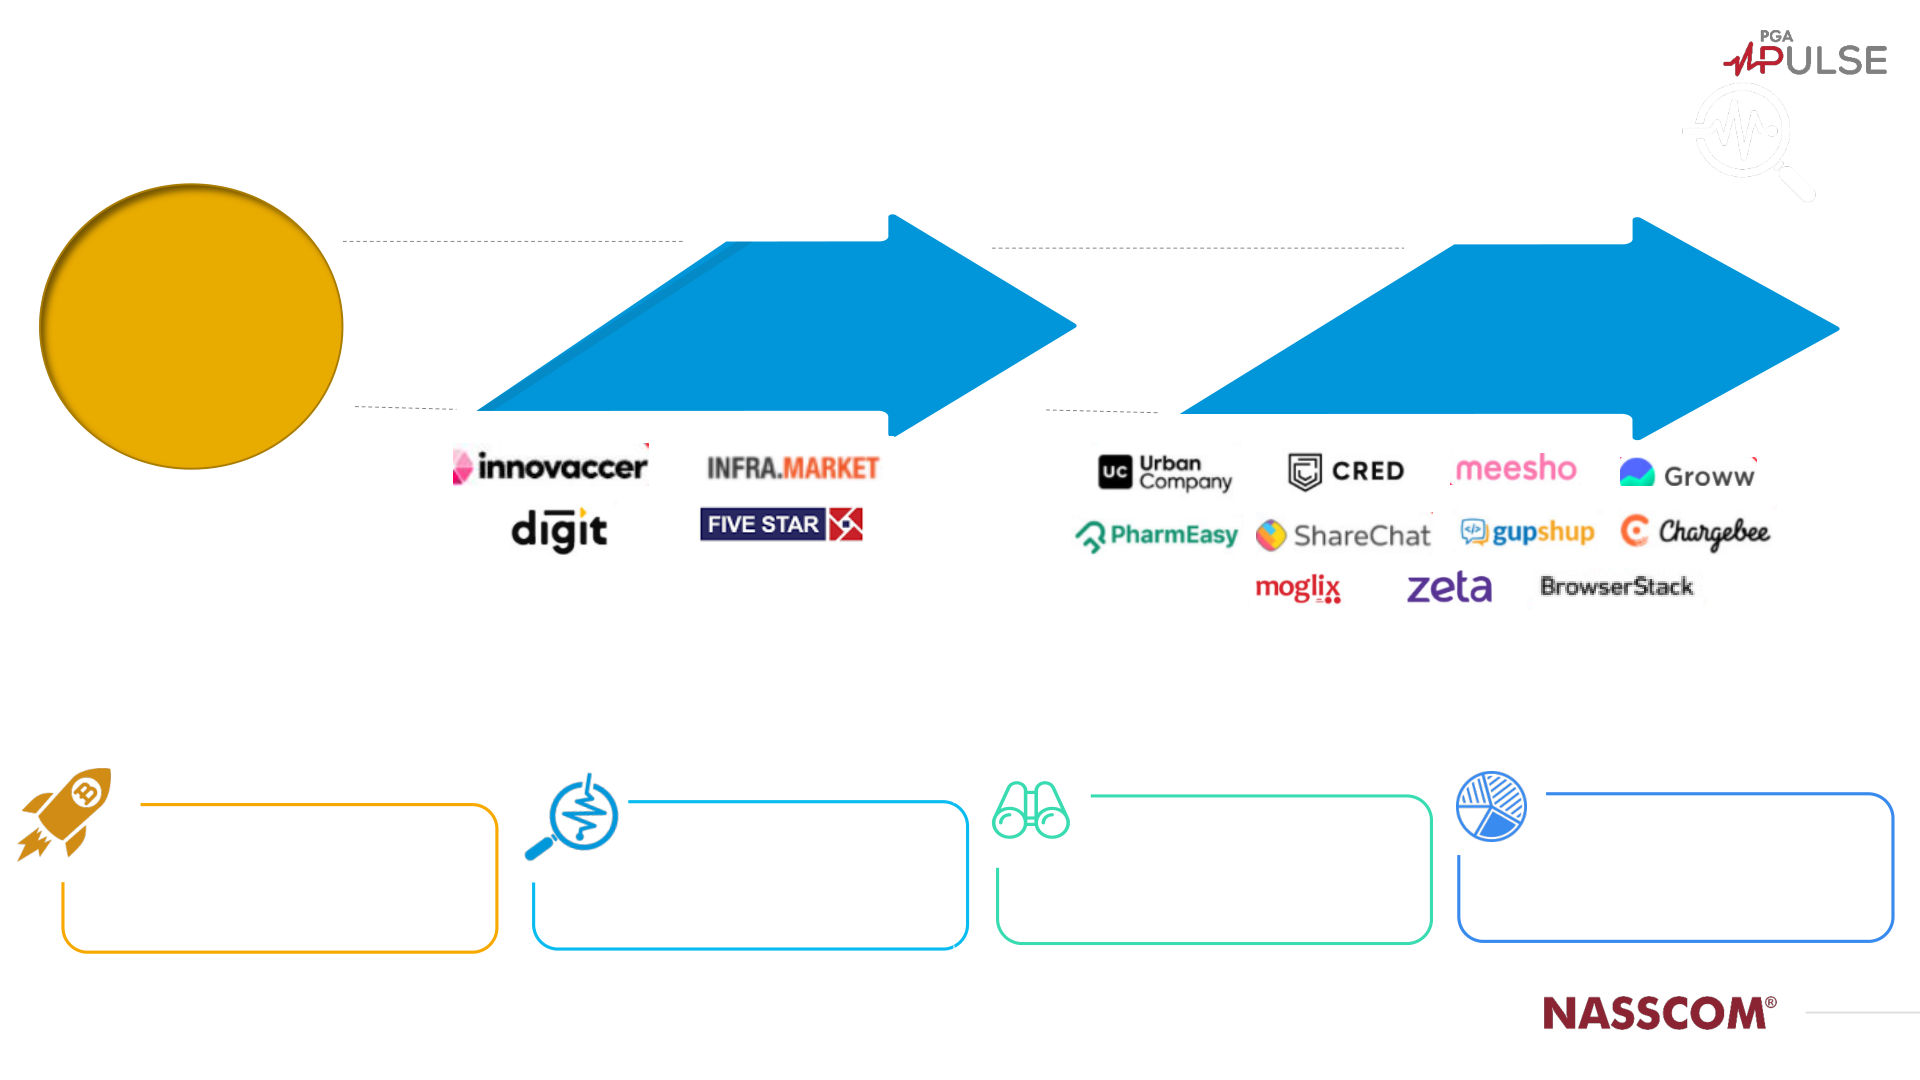
Quarterly Tech Start - up Factbook Q2 - 2021 Start - up Trend Analysis August 2021 Summary: Q2 2021 (Apr – Jun 2021) Q2 2021 has been impeccable for the start - up growth story. From being the most funded quarter, it has also added the most number of unicorns. Standing tall during the pandemic second wave headwinds, Indian start - up ecosystem has shown a strong resilience in this quarter. Funding # Deal Volume Unicorns Top Funded Sector Most Funded Stage US$ 6.5B 160 FinTech 11 Growth 27% of the Total Deal Value 61% of Total Deal Value Total Unicorns(till June 21): 53 Up by 71% Q - o - Q Up by 2% Q - o - Q 2 Deal value by latest quarter >50% of funding was concentrated on 3 sectors - FinTech, FoodTech and Enterprise Tech Funding by Deal Size Funding by Stage Funding by Sector 9% 9% 9% 27% 31% 11% 30% US$ 6.5B US$ 6.5B US$ 6.5B 61% 13% 8% 71% 11% 10% FinTech FoodTech Growth Late Early Enterprise Tech EdTech > US$ 100M US$ 50-100M US$ 25-50M < US$ 25M Media & Entertainment Others Large ticket deals helped Increased focus towards growth Rise by 80% in large deals (>US$ >71% jump in Q2 2021 deal FinTech and FoodTech to 100M) over previous quarter stage, accounting for more than value compared to Q1 2021 account for 40% of deal value 60% of deal value Notes(s): Others includes SCM, Retail Tech, HealthTech, Marketing, Automotive, HR Tech, Hospitality, Manufacturing, AgriTech, Ae rospace, Energy, Mobility, Legal Tech, Gaming 3 Source: PGA Labs Deals Database Deal volume by latest quarter 71% of deal volumes account for <US $ 25M; 28% deals in Enterprise Tech Deal Volumes by Stage Deal Volumes by Sector Deal Volumes by Size 6% 12% 26% 7% 28% 32% 11% 160 160 160 5% 63% 71% 9% 23% 9% Enterprise Tech FinTech EdTech Early Growth Late < US$ 25M US$ 25-50M US$ 50-100M > US$ 100M HealthTech SCM & Logistics Other Lower ticket size deals dominate; 63% bets on early - stage 60% deals in 3 specific th 70% rise in large ticket size (>US$ >1/4 of deals focused on innovative start - ups - though verticals - Enterprise Tech, 100M) deals compared to previous Enterprise Tech deal size remains small FinTech and Ed Tech quarter Notes(s): Others includes Food Tech, Retail Tech, Marketing, Automotive, HR Tech, Hospitality, Manufacturing, AgriTech, Aeros pac e, Energy, Mobility, Legal Tech, Gaming 4 Source: PGA Labs Deals Database Funding by sales channel and funding rounds Growth stage funding for B2C tech start - ups drives deal flows B2B start - ups raised over Top 3 B2B funded B2C start - ups led the race in deal Series D and E together account US$ 1.9B across 85 deals, start - ups are Zeta, value for 45% of deal value with an average deal size Razorpay and Axtria of ~US$ 22M Deal flow split Split by series (%, Apr 21 – Jun 21) (%, Apr 21 – Jun 21) Series J 12% Series H 5% B2C start - ups raised Series G 2% Top 3 B2C funded over US$ 4.2B across B2B, start - ups are Swiggy, 29% 75 deals, with an Series F 11% ShareChat and BYJU’s average deal size of Series E 19% ~US$ 56M US$ 6.5B Series D 26% Series C B2C , 11% 71% Series B 6% 100 start - ups received 61% of the funding (51 Series A 6% funding in the early deals) went to growth stage, accounting for 9% stage start - ups Seed 1% of total funding raised Source: PGA Labs Deals Database Top investors and their focus sector Diversified investor interest across sectors Elevation Capital and Tiger Global have FinTech accounted for 12% Illustrative invested in 3 sectors - of deal volume among top Most prominent investor in terms of deal volume FinTech, Enterprise investors Tech and Retail Tech Top Investors, Split of deal flow Investor diversification (#, Apr 21 – Jun 21) Elevation Capital 10 Enterprise Tech Retail Tech accounted for 100x 9 HealthTech accounted for 13% 20% of deal volume among Sequoia Capital 8 of deal volume top investors among top investors EdTech Beenext 8 Tiger Global 8 FoodTech Accel India 7 IPV 7 Retail Tech Blume Ventures 6 Enterprise Tech Prominent investors 5 among top 10 Kalaari Capital 6 Elevation Capital, investors funded start - Falcon Edge Capital 6 FinTech Sequoia Capital and ups in the FinTech Tiger Global have space done 8+ deals Source: PGA Labs Deals Database DeepTech deal flow Growing investor interest towards DeepTech start - ups Top DeepTech start - ups by funding Illustrative (US$ M, Apr 21 – Jun 21) AI - based life sciences software 150 19% of deal volume DeepTech start - ups catering to start - ups raised ~US$ 450M 100 AI - based delivery management leveraging DeepTech across 29 deals 25 AI based voice automation solutions, representing ~7% of 25 Blockchain based crypto platform Q2 2021 funding in value 20 SaaS based sales intelligence tool Top DeepTech Investors Illustrative CoinSwitch, Innovacer Axtria Sequoia Capital and 22 deals across early CoinSwitch, LambdaTest WestBridge are the stage in DeepTech FarEye top 2 investor start - ups investing in AI/ML Vernacular.ai technologies PlayShifu Atlan Note(s): DeepTech includes AI/ML, AR/VR, IoT, Blockchain, Robotics, 3D Printing, Big Data & Analytics Source(s): Secondary research, PGA Labs deal database, PGA Labs analysis Unicorns E xponential rise in unicorn base in the Indian tech start - up ecosystem in Q2 2021 Illustrative 53 15 11 Unicorns added in Unicorns added in Total Unicorns in H1 2021 (Jan - Jun) Q2 2021 (Apr - Jun) India as of June 2021 27% of unicorns added in Q2 6 unicorns have filed for IPO 2021 belong to FinTech while CRED turned unicorn in just 29 Tiger Global invested in 64% of this year, out of which Zomato 18% each belong to SaaS & months of its inception the unicorns during Q2 2021 got listed in July 2021 Social commerce 8 Source: PGA Labs Deals Database Appendix Top deals Sector wise top deals Tech start - ups filing DRHPs with SEBI Methodology Definitions: Stages / Sectors Stakeholder Initiatives 9 Appendix - Top Deals Top deals of Q2 2021 Illustrative Funding Funding # Company Founded Sector Sub - sector Investors (US$ M) stage Falcon Edge Capital, Goldman Sachs, 1 2014 FoodTech Food delivery 800 Late Think Capital, Amansa Capital and Carmignac 2 2015 Media & Entertainment 502 Tiger Global Management Social networking Growth 3 2011 EdTech K12 learning 340 Late UBS, Blackstone, ADQ 4 2015 HealthTech Marketplace 323 Growth Prosus Ventures, TPG Growth SoftBank Vision Fund, Prosus Ventures, 5 2015 Retail Tech 300 Growth Mcommerce Shunwei Capital, Venture Highway Payment 6 1998 FinTech 285 Growth Baron Capital Group processing 7 2011 SCM & Logistics Logistics services 277 Late Fidelity Investments 8 2015 FinTech 250 Growth SoftBank Vision Fund Payments 9 2018 FinTech 215 Growth Falcon Edge Capital, Coatue Management Credit card rewards Prosus Ventures, Tiger Global 10 2014 Retail Tech Marketplace 188 Late Management, DF International Partners Total of top deals 3,480 Source(s): PGA Labs deal database, PGA Labs analysis 10 Appendix Sector wise top deals in Q2 2021 Illustrative FinTech Enterprise Tech Sub - Funding Funding Funding Funding Company Investors Company Sub - sector Investors (US$ M) stage sector (US$ M) stage Payment 150 Growth Bain Capital Pine Labs 285 Growth Baron Capital Group Axtria Data analytics processing Social Tiger Global Management, Fidelity Zeta 250 Softbank Vision Fund Payments Growth 100 Late Gupshup networking Management, Think Investments Credit card Falcon Edge Capital, Coatue Programming CRED 215 90 Growth Eight Roads Ventures Growth Whatfix Management LLP rewards tools Retail Tech SCM & Logistics Funding Funding Funding Funding Company Sub - sector Investors Company Sub - sector Investors (US$ M) stage (US$ M) stage Logistics SoftBank Vision Fund, Prosus Delhivery 277 Late Fidelity Investments Meesho 300 services Mcommerce Growth Ventures, Venture Highway Logistics Dragoneer Investment Group, FarEye 100 Growth Urban Prosus Ventures, Tiger Global TCV management 188 Marketplace Late Company Management Avataar Ventures, Prosus Logistics ElasticRun 75 Growth FabAlley Marketplace 3.47 Growth Elevation Capital services Ventures, Kalaari Capital FoodTech Media & Entertainment Sub - Funding Funding Sub - Funding Funding Company Investors Company Investors sector (US$ M) stage sector (US$ M) stage Falcon Edge Capital, Goldman Sachs, Food Social Swiggy 800 Late 502 Growth Tiger Global Management ShareChat delivery Think Capital, Amansa Capital networking Meat Meeting Licious 65 Brunei Investment, Vertex Ventures Late Fireflies 14 Early Khosla Ventures ordering assistant Source(s): PGA Labs deal database, PGA Labs analysis 11 Appendix - DRHPs Tech start - ups filing DRHPs with SEBI Illustrative # Company Founded Sector Sub - sector Date DRHP 1 2012 Retail Tech Ecommerce platform 3/8/2021 2 2008 FinTech Insurance marketplace 2/08/2021 3 2009 FinTech Payments 16/7/2021 4 2009 FinTech Payments 13/7/2021 5 2009 Automotive Auto classifieds 17/5/2021 6 2008 FoodTech Food delivery 28/4/2021 Source(s): Secondary research, Praxis analysis 12 Appendix - Stakeholder initiatives Positive outlook for start - up ecosystem is evident from different stakeholder initiatives Illustrative Software Technology Parks of India (STPI) • STPI an autonomous body under MeiTY setting up incubation center for start - up in domains like Healthcare, IoT, ICT and ecommerce • Budget is ~ US$ 3M NASSCOM Industry Partnership Program (NIPP) Initiatives Start - up India Seed Fund • NIPP Retailtech Challenge 2021 closed with 222+ applications, across 34 use - cases and • Project worth ~ US$ 134M to help start - ups brought together an audience of 225+ and support ideas from aspiring delegates entrepreneurs • 10,000 start - ups completed 3 Investor Demo • To ensure that there is no capital shortage Days and presented 16 start - ups, every demo for start - ups day joined by 25+ investors • Financial assistance up to ~US$ 70K for start - ups at early stage through incubators • The program will provide incubators with funds to support start - ups • 3,600 entrepreneurs through 300 incubators will benefit from this scheme in next 4 years Source(s): Secondary research, Praxis analysis 13 Scope Inclusions Exclusions What's included in the report? What’s excluded from the report? • Non - tech start - ups operating in the consumer • Only tech start - ups have been considered for this space have not been included in this report report which are working towards innovation in technology, business process or business model • Investments from angel investors, incubators and start - up accelerators have been excluded • Start - ups which have received funding from private equities or venture capital firms have • Debt investments and strategic deals into tech been considered start - ups have not been considered searching... • Founders of Indian origin, with HQ or core • Start - ups at the idea stage without a prototype product development in India or minimum viable product have also not been considered • Start - up to have a prototype or MVP; idea stage start - ups are not considered 14 Methodology This pulse report has been co - developed by NASSCOM and PGA Labs through a comprehensive study to understand the tech start - up la ndscape in India This report analyses the following – ● Current investment scenario and trends that define the Indian tech start - up ecosystem ● Ecosystem enablers like Incubators/Accelerators as well as government policies ● Recent DRHPs filed with the regulators Primary input for this report includes the following sources Extensive research of media PGA Labs proprietary deal Government websites Sector analyst reports articles database • Inc42 • Ministry of corporate affairs • Your story • SEBI • IVCA • Economic Times • Mint • Business Standard Appendix Definitions of stages and sectors (1/2) Stages of fundings have been mapped as: ● FinTech: Enables financial services, banking and insurance through technology ● Series A and prior rounds are early stage E.g., Online Banks, Financial Management Apps, Payment Management Platforms, ● Series B,C,D and E are growth stage Alternative Lending Platforms, Money Transfer Platform, Expense Management, Investment Platforms, Cryptocurrency & Trading Platforms, etc. ● Series F and above are late stage ● EdTech: Provides learning solutions & services through technology Sector definitions are given below: E.g., Learning Apps, Test Preparation Tech, Education Advisory Platform, K - 12/Higher education platforms, Language Learning Platforms etc. ● Enterprise Tech: B2B Product companies targeting Horizontal solutions for Large Enterprises / SMBs ● Travel & Hospitality: Tech companies engaged in supporting the E.g., Data Analytics/AI/ML Platforms, Development Platforms, Collaboration travel and hospitality industry tools Productivity Applications, Customer Services, Big Data/Cloud/Security E.g., Hotel Booking Services, Travel Planning, Travel Packages Portal, Travel Infrastructure, etc. Collaboration Community, etc. ● HealthTech: Provides technology platform for solving ● Mobility: Tech - enabled companies providing simplified HealthTech problems Transportation services to users E.g., Medical Solutions, Marketplace for Health Services, Health Lab E.g., Car - pooling, Self - Drive Rentals, Two - wheeler taxi aggregators, Mass Transit, Tech Aggregators, Online Pharmacies, E - Diagnostics, Ambulance Aggregator, etc. Enablers ● HRTech: Tech - enabled companies supporting Human ● Industrial & Manufacturing: Engaged in manufacturing of tech - Resources Activities enabled devices or machines; Construction/Mining sector, etc. E.g., Applicant Tracking systems, HR Management System, Candidate Assistance E.g., IoT based Predictive Maintenance of Machines, 3D Printing (Manufacturing) & Sourcing, Corporate Training/Learning and Development, Recruitment Marketplaces, etc.. ● Automotive: Companies involved in production, manufacturing, sales and services of motorized vehicles E.g., Electronic Engineering, System Integration, Automotive Maintenance, Electric Vehicles, Automotive marketplaces, etc. Appendix Definitions of stages and sectors (2/2) ● Media & Entertainment: Provides content for entertainment across ● SCM & Logistics: Enabling tech in logistics services and supply chain the web and mobile medium management E.g., News & Media Apps, Live Streaming Apps, News Platforms, OTT Content, Video E.g., Logistics and Distribution Platform, Fleet Management, Warehousing, IoT Platform Intelligence Apps, etc. for Logistics, IoT Platform for Goods Transportation Marketplace, etc. ● Retail Tech: Companies enabling Sales of goods and product online ● Gaming: Tech Innovation and facilitation in the Gaming industry E.g., AR/VR Gaming, Community platform Games, Fantasy Gaming Platforms etc. or Integration of tech in offline markets E.g., Products/Services cutting across several verticals - . Fashion & Lifestyle ● Legal Tech: Tech - based companies for Legal help to Marketplaces, Online grocery & Home essentials platforms. Also includes Retail enablers, B2B marketplaces, Social commerce platforms, Rental platforms etc. Individuals/Corporates E.g., Contract Management, Brand Protection and Anti Counterfeit, Legal Services ● AgriTech: Start - ups engaged in tech enablement in the Agricultural Discovery/Booking marketplaces, etc. industry ● Advertising & Marketing Tech: Provides direct advertising and E.g., Field Surveillance, Precision AgriTech, Farm infrastructure, Soil Testing, Farm Input E - Commerce etc. marketing assistance through technology E.g., Content marketing, influential marketing, Push notifications etc. ● Aerospace & Defense: Tech - based companies supporting the Defence and Aviation industry E.g., Military Drones, Green Propulsion Systems developers, Sensors and Platforms for security applications etc. ● Energy & Utilities: Tech Enablement for Natural Resource Management and Utilization E.g., Renewable Energy products, Recycling of Resources, Energy Production and Distribution, EV charging Infrastructure etc. ● FoodTech: Tech - enabled companies supporting the FoodTech industry E.g., Online Food Ordering, Restaurant Management Cloud Solutions, Food Discovery Platform 17 About About NASSCOM is the industry association for the IT - BPM sector in India A not - for - profit PGA Labs is a technology - enabled business research & intelligence services firm that organization funded by the industry, its objective is to build a growth led and specializes in driving decision from on - ground insights Our teams are multifaceted with a sustainable technology and business services sector in the country with over 3100 unique mixture of qualitative, quantitative and digital research experts . With a holistic members NASSCOM Research is the in - house research and analytics arm of approach focusing on the “What and Why”, we are able to extract relevant insights from data NASSCOM generating insights and driving thought leadership for today’s business employing advanced technology tools and innovative data gathering approaches leaders and entrepreneurs to strengthen India’s position as a hub for digital technologies and innovation Our clients use our capabilities to generate competitive / market insights for the sectors they operate in, sectors they want to expand to or the sectors of interest for their portfolio Usage of Information companies Forwarding/copy/using in publications without approval from NASSCOM Kno w more about us : www.pgalabs.in will be considered as infringement of intellectual property rights Credit and Acknowledgements: Achyuta Ghosh, Head – Research; Nirmala Balakrishnan, Deputy Director -- Research; Ashish Gupta, Manager -- Research For queries, please contact: Poonam Karkera Diksha Bhutani Associate Manager, Strategic Initiatives Associate, Corporate Communications p oonam.karkera @praxisga.com pr @praxisga.com M: +91 998 749 8982 M: +91 989 999 7679 Credit and Acknowledgements: Parul Singhh, Head – Corporate Communications; Shivaraj Jayakumar, Senior Consultant, Arjun Oberoi, Associate Consultant 18 Disclaimer Disclaimer The information contained herein has been obtained from sources believed to be reliable. NASSCOM and its advisors & service p rov iders disclaims all warranties as to the accuracy, completeness or adequacy of such information. NASSCOM and its advisors & service providers shall have no liability for errors , o missions or inadequacies in the information contained herein, or for interpretations thereof. The material or information is not intended to be relied upon as the sole basis for a ny decision which may affect any business. Before making any decision or taking any action that might affect anybody’s personal finances or business, they should consult a qualified prof ess ional adviser. Use or reference of companies/third parties in the report is merely for the purpose of exemplifying the trends in the industr y a nd that no bias is intended towards any company. This report does not purport to represent the views of the companies mentioned in the report. Reference herein to any specific com mer cial product, process or service by trade name, trademark, manufacturer, or otherwise, does not necessarily constitute or imply its endorsement, recommendation, or favouring by NASSCOM or any agency thereof or its contractors or subcontractors. The material in this publication is copyrighted. No part of this report can be reproduced either on paper or electronic media wi thout permission in writing from NASSCOM. Request for permission to reproduce any part of the report may be sent to NASSCOM. www.nasscom.in /NASSCOMOfficial research@nasscom.in Copyright © 2021 /nasscomR NASSCOM Plot 7 to 10, Sector 126, Noida - 201303 +91 - 120 - 4990111 /NasscomVideos