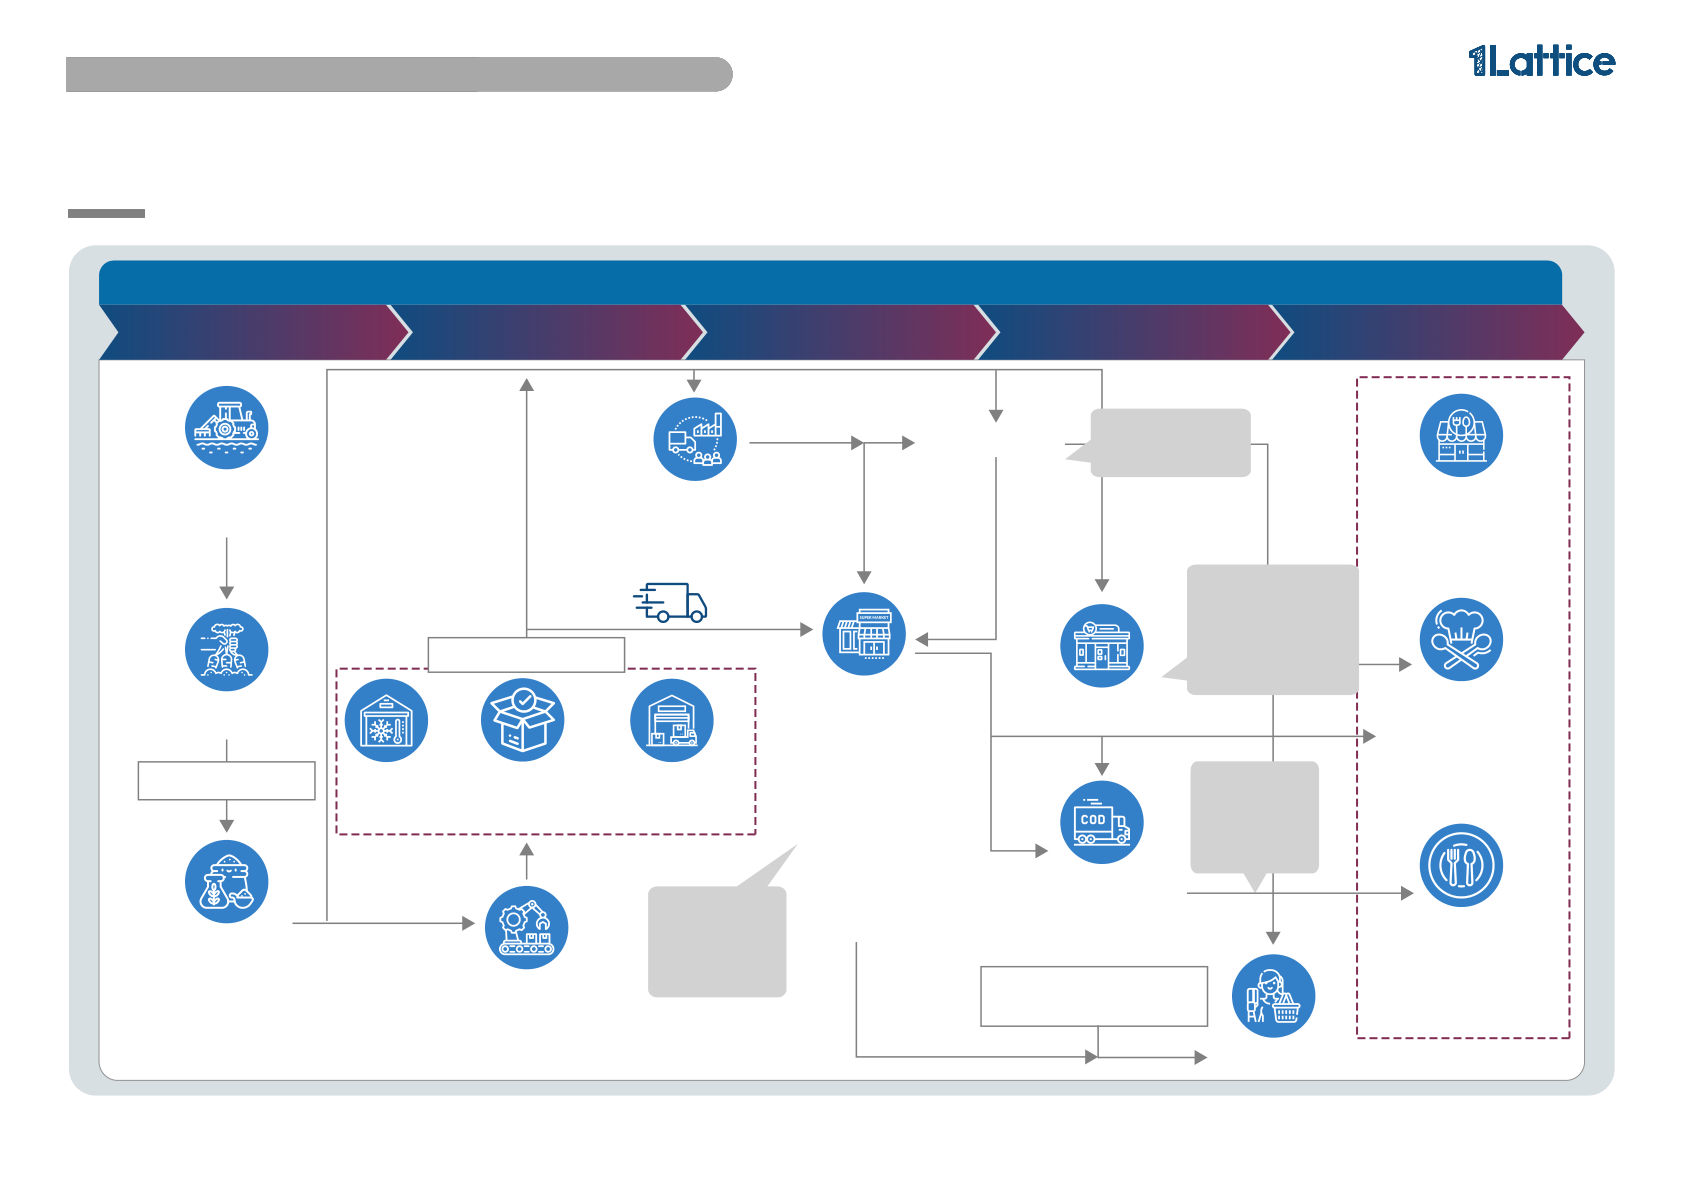
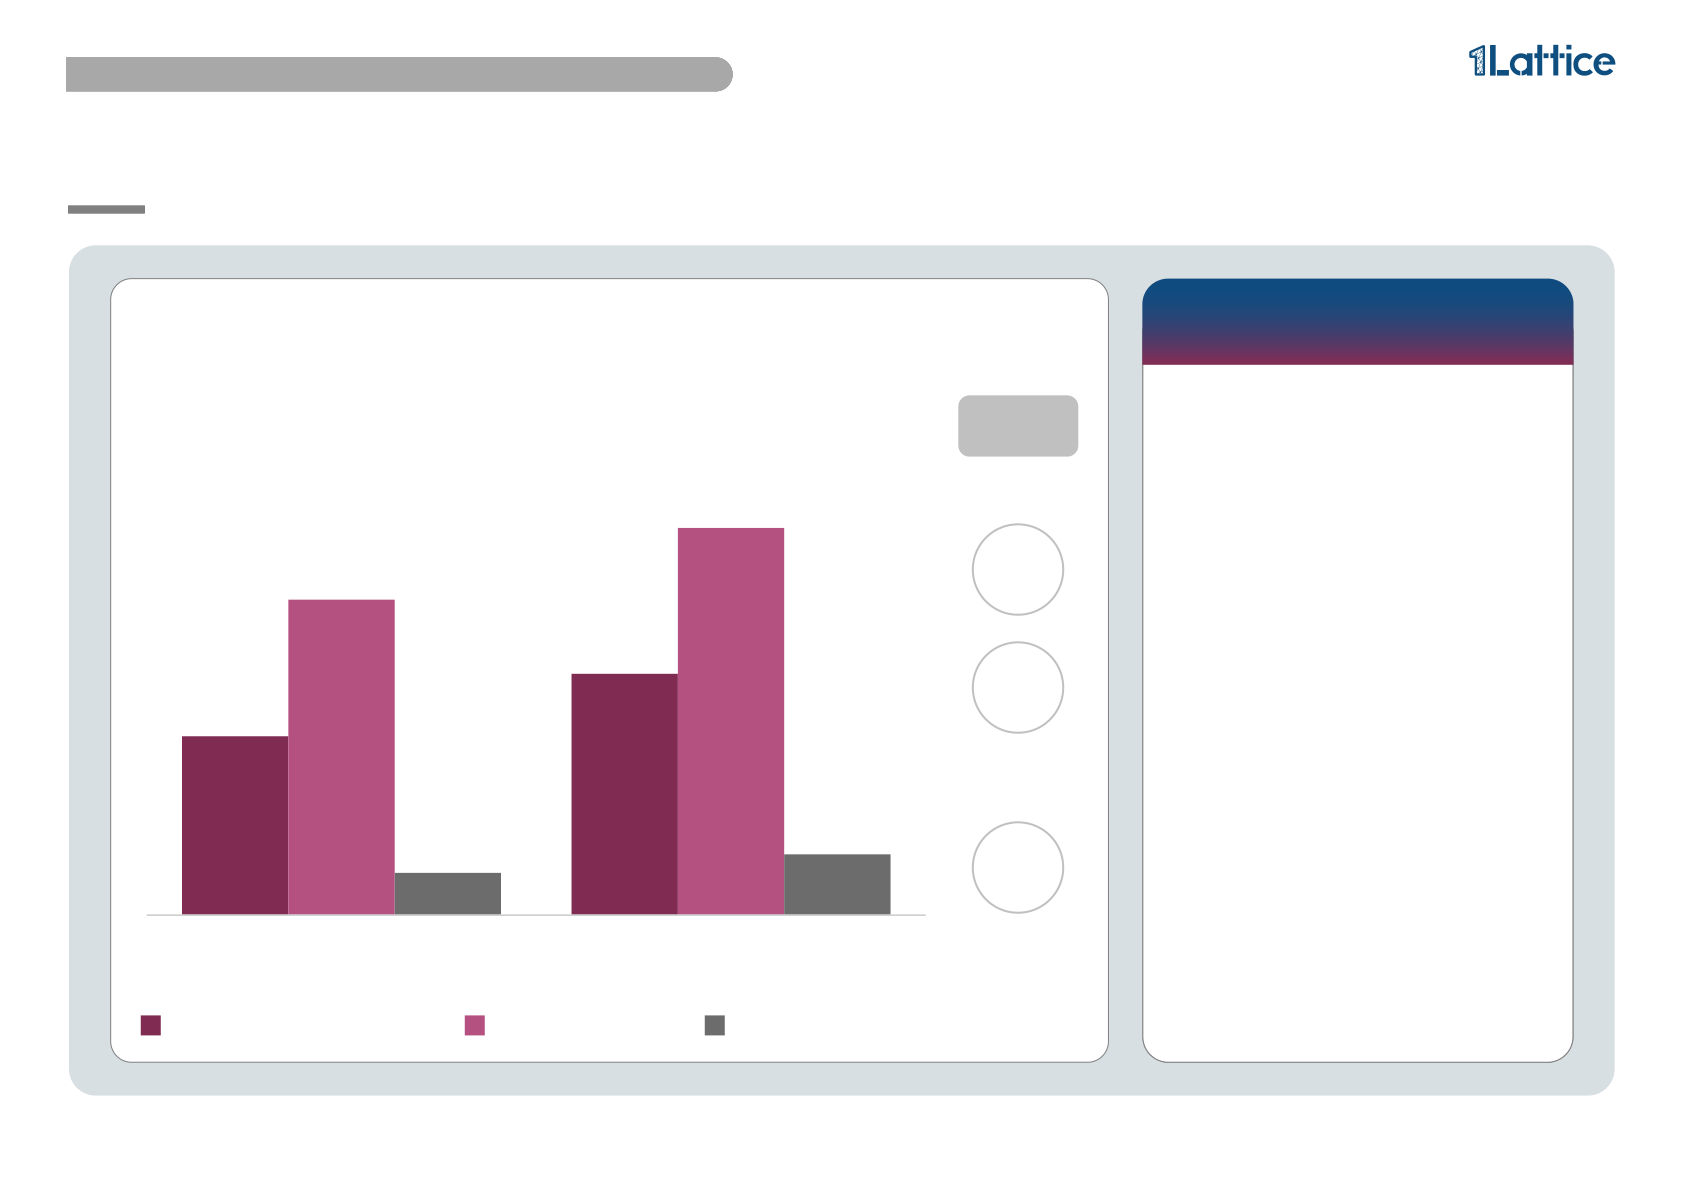
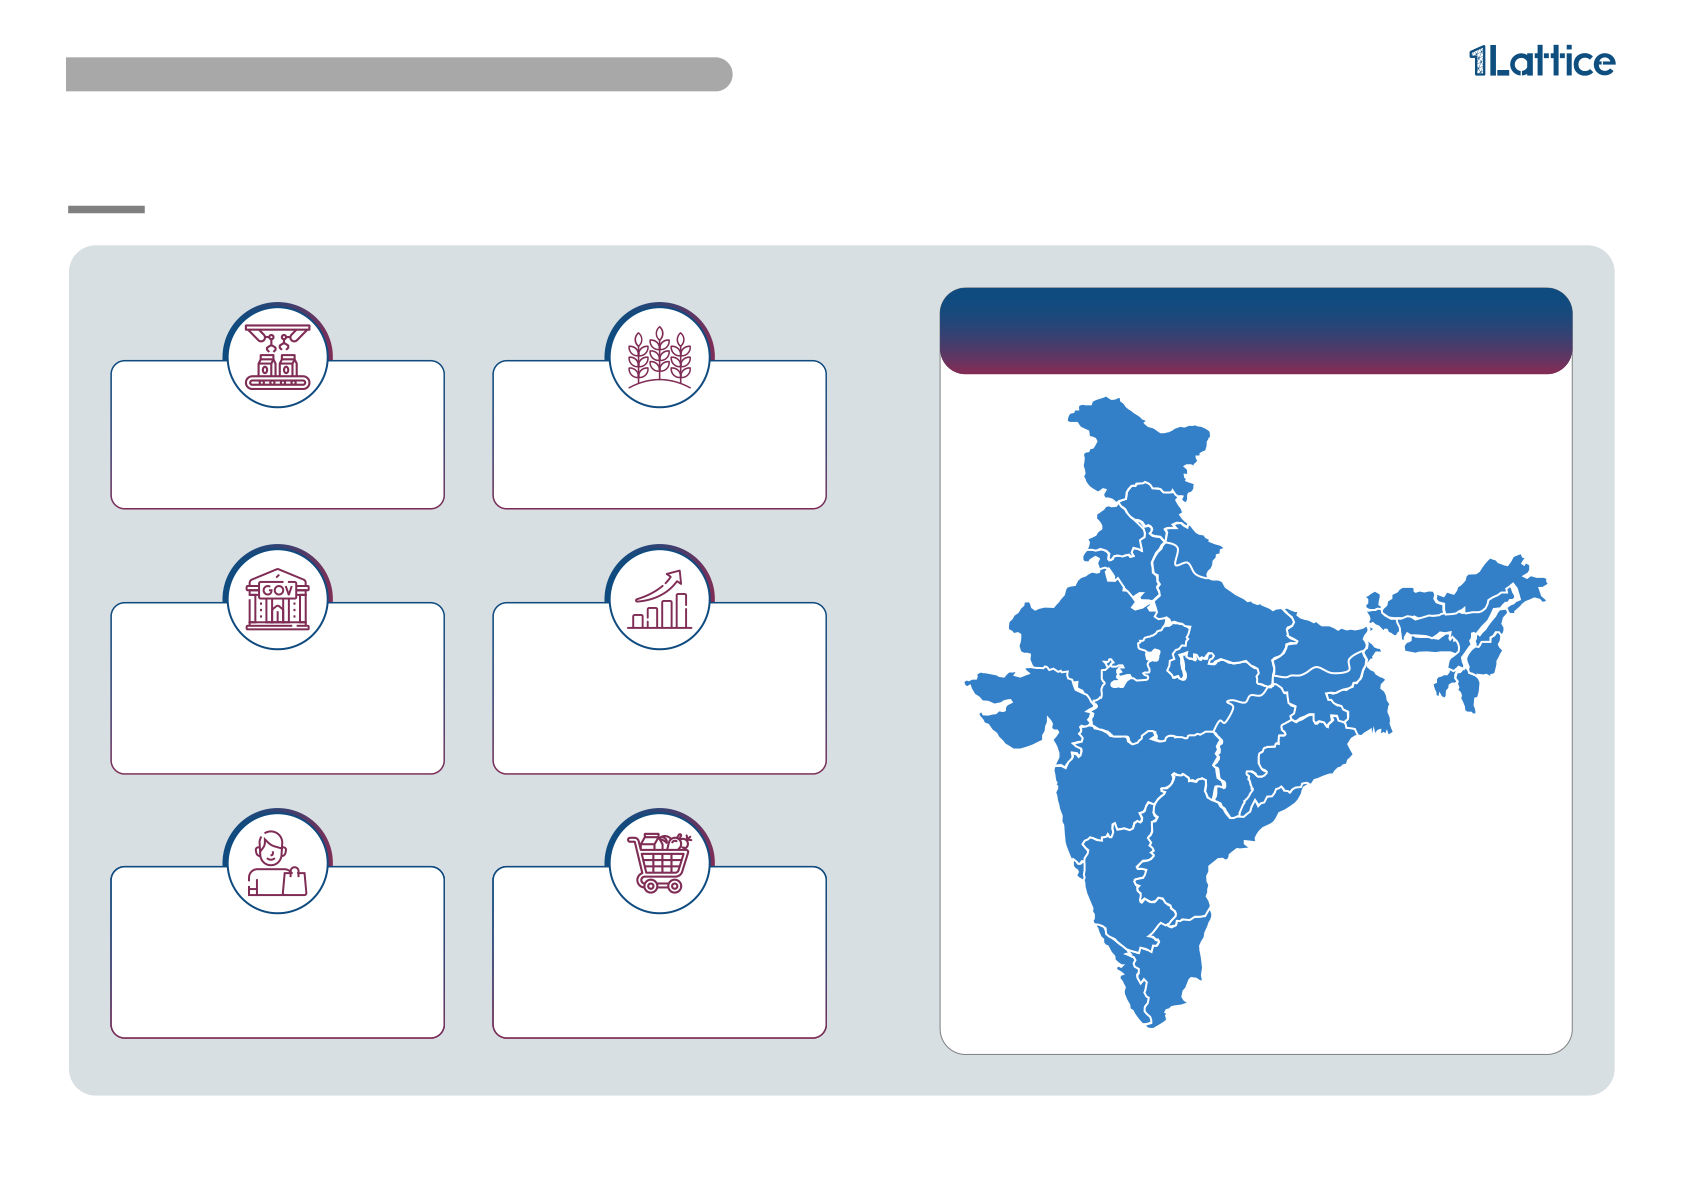
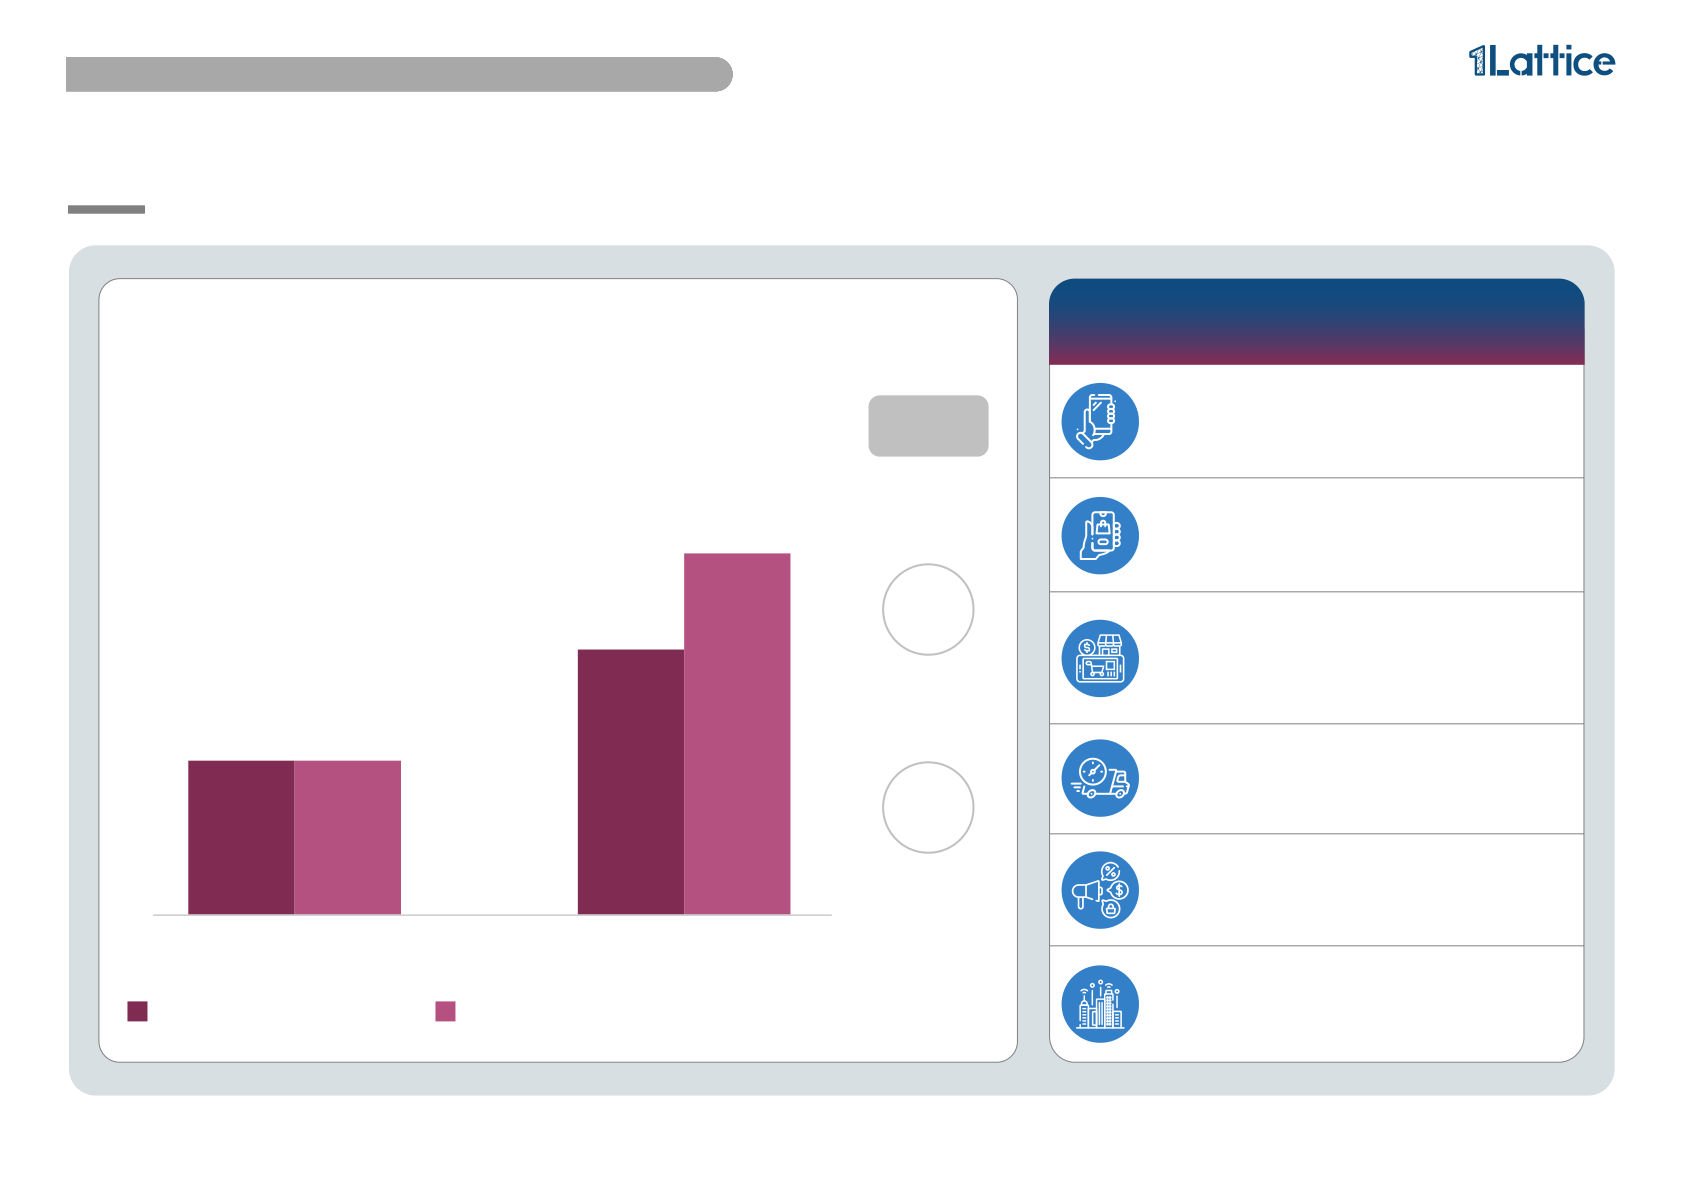
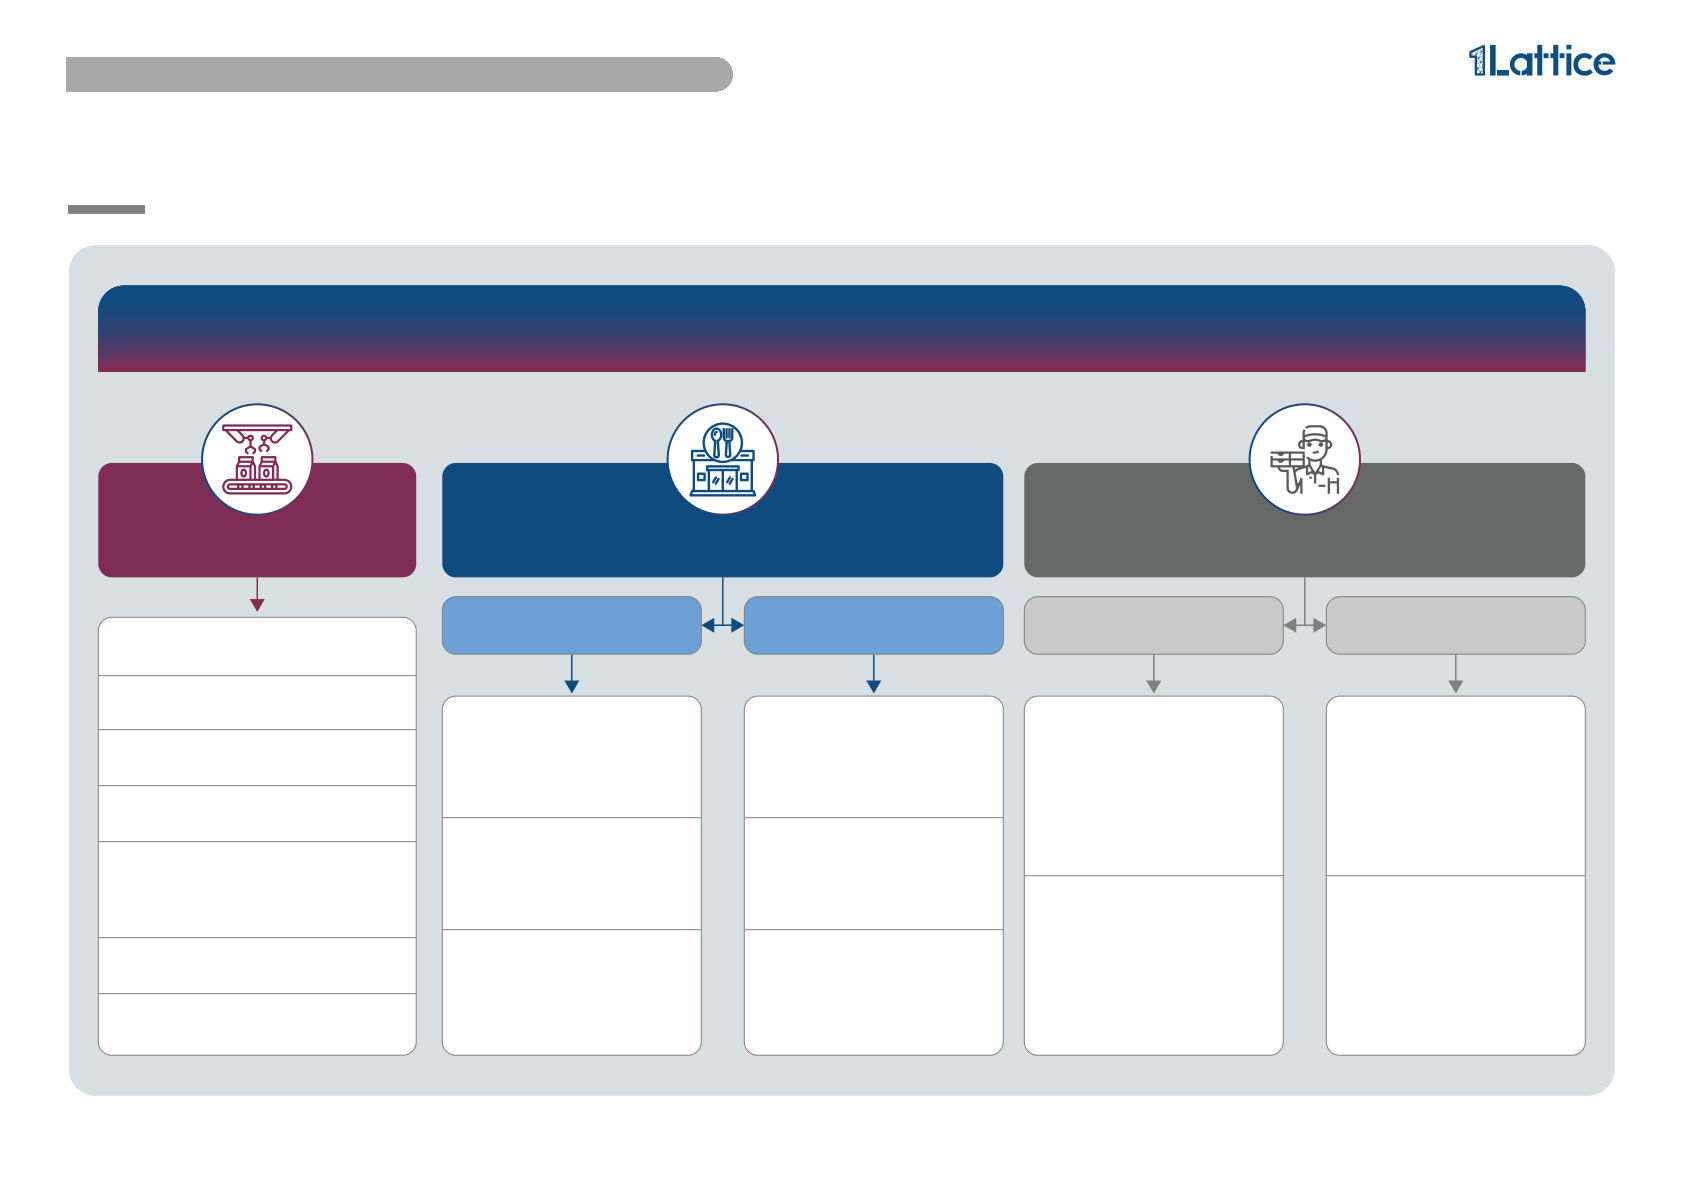
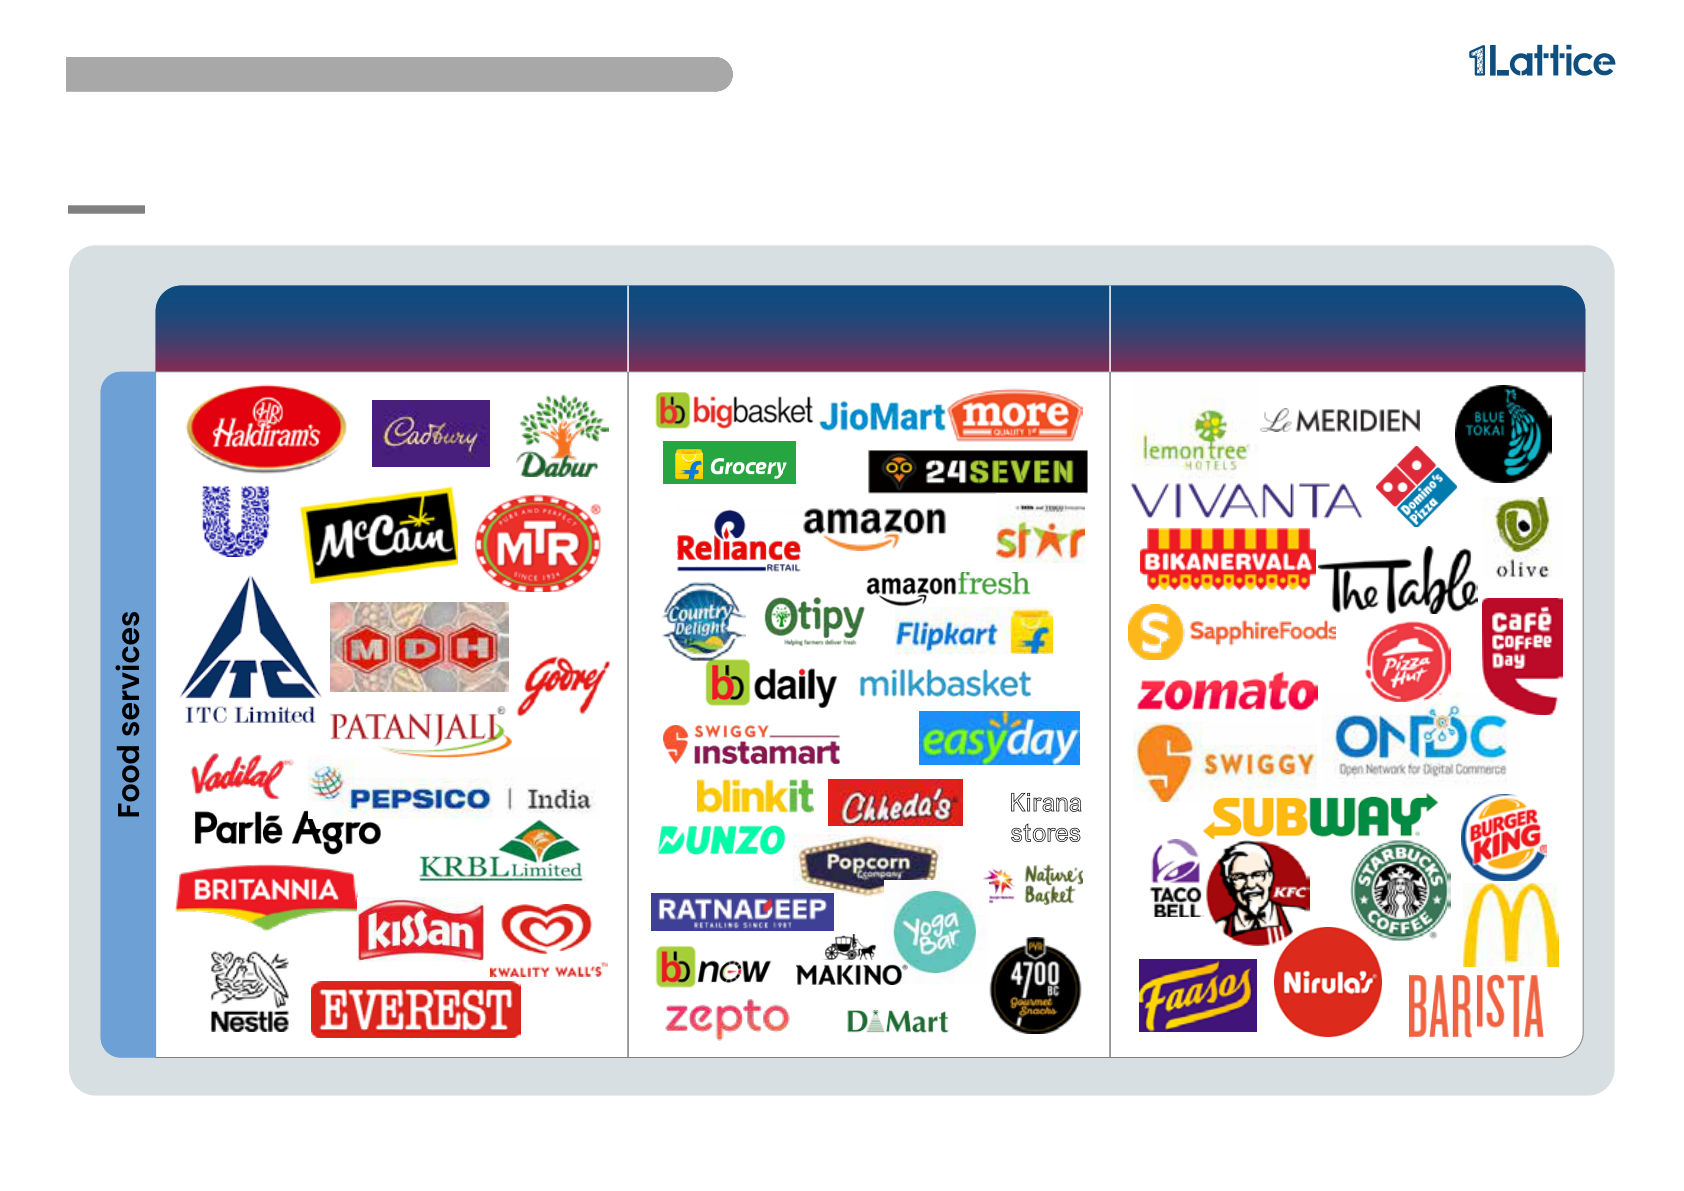
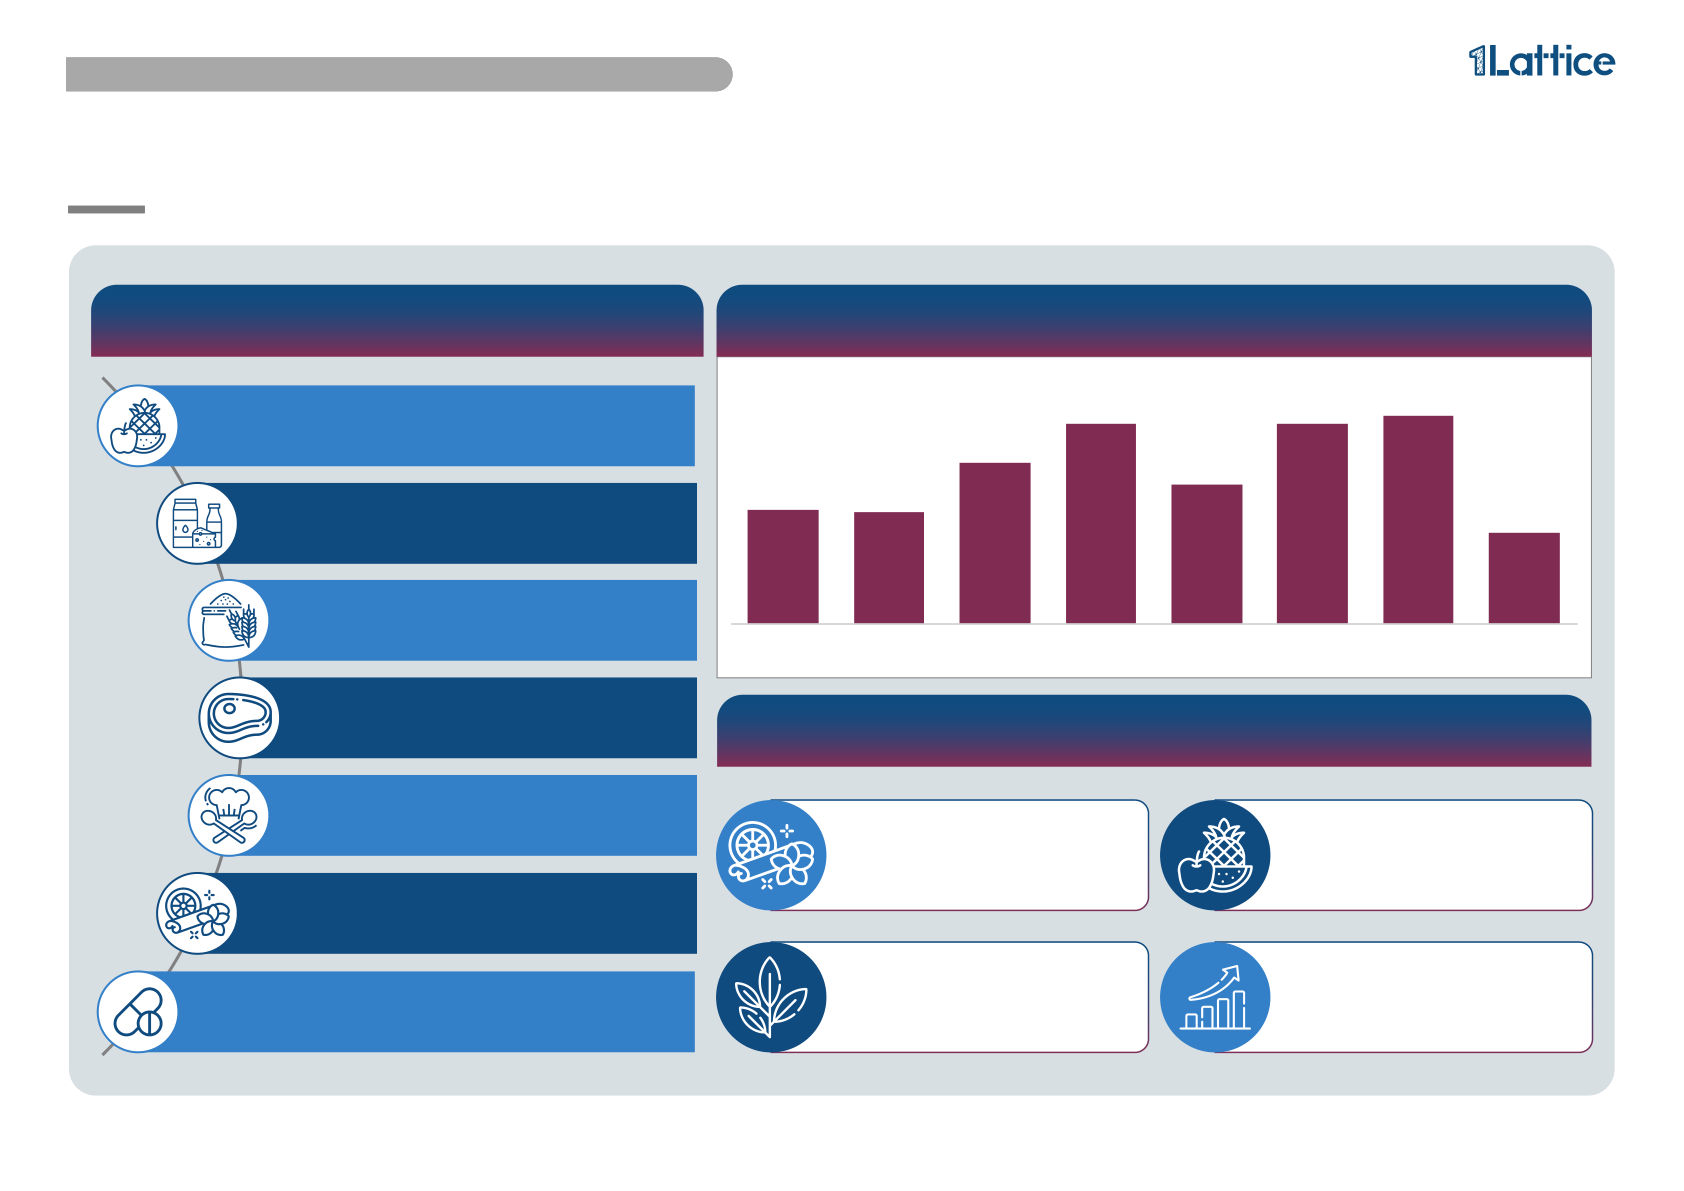
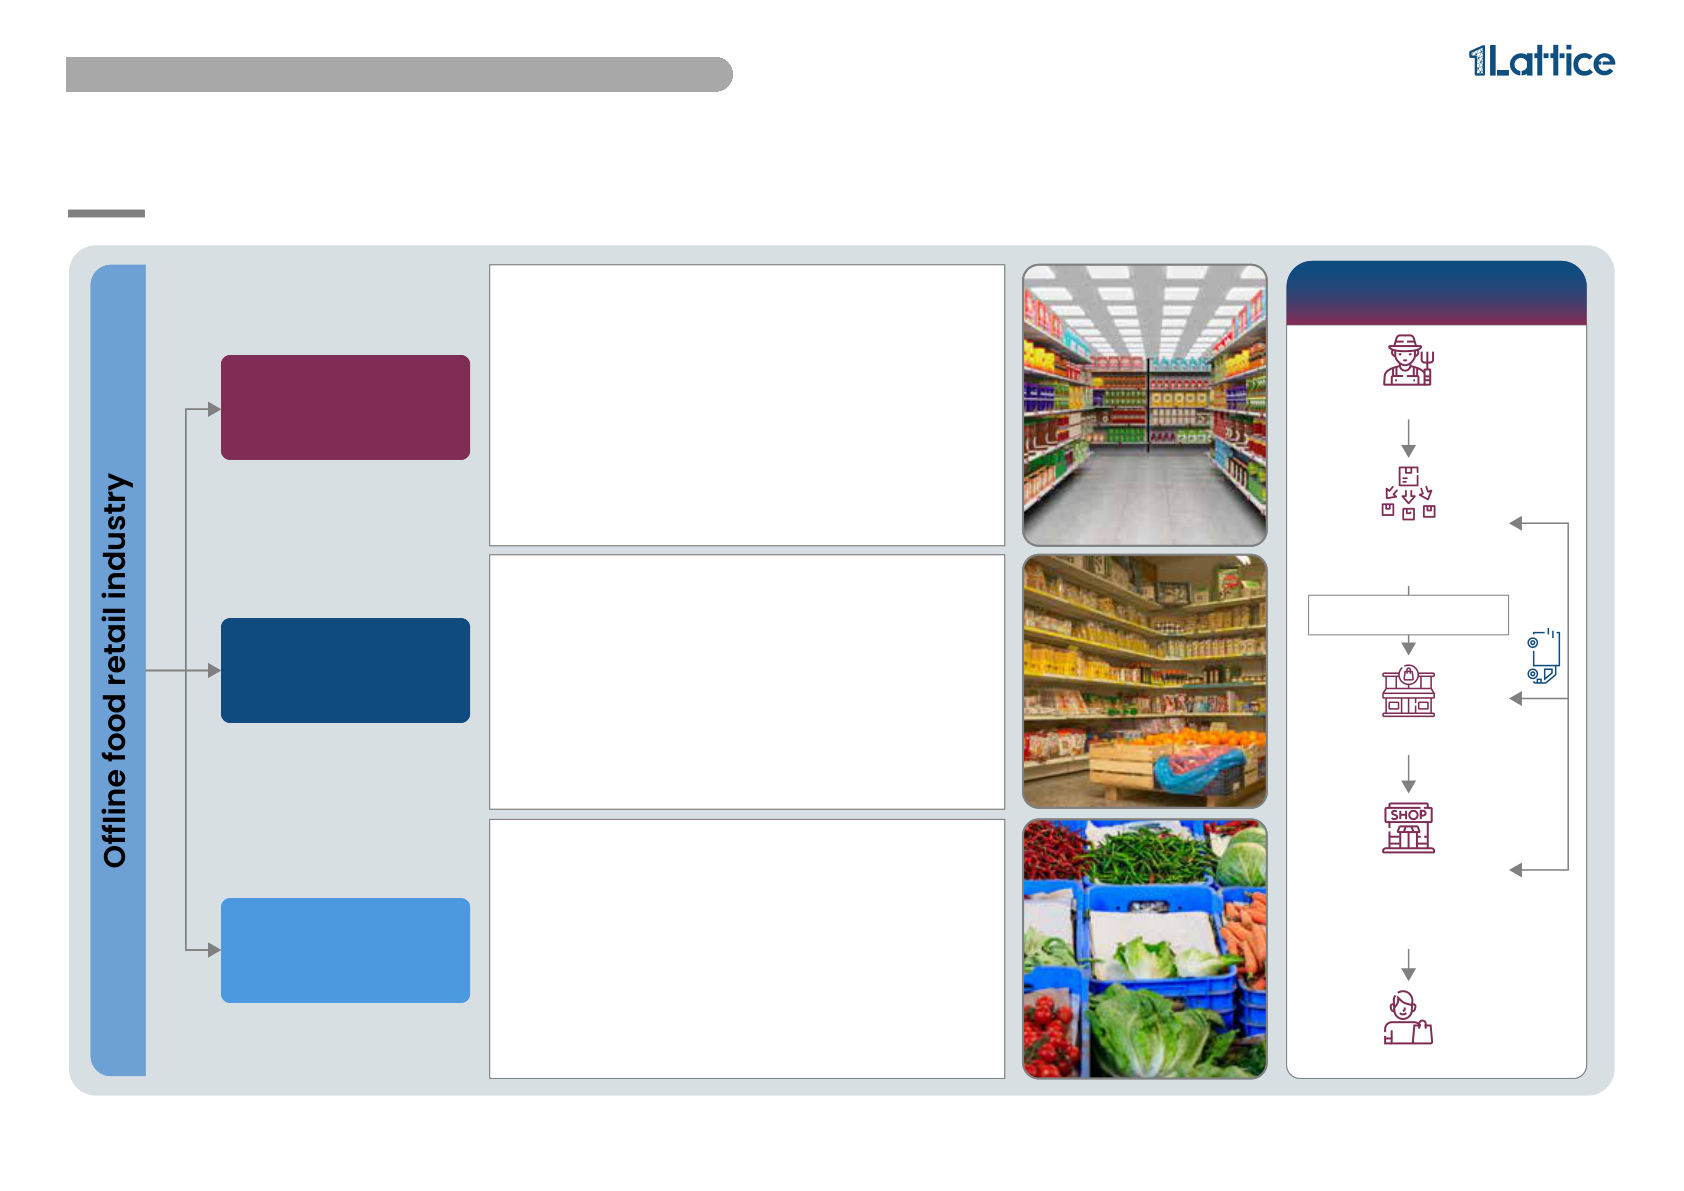
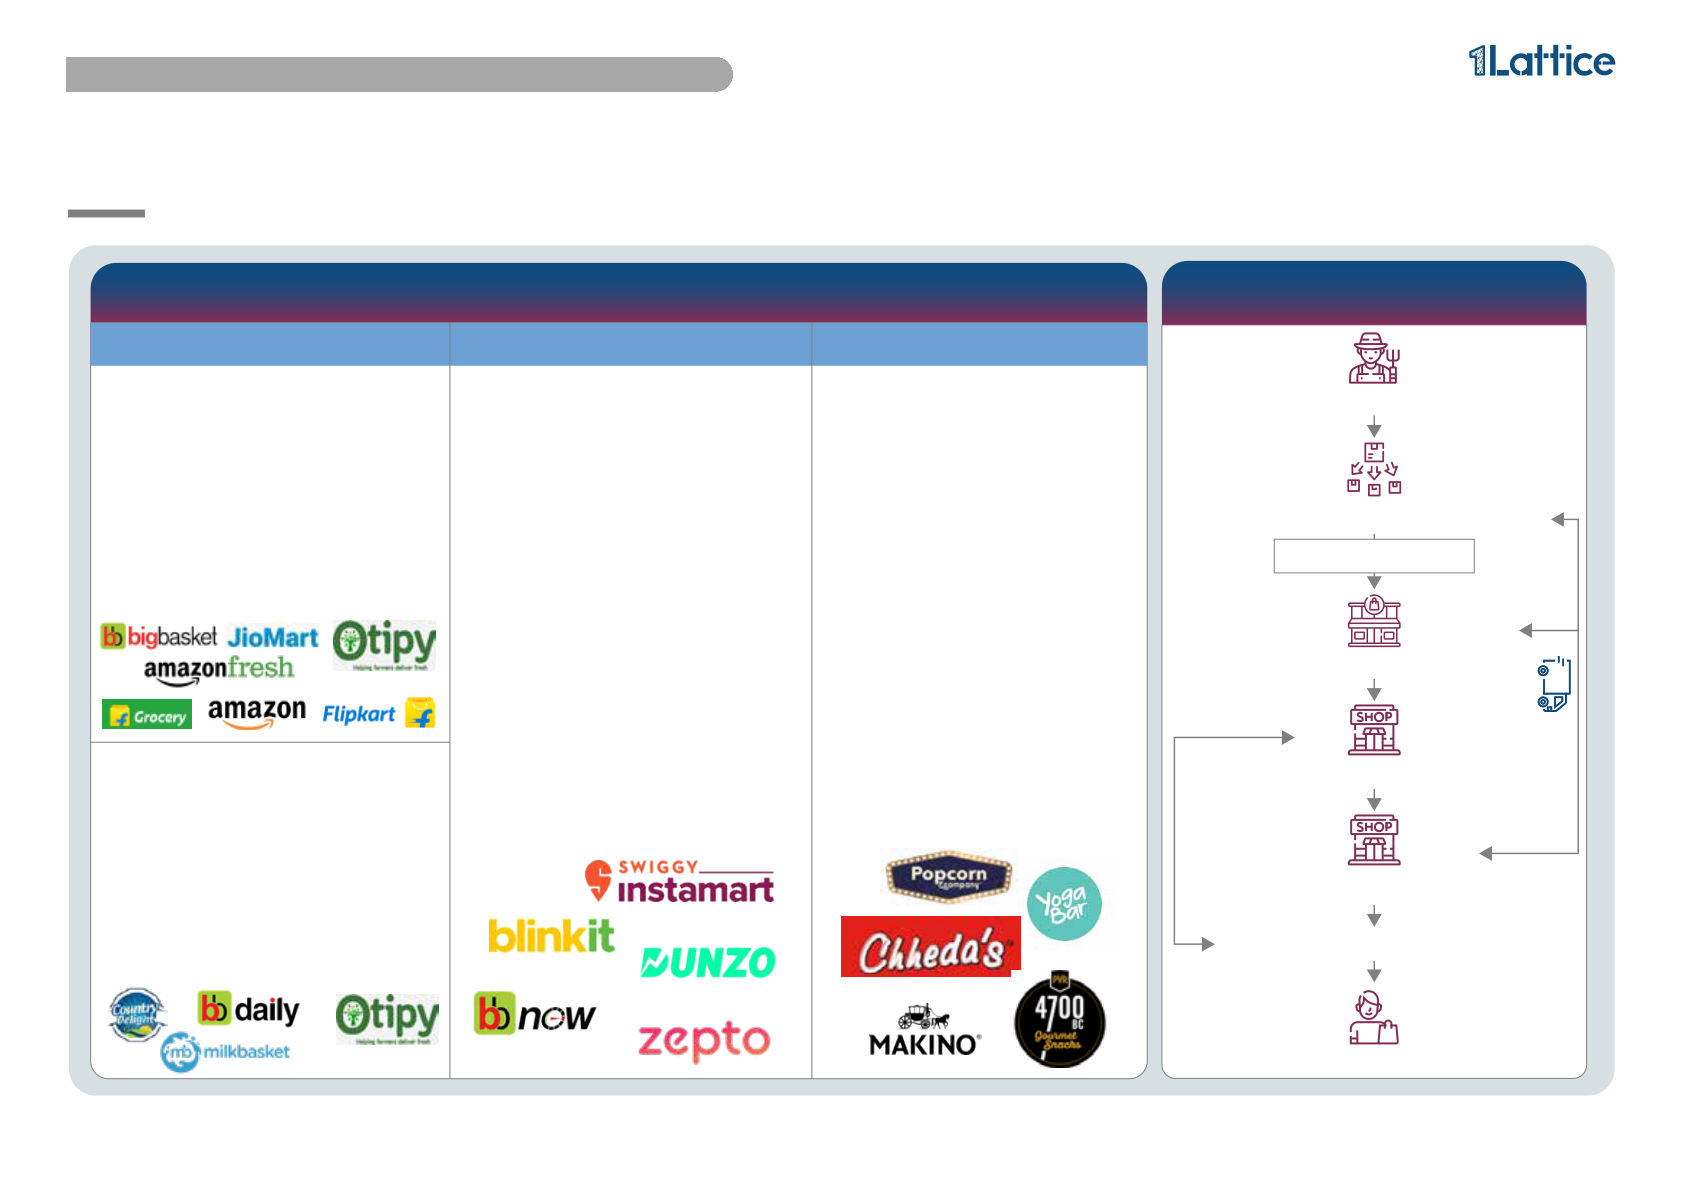
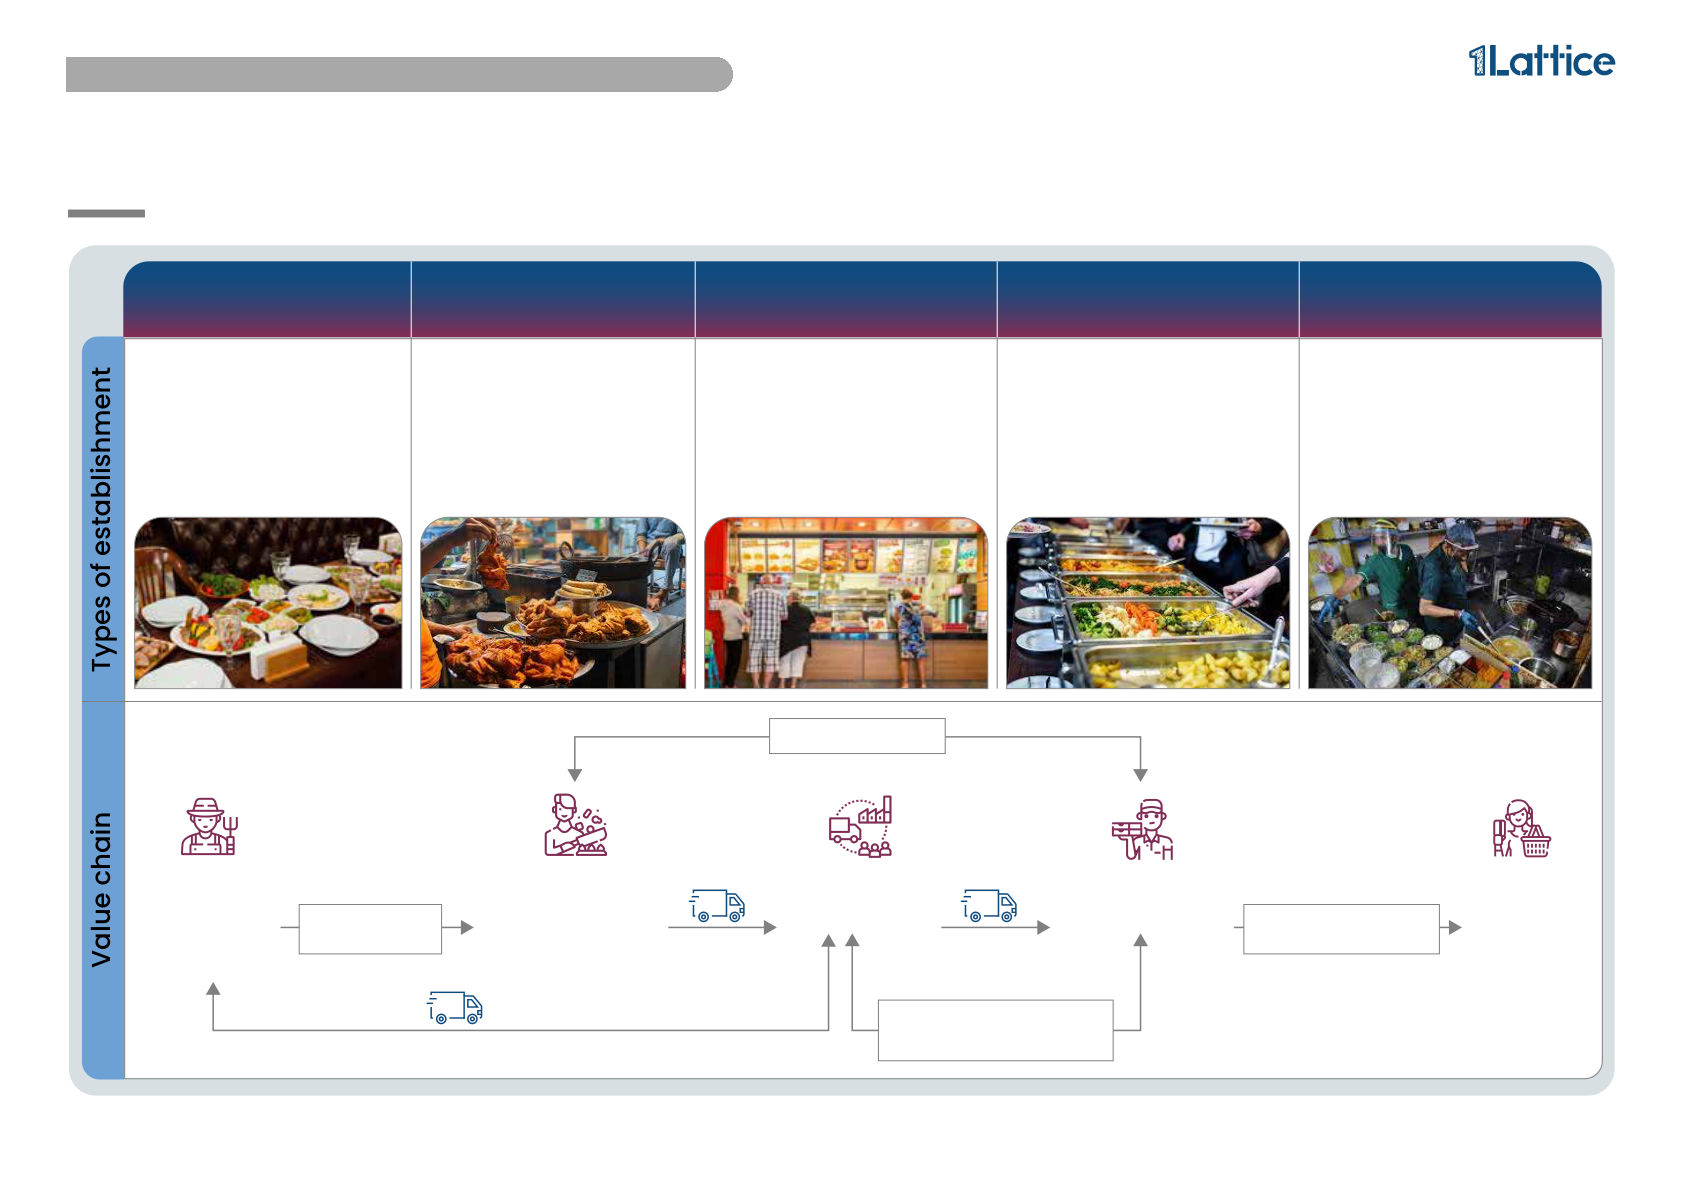
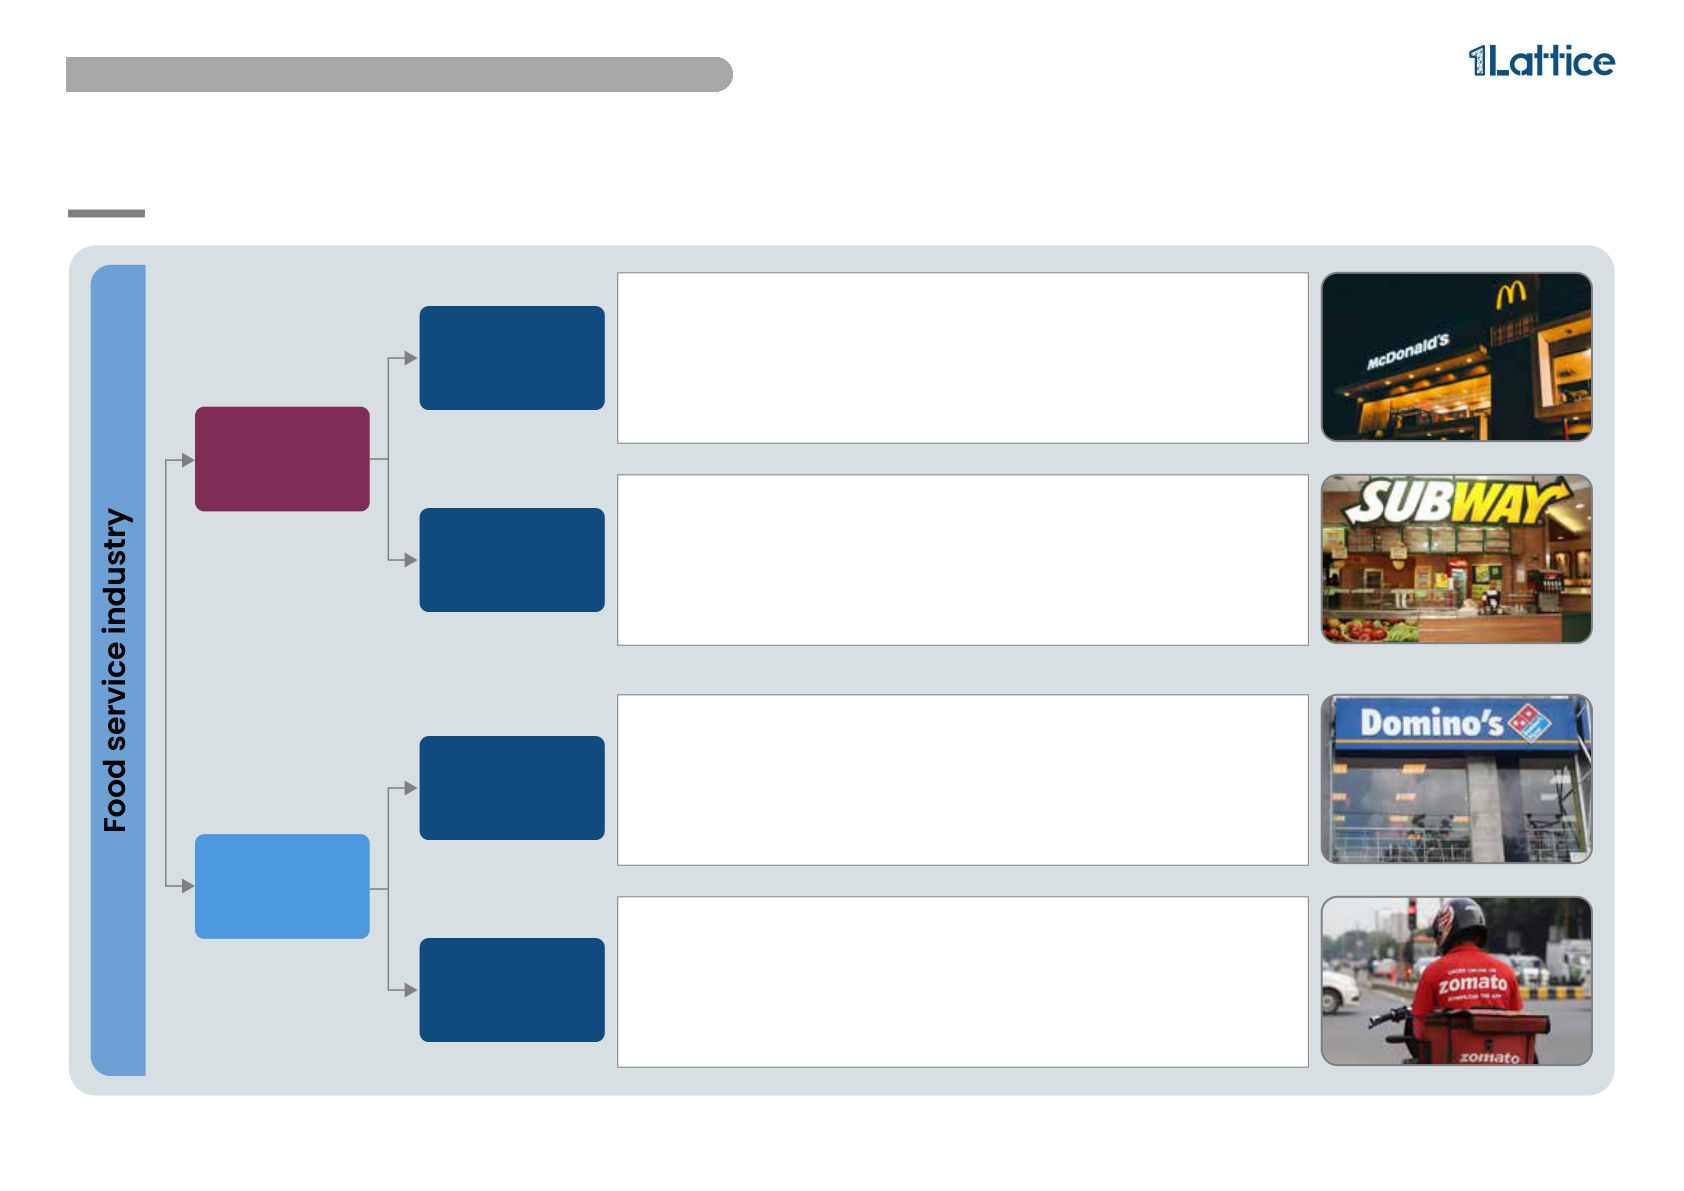
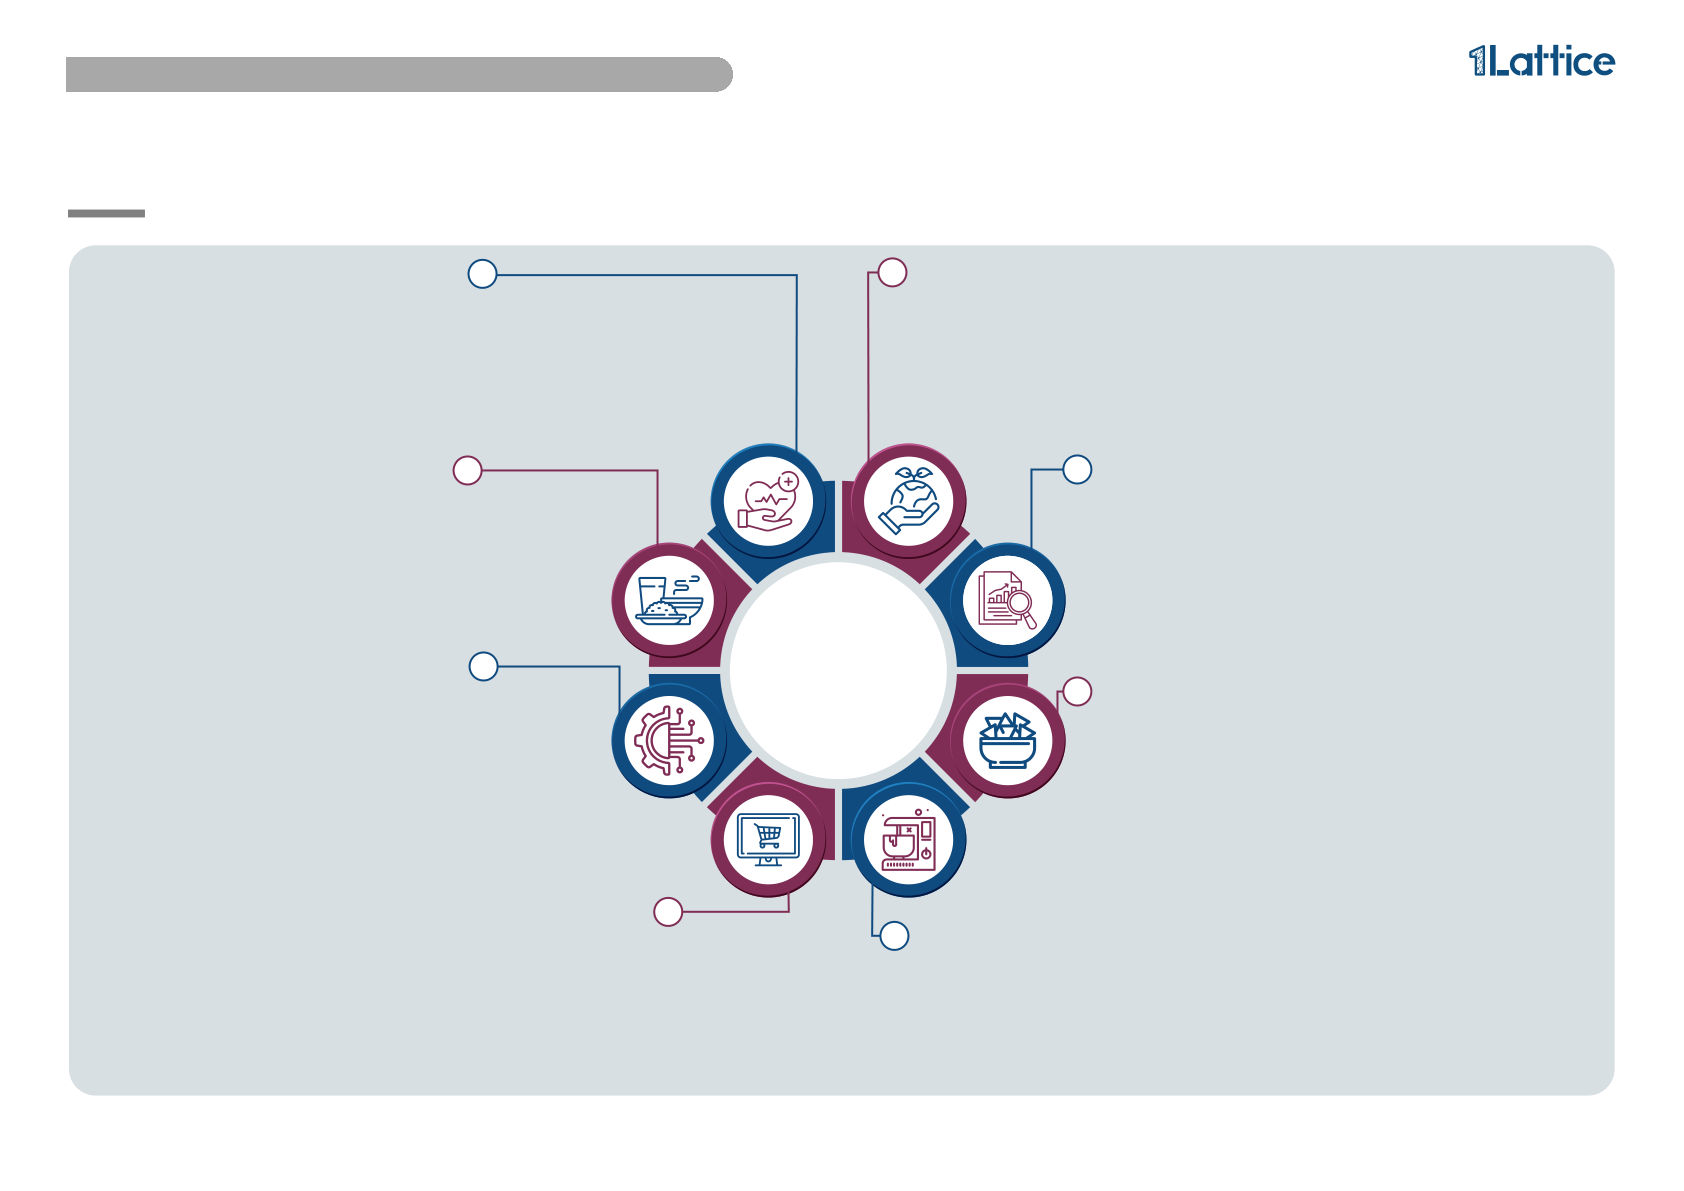
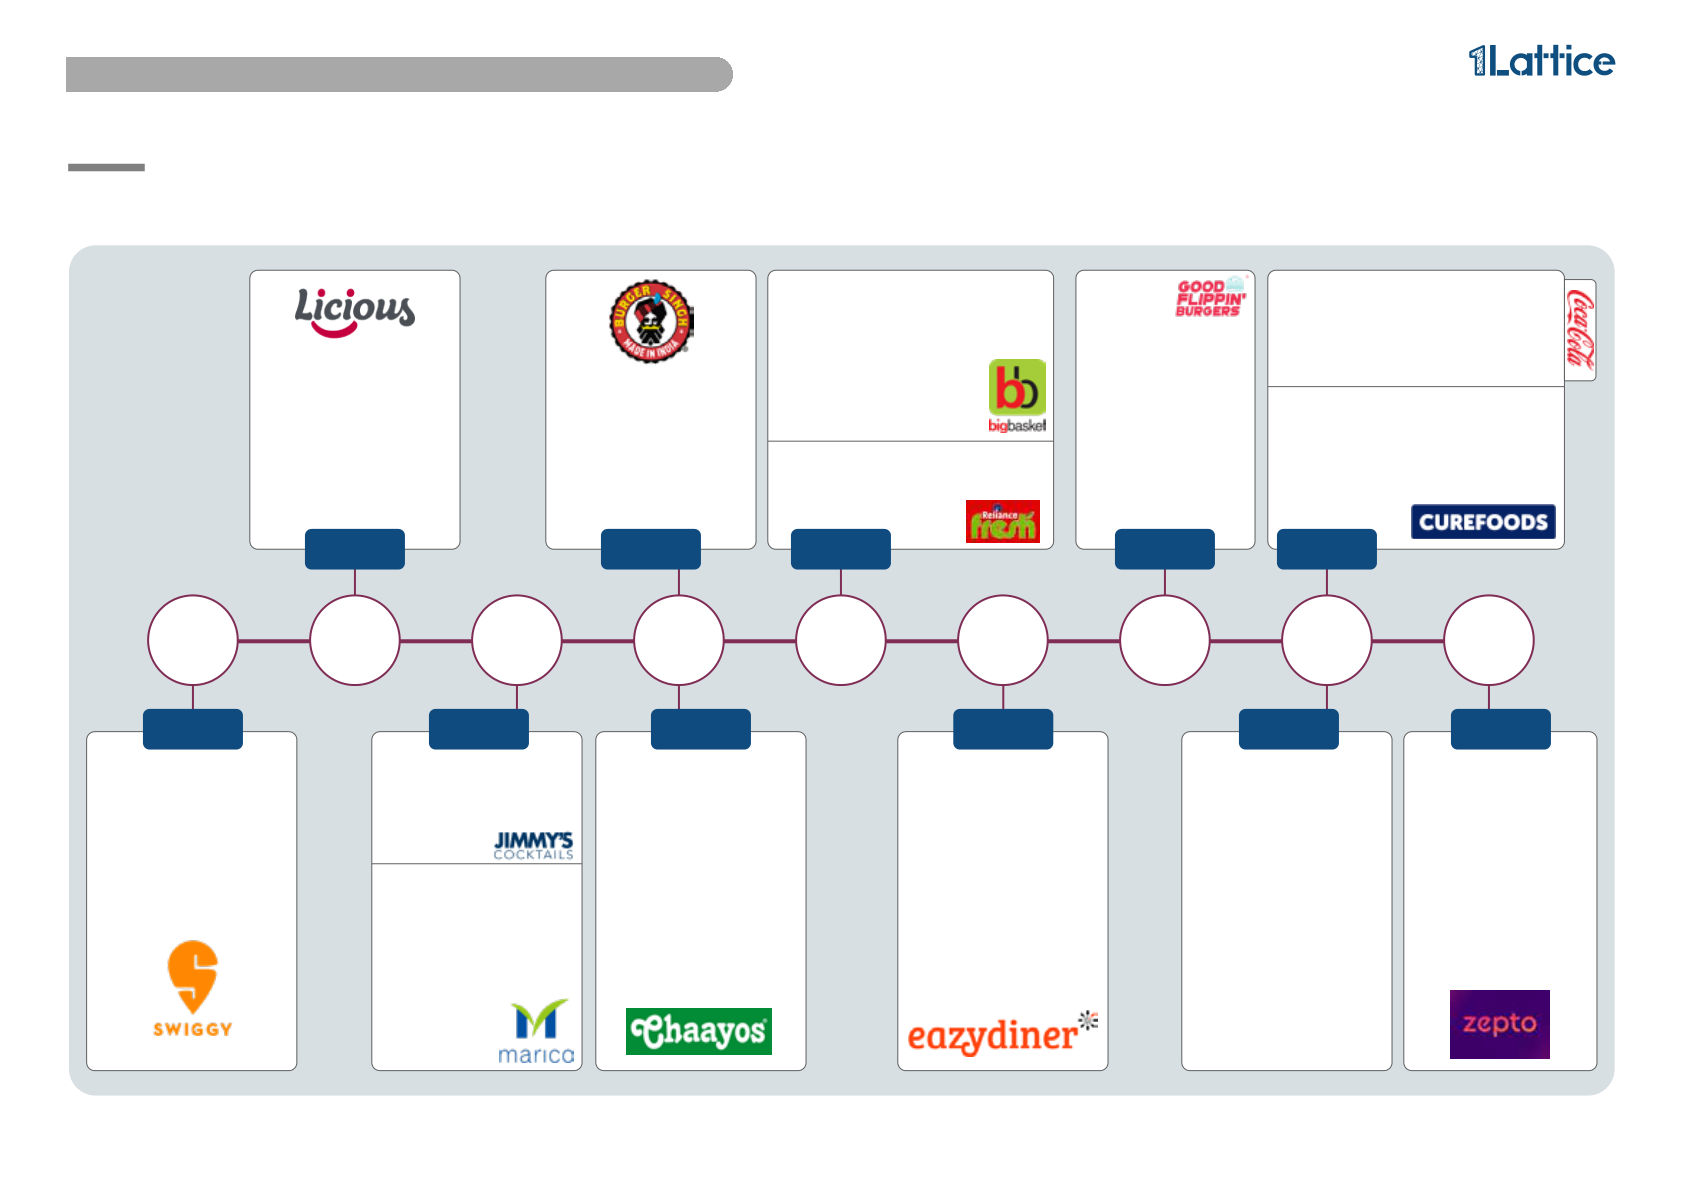
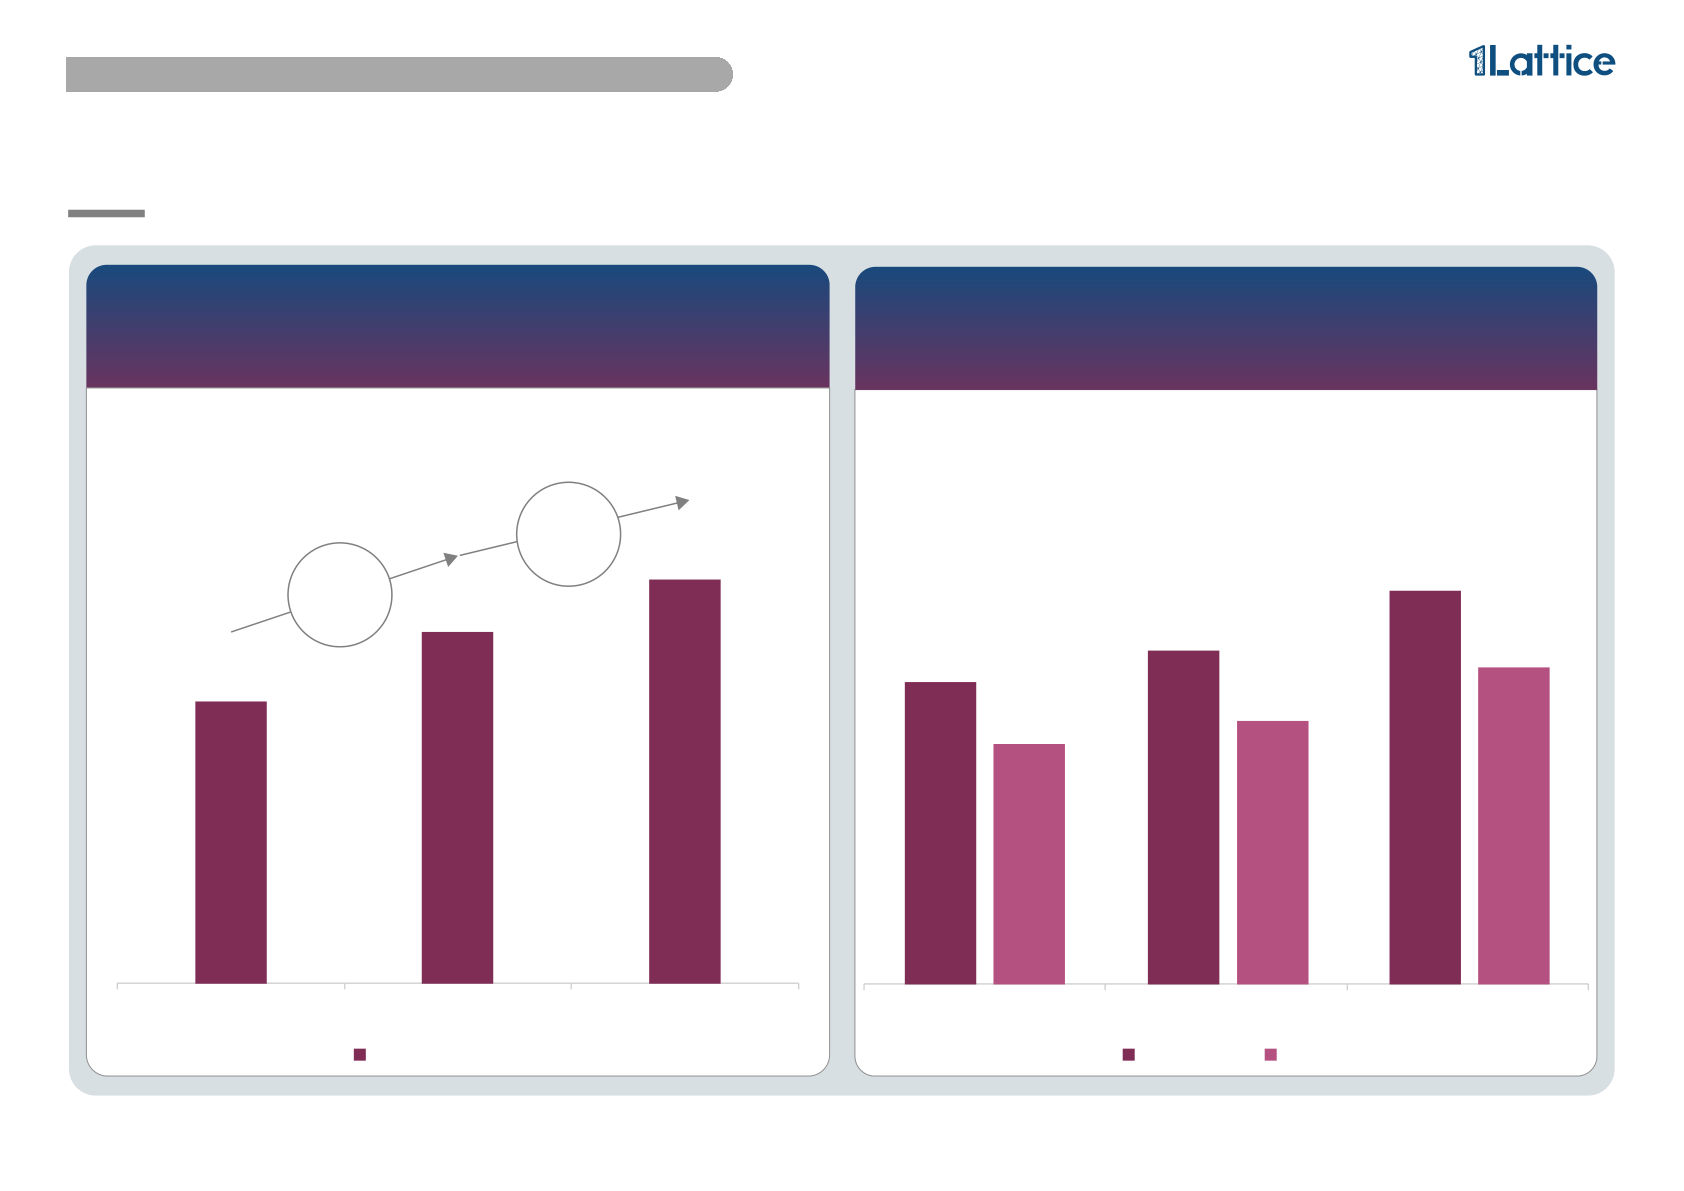
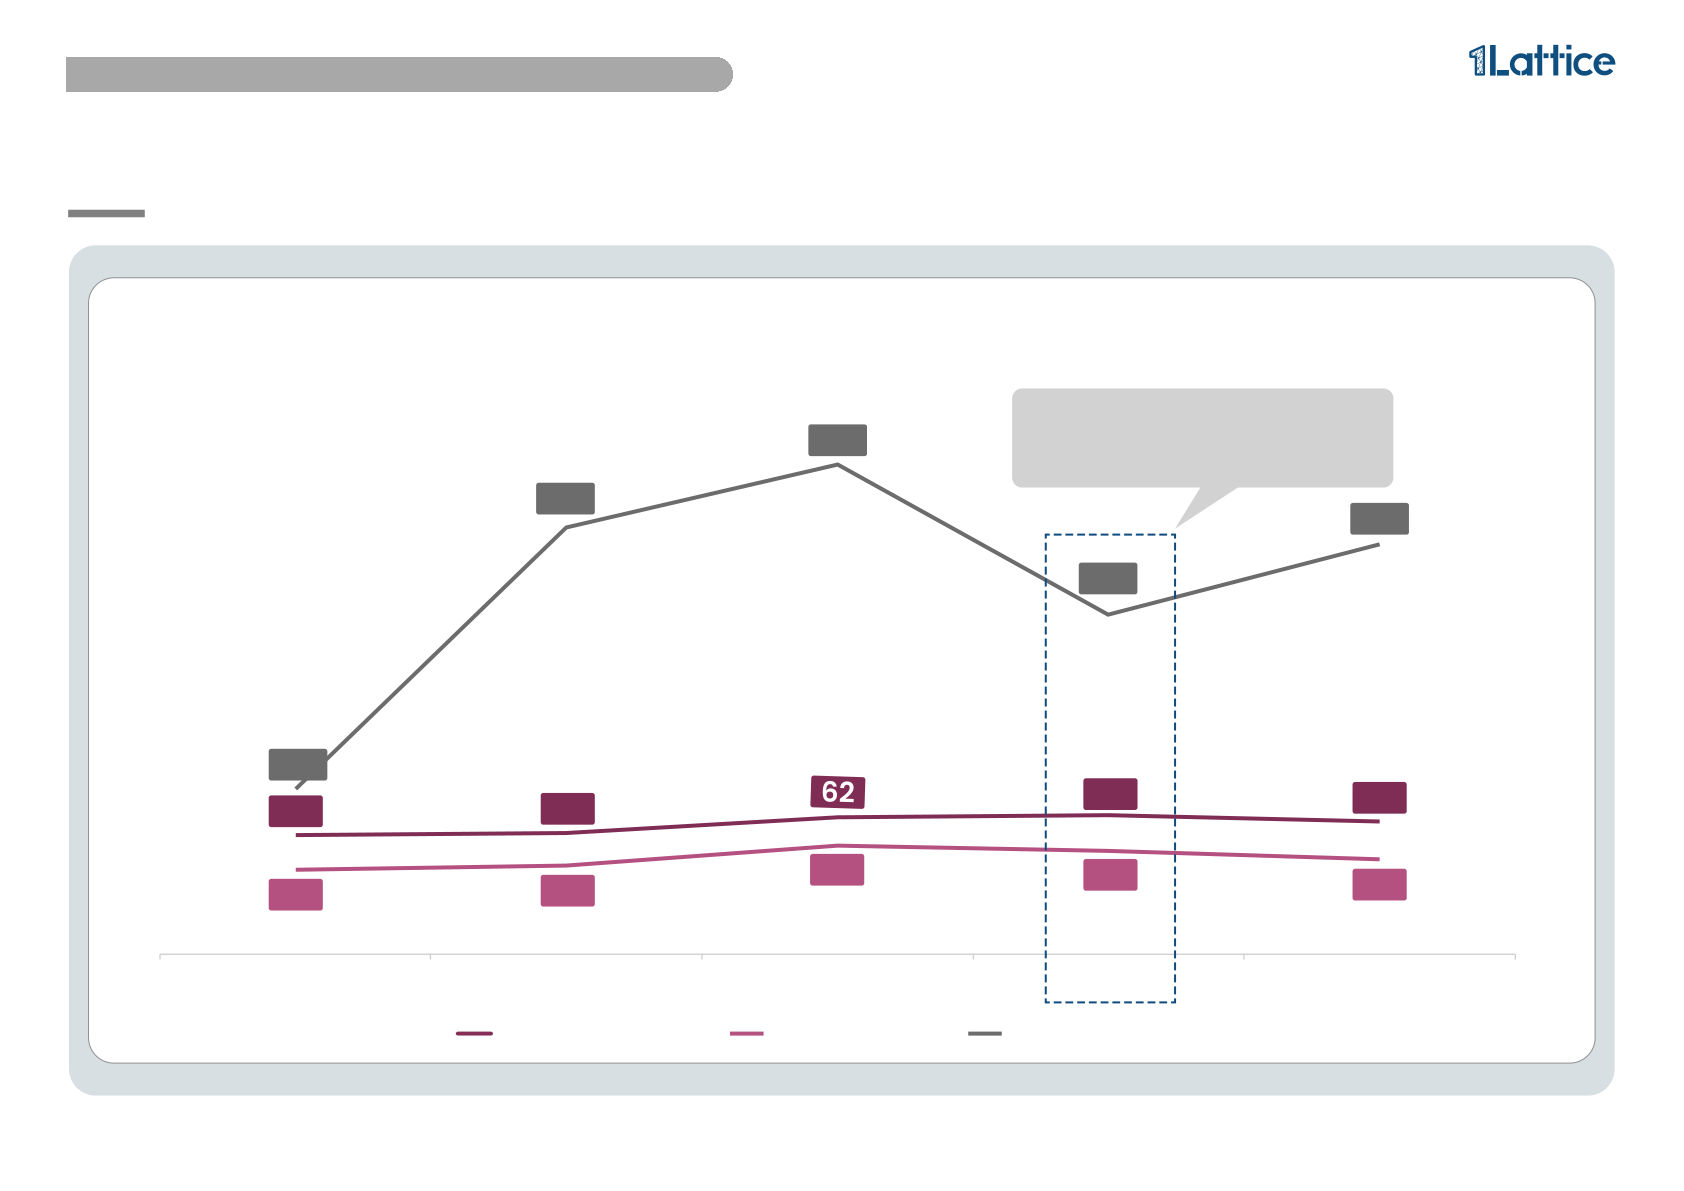
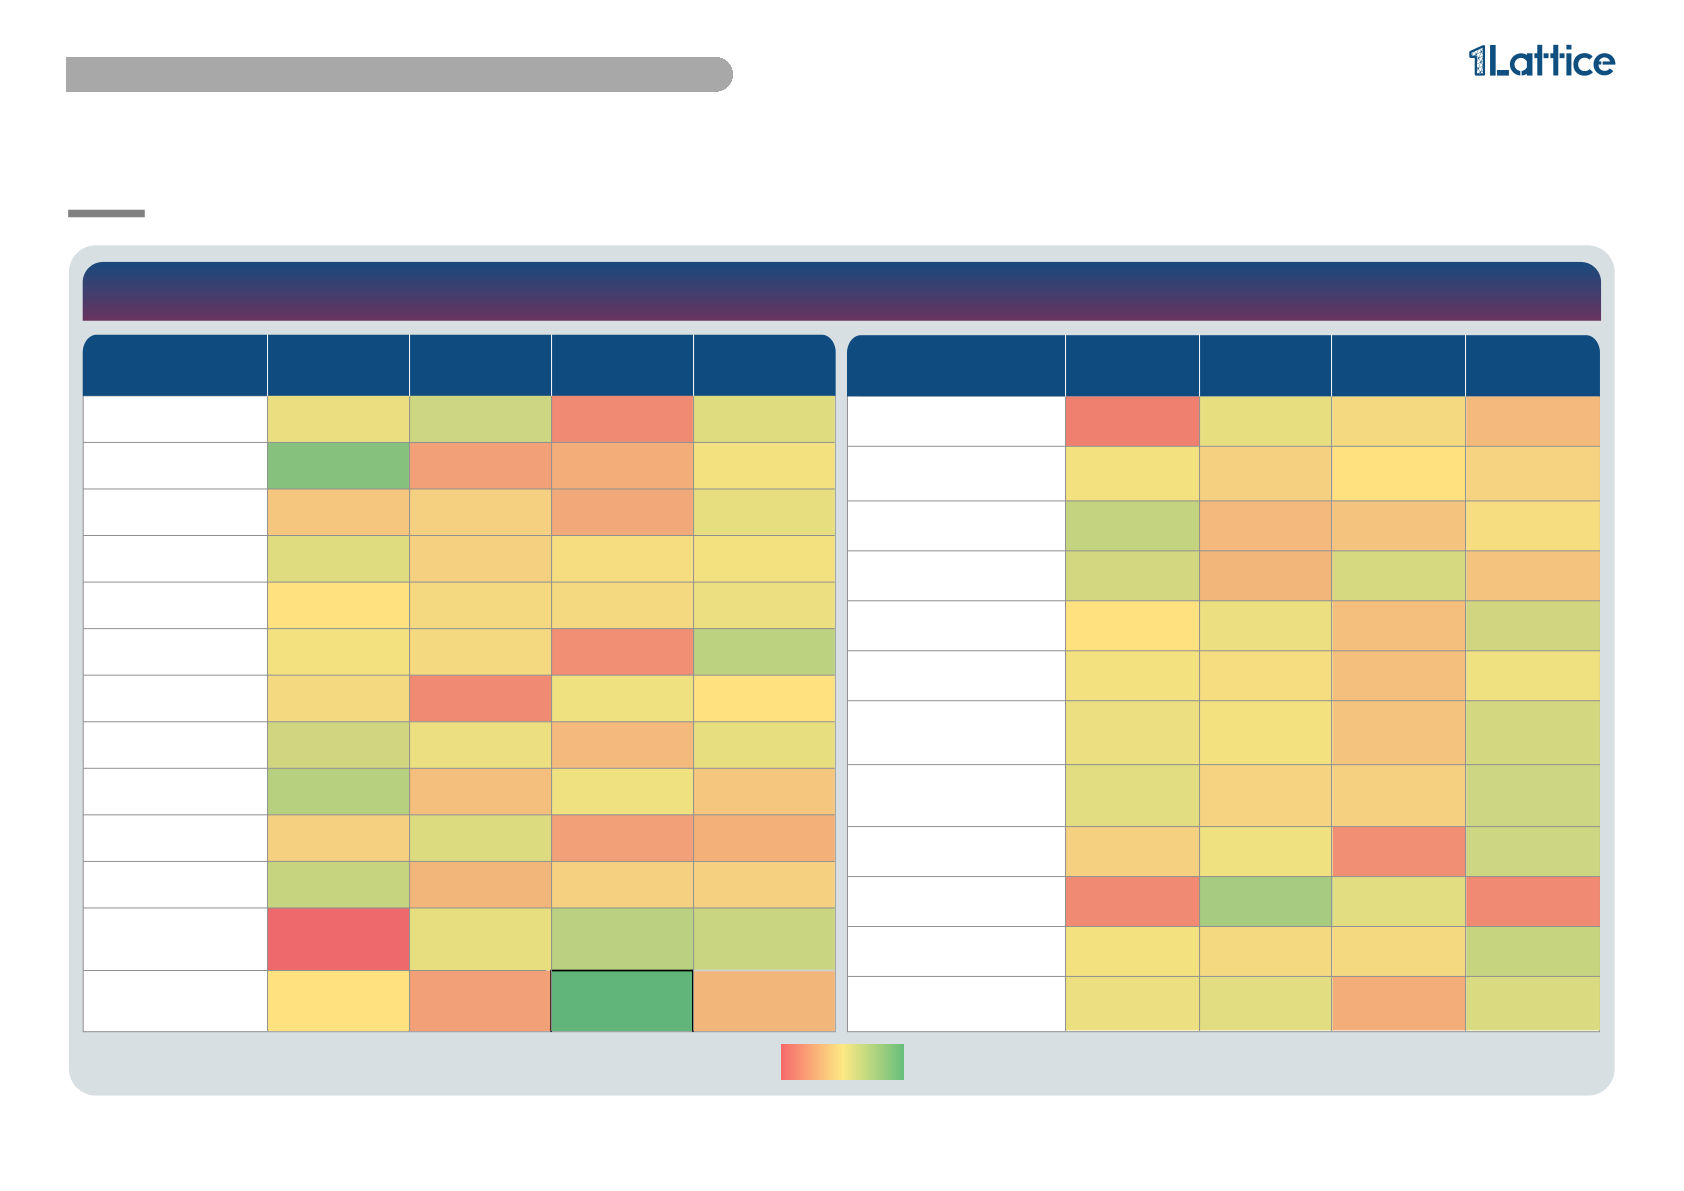
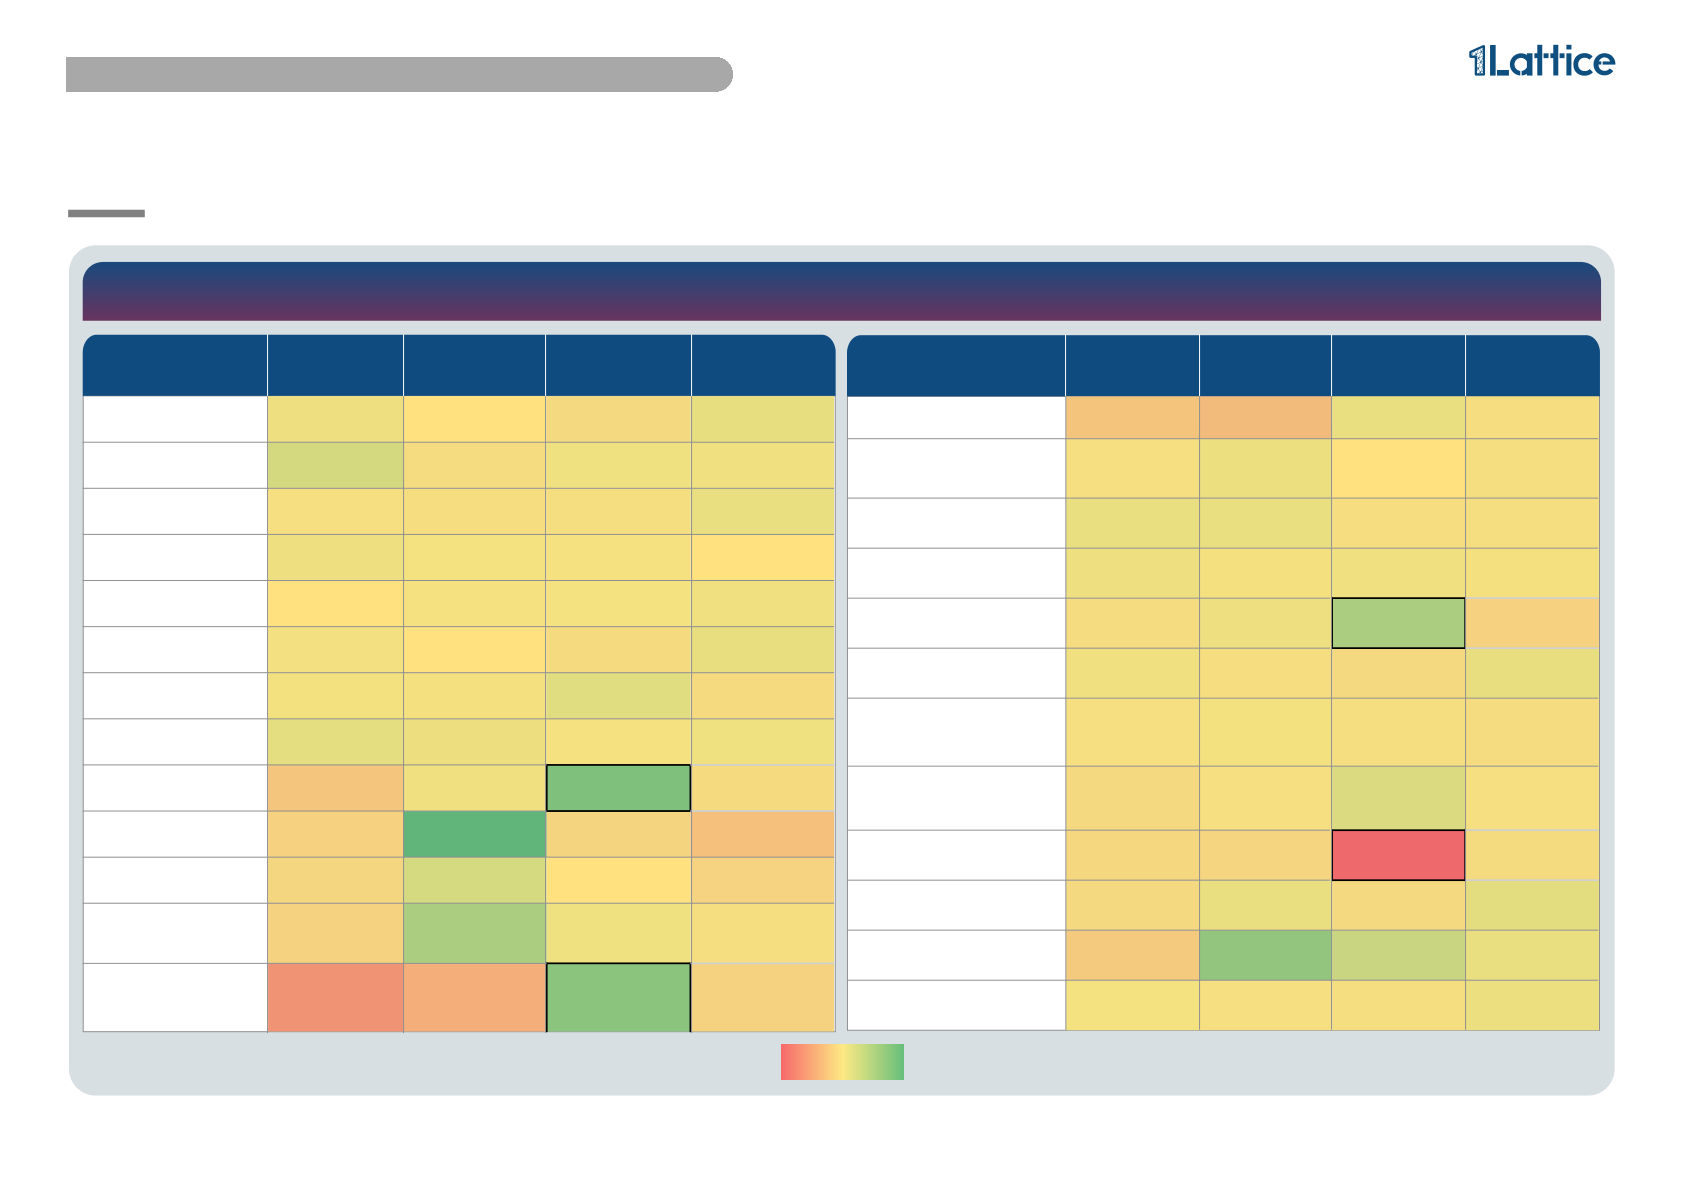
Nourishing India A HOLISTIC VIEW OF THE Food & Grocery SECTOR November 2023 @Lattice Technologies Pvt. Ltd. About the product At 1Lattice, we proudly tailor our array of solutions to meet In sectors such as Fashion, Food and Grocery, Footwear, the unique needs of our esteemed clients in the and many others, 1nsights becomes your strategic Consumer and Retail Sectors. Our flagship product, partner, providing comprehensive insights to drive your 1nsights consistently takes center stage in these success. We understand that thriving in these fields partnerships, helping us gather strategic and insightful hinges on a deep understanding of market dynamics, knowledge in this dynamic industry. the identification of untapped opportunities, and a proactive approach to overcoming challenges. With We excel in delivering in-depth market assessments, 1nsights, you gain a significant advantage in navigating complete with meticulous market sizing, granular the complex and ever-changing landscape. competitive benchmarking, and precise price benchmarking to ensure that your product or service 1nsights is a robust suite of tools and data which equips stands out in the competitive landscape. Our rigorous you to excel and outperform in your in your respective competitive analysis provides you with a deep markets. We eagerly look forward to the opportunity to understanding of your industry peers, while our expertly partner with you and provide the same level of conducted business plan validation ensures that your dedication and excellence to enable better decision strategies are rooted in market realities. making. Your success remains our primary mission. The Food and Grocery industry is a As India stands at the crossroads of Foreword Foreword dynamic and ever-evolving sector economic growth and socio-cultural that plays a pivotal role in our daily change, the food and grocery market lives. Much like every other industry, it finds itself at the epicenter of this is experiencing rapid growth and transformation. Despite challenges transformation, adapting to changing like price sensitivity and lack of consumer preferences and market infrastructure which plague the conditions. industry, rising health consciousness and rapid urbanization are areas with In the Indian context, the Food and high potential and opportunity in 2023 Grocery industry holds a significant and beyond. This shift in consumer position; It is the largest segment of preferences is swiftly rising and is the overall retail industry, employing a becoming critical to reshaping the significant share of our population. future of food production, processing, Indian food retail market is estimated retail, and services. to reach ~US$ 668B by FY25, out of which online would be ~US$ 9B. As we In this report, we explore the venture into the next decade with over intricacies of the Food and Grocery 1.4B consumers in the Indian market market in India and look forward to itself, the prospects for this industry continuing the discussion with our are nothing short of promising, with friends across sectors and expectations of substantial growth. exchanging notes. Ashish Dhir Executive Vice President Agenda Executive summary Food & Grocery: Indian market outlook Market segmentation Growth drivers & barriers Recent trends & Government initiatives Notable investments & opportunities Food and Grocery market index of India The way ahead Executive summary Food and grocery retail is the largest segment of the retail industry in India and is estimated to reach US$ 668B by 2025, with a CAGR of ~7% US$ 668B US$ 0.4B US$ 25.6B 12.8+ M (Exports of (FDI in food (Traditional (F&G retail market agriculture & processing grocery outlets size by 2025) processed food in in 2022) as of 2023) FY22) ~7% ~63% ~11.6% 8% (share of (F&G share of (share in the (CAGR of F&G agro-food the total employment retail market processing retail industry) by F&G sector) FY22-FY25) in India’s GDP) Source(s): Investindia.gov, IBEF, Media articles, 1Lattice analysis © 1Lattice | 05 Agenda Executive summary Food & Grocery: Indian market outlook Market segmentation Growth drivers & barriers Recent trends & Government initiatives Notable investments & opportunities Food and Grocery market index of India The way ahead Introduction to F&G sector Industry highlights Food processing F&G Industry Food retail Food service ~11.6% is the Food processing Current market size of Food service industry to employment share of industry is estimated to the food retail industry reach ~US$ 105B F&G industry in India be ~US$ 417B by FY25 ~US$ 583B by 2025 ~63% of the retail ~10.4% is the industry ~54% of the monthly Projected market for industry consists of food share in India’s exports grocery budget is spent quick-service and grocery online by consumers in restaurants by 2028 is tier 1 & tier 2 cities ~US$ 32.22B Source(s): InvestIndia.gov, IBEF, MOFPI, media reports,1Lattice analysis © 1Lattice | 07 Value chain of the F&G sector Food and grocery sector ranges from raw material cultivation, food processing to consumer delivery via retail or the food service industry Stages of the food and grocery value chain Agri - food Food processing Offline food retail Online food retail Food service Can source from Wholesalers manufacturers or distributors Cultivation Restaurants Distributors & rearing (Subway, Gulati’s, McDonald’s, etc.) Hub or dark stores can source their products from manufacturers, Packaged food distributors, or wholesalers Organized Cloud kitchen Hub / Dark store Harvesting (Supermarkets like (Liveatlife, Slay Big Bazaar, More, coffee, Firangi Restaurants Agri-logistics DMart, etc) & Cold Packaging Warehousing Bake, etc.) source from unorganized storage e-commerce platforms like retailers Hyperpure (kiranas, local E-commerce shops, small Unorganized delivery retailers outlets, etc) Quick service source from aggregators Raw restaurants distributors & material/produce Through Blinkit, Zepto, wholesalers (Burger King, Pizza Manufacturers Swiggy Instamart (Pulses, rice, fruits, Hut, KFC, etc.) vegetables, etc.) Consumer Source(s): Industry reports,1Lattice analysis © 1Lattice | 08 Indian F&G market size Indian food retail market is estimated to reach ~US$ 668 B by FY25 owing to changing lifestyles, new distribution models, & growing technology Indian food & grocery market size (segment wise) Growth drivers (FY22-FY25F, US$ B) • Changing lifestyles and CAGR consumer preferences, more FY22-25 demand for healthy food 668 • Large availability of raw materials in India 10.6% 545 • Growing urban populations led to an increased demand for ready-to-eat & on-the-go food 417 options 7% 308 • Growing segment of e-commerce & delivery services • Transformation of the industry, through technology (food 105 73 delivery apps, automation in 12.5% kitchens, etc.) to increase convenience FY22 FY25F Food processing Food retail Food services Source(s): Investindia.gov, IBEF, Government of India, LinkedIn, 1Lattice analysis © 1Lattice | 09 Prospect of the food industry in India India offers a lot of prospects for the food industry, owing to its diverse agricultural products, expanding GDP, growing consumer base, & favorable Government policies LAND OF OPPORTUNITIES LAND OF OPPORTUNITIES 100% FDI in food Largest producer of processing several agri-products Proactive Government 5th largest economy policies & fiscal in the world incentives 1.42 billion consumers India’s food processing in the market market to reach US$417 B by 2025 Source(s): MOFPI, 1Lattice analysis © 1Lattice | 10 Indian online F&G market size Indian online food retail market is estimated to reach ~US$ 9B by FY25 owing to rapid smartphone penetration & digital adoption, and growing demand for convenience Key drivers of growth Indian online F&G market size (segment wise) (FY22-FY25F, US$ B) • India to have 1B smartphone users CAGR by 2026, with rural areas driving FY22-25 the demand • Rapid digital adoption , with ~880M 12 people online & around 9,000Cr digital transactions till CY22 19.9% • Rising consumer preference for 9 online shopping, fueled by convenience and a wide range of product options 5 5 • Integration of hyperlocal delivery models enables faster order fulfillment & reduces delivery cost 33.0% • Promotions & discounts , offered by online platforms, increases loyalty FY22 FY25F • Growing expansion beyond Tier 1 Online food retail Online food delivery service cities plays a key role Source(s): IBEF, Industry reports, 1Lattice analysis © 1Lattice | 11 Agenda Executive summary Food & Grocery: Indian market outlook Market segmentation Growth drivers & barriers Recent trends & Government initiatives Notable investments & opportunities Food and Grocery market index of India The way ahead F&G Industry segmentation Food & grocery industry consists of 3 major segments: food processing, food retail, & food services Key segments of the food & grocery industry Key segments of the food & grocery industry Key segments of the food & grocery industry Key segments of the food & grocery industry Food processing Food services Food retail Food delivery Offline food retail Online food retail Dine-in restaurant Fruits and vegetables Dairy Traditional grocery Hybrid grocery Food grains stores and local Restaurant Company-owned retailers vendors delivery fleet outlets Poultry and meat Ready to eat / Supermarkets Meal kit services ready to cook Delivery Franchisee-owned Spices Online Specialty aggregators outlets aggregators food stores Nutraceuticals Source(s): 1Lattice analysis © 1Lattice | 13 Competitors landscape Indian food & grocery landscape has food processing manufacturers, food retail players, & players providing services related to food and grocery Food processing Food retail Food services Food services K i r a n a s t o r e s Source(s): 1Lattice analysis © 1Lattice | 14 Agenda Executive summary Food & Grocery: Indian market outlook Market segmentation Food processing Food retail Food services Growth drivers & barriers Recent trends & Government initiatives Notable Investments & opportunities Food and Grocery market index of India The way ahead Food processing: Overview Indian food processing industry is one of the largest in the world in terms of production, consumption, export, and growth potential Key sectors FDI Inflows in Food processing sector in India (US$ M) 939 905 905 Fruits & vegetables 727 628 516 506 411 Dairy Food grains 2014-15 2015-16 2016-17 2017-18 2018-19 2019-20 2020-21 2021-22 Poultry & meat India’s market position Ready-to-eat / ready-to-cook World's largest producer World's second largest of spices, milk and producer of food grains, pulses fruits, and vegetables Spices World’s second largest India’s food processing producer of tea and sector to reach $417 B Nutraceuticals sugarcane by FY25 Source(s): Government of India, 1Lattice analysis © 1Lattice | 16 Food processing: value chain Value chain of fruits and vegetables and dairy processing Value chain of fruits and vegetables and dairy processing Value chain of fruits and vegetables and dairy processing Value chain of fruits and vegetables and dairy processing Fruits & vegetables value chain Fruits & vegetables value chain Food grains value chain Food grains value chain Primary & Retailing Aggregation secondary Distribution Inputs & export processing • Seeds & planting • Collection Agents • Cleaning • Cold storage • E-commerce material • Firms • Grading • Pack houses • Convenience stores • Fertilizers • Traders • Sorting • Warehouses • Supermarkets • Farm equipments • Cooperatives • Packaging • Department stores • Private Mandis • Pulping • Export houses • Canning • Dehydration • Powdering Dairy value chain Primary & Retailing Aggregation secondary Distribution Inputs & export processing • Milching animals • Collection Agents • Pasteurization • Private dairy • E-commerce • Cattle feed • Chillers • Packaging • Dairy cooperatives • Convenience stores • Dairy seed • Firms • Value added products • Firms • Supermarkets like toned milk, cream • Fodder • Traders • Commercial vehicles • Department stores milk, butter, ghee, • Milking technology • Milk traders • Export houses ice-cream & other products Source(s): Government of India, 1Lattice analysis © 1Lattice | 17 Food processing: value chain Value chain of food grains and poultry & meat processing Food grains value chain Food Stakeholders Inputs Retailers Consumer companies • Seeds • Farmers • Bakery • Hypermarket • Rural area • Fertilizers • Traders • Snacks • Supermarket • Urban area • Crop protection • Processors • Beverages • Corner shops • Farm machinery • Hotels, restaurants, catering • Crop insurance • Irrigation equipments Poultry & meat value chain Primary Inputs Production Distribution Retailing processing • Animal feed • Animal breeder • Hide removal • Warehouses • Small meat & egg • Veterinary services • Poultry farms • Carcass cutting • Cold storage • Retail chains • Trimming • Wholesalers • Institutional buyers (restaurants, hotels) • Washing • Reefer vehicles • Export Source(s): Government of India, 1Lattice analysis © 1Lattice | 18 Food processing: value chain Value chain of spices and nutraceuticals Spices value chain Food Stakeholders Inputs Retailers Consumer companies • Seeds • Farmers • Ready-to-eat/ready- • Hypermarket • Rural area to-cook segment • Fertilizers • Traders • Supermarket • Urban area • Therapeutic industry • Low-scale processing • Processors • Corner shops machinery • Hotels, restaurants, • Condiments catering Nutraceuticals value chain Inputs Stakeholder Companies Retailers Consumers • Herbs • Farmers • Pharmaceuticals • Pharmacies • Rural area industry • Roots • Traders • Hypermarkets • Urban area • Wellness industry • Medicinal plants • Processors • Supermarkets Source(s): Government of India, 1Lattice analysis Source(s): Government of India, 1Lattice analysis © 1Lattice | 19 Agenda Executive summary Food & Grocery: Indian market outlook Market segmentation Food processing Food retail Food services Growth drivers & barriers Recent trends & Government initiatives Notable Investments & opportunities Food and Grocery market index of India The way ahead Food retail industry overview Indian food retail industry is currently estimated as ~US$ 583B & is expected to reach Indian food retail industry is currently estimated as ~US$ 583B & is expected to reach Indian food retail industry is currently estimated as ~US$ 583B & is expected to reach Indian food retail industry is currently estimated as ~US$ 583B & is expected to reach ~US$ 905B by FY30 ~US$ 905B by FY30 ~US$ 905B by FY30 ~US$ 905B by FY30 Overview Overview Offline food retail Offline food retail Food grains value chain Food grains value chain Online food retail Online food retail Retail market size of Food & grocery (FY19 - FY30F, US$ B) • Refers to the traditional • Refers to the digital or • Food retail constitutes brick-and-mortar stores e-commerce platforms 6% of the organized CAGR and outlets where and services that allow retail industry, whereas it 6% consumers purchase consumers to purchase constitutes 94% of the food and grocery items food and grocery items unorganized retail 905 in person online, often for home industry CAGR delivery or pickup • Divided into organized • Growth in food retail has 7% and unorganized • Two basic methods of been a result of higher 714 retailers , with ordering are through disposable incomes and unorganized retailers either a hybrid grocery easy availability of credit 583 store or an online driving the sector • Food retail in India can aggregator be segmented by their 476 449 channels of distribution i.e. offline and online food retail Largest retail India is the third Food retail market E-grocery consumption largest food retail is valued at penetration in the FY2019 FY2020 FY2023 FY2026F FY2030F category with a market in the ~US$583 B in overall market in Retail market size of Food & Grocery share of ~63% world FY2023 2023 is ~1.2% Source(s): IBEF, USDA, Media article, LinkedIn, 1Lattice repository, 1Lattice analysis © 1Lattice | 21 Offline food retail overview Indian offline food retail market consists of traditional grocery stores & local vendors, Indian offline food retail market consists of traditional grocery stores & local vendors, supermarkets, and specialty food stores supermarkets, and specialty food stores • Backbone of India's offline food retail sector Value chain Value chain Value chain Value chain Value chain Value chain & an integral part of the Indian retail ecosystem Traditional • Typically, small and independently owned , often run by families Farmers grocery stores & • Include neighborhood Kirana stores, local vendors general provision stores, local vendors and small street vendors putting weekly Bazaar like the Monday Bazaar Manufacturers / Distributors • Offer a wide range of food and non-food products to consumers under one roof Food processing Food processing Food processing Food processing • Provide convenience, variety, and a one-stop shopping experience Supermarkets • Organized retail chains in India, such as Smart Bazaar, D-Mart, Spencer's Retail, and Wholesalers More Supermarket have a significant presence in the grocery supermarket sector • Focus on specific food categories or products, for example, stores specializing in Organized & fruits and vegetables, meat and seafood, unorganized dairy products, and organic foods retailers Specialty food • Examples - Nuts and dried fruits stores stores specialize in selling a variety of nuts, dried fruits, etc. while Meat and seafood stores sell meat and meat-related products Consumer Source(s): The economic times, Industry report, 1Lattice analysis © 1Lattice | 22 Offline food retail overview Indian offline food retail market consists of traditional grocery stores & local vendors, supermarkets, and specialty food stores • Traditional grocery stores and supermarket chains that have expanded their operations to include online shopping and home delivery services • Adaptation to e-commerce has enabled these established Hybrid grocery retailers to reach a wider customer base and compete in the retailers growing online grocery market • Examples include Modern Bazaar, Reliance fresh & supermart, DMart, etc. • Meal kit services provide pre-portioned ingredients and recipes to customers, enabling them to prepare meals at home without the need to shop for individual ingredients • Eliminating the need to plan meals , create shopping lists, and Meal kit services shop for ingredients, saving significant time • Examples include Food Darzee, Grow Fit, Healthie, etc. • Digital services connecting consumers with grocery stores and supermarkets through third-party retailers for home delivery of groceries and other items Online • Customers can browse through the virtual catalog of products, add items to their digital shopping cart, and place aggregators orders through the aggregator's website or mobile app • Examples include Bigbasket, Amazon Fresh, Zepto, Swiggy Instamart, etc. Source(s): Investindia.gov, Media article, Mckinsey, 1Lattice analysis © 1Lattice | 23 Online aggregator segmentation Online aggregators play an integral part in the online food retail industry; the value chain flows from farmers to distributors to aggregators to consumer Types of online aggregators Value chain Value chain Value chain Food grains value chain E-commerce Quick commerce Pure play Scheduled delivery Farmers • Online platforms that allow • Quick commerce e-grocery • Businesses primarily customers to order groceries services excel in delivering operating in the online and schedule specific delivery groceries to customers, space , offering a range of typically within 15 minutes to food-related products and • Help users plan , reducing the Manufacturers / Distributors an hour services through internet need for last-minute trips to Food processing platforms physical stores and enabling • Offer a curated selection of better time management essential and popular grocery • These companies have a items digital-first approach and often do not have a • Prioritize convenience over an Wholesalers physical presence extensive product range, making it ideal for customers • Leverage e-commerce seeking quick access to technology to connect with Subscription-based everyday necessities without customers and deliver food Retailers • Online platform where the need for lengthy shopping products and services customers pay a recurring fee trips or planning directly to their doorsteps to access a range of grocery products and have them Hub/ Dark store delivered to their doorstep on a regular basis , typically E-commerce aggregator weekly or monthly Consumer Source(s): Industry report, Media article, 1Lattice analysis © 1Lattice | 24 Barriers to food retail segment A highly fragmented market, price sensitivity, and intense competition are a few barriers and challenges impacting the growth and development of the F&G industry Highly fragmented market • Many small & unorganized players present in the food retail market • Consistent alteration of strategies required to cater to diverse consumer preferences & local tastes Price sensitivity • Highly price-sensitive customers present in India • Delicate balancing required between offering affordable products & maintaining profitability Consumer behaviour and preferences • Indian consumers have unique preferences and shopping habits • Understanding and catering to these preferences is essential for success in the food retail segment Intense competition • Intense competition in the food retail segments with both domestic and international players vying for market share • Surviving and thriving in this competitive landscape requires significant investments in marketing and differentiation Less transparency • Less transparency among manufacturers about needs and wants of consumers • Misleads manufacturers from the areas having growth prospect Source(s): Media articles, industry reports, 1Lattice analysis © 1Lattice | 25 Agenda Executive summary Food & Grocery: Indian market outlook Market segmentation Food processing Food retail Food services Growth drivers & barriers Recent trends & Government initiatives Notable Investments & opportunities Food and Grocery market index of India The way ahead Food service: types of establishments & value chain Food service sector encompasses a wide range of establishments each catering to different customer preferences, occasions, and dining experiences Restaurants Food trucks & Buffet & self-service Food grains value chain Fast food chains Cloud kitchen & cafes street food vendors restaurants Establishments where Mobile food vendors Quick-service restaurants Restaurants where Allowing restaurants to customers dine in and serving a variety of foods offering affordable & customers serve serve customers order meals from a menu and beverages at convenient meals, often themselves from a exclusively through outdoor locations, with a focus on speed and selection of dishes, often delivery aggregator festivals, and events efficiency for a fixed price platforms without the overhead costs Direct sourcing Farmers Food production Wholesalers & Food service Consumer & preparation Distributors establishments Raw material Kitchen operations Supplier procurement (Baking, & service Distributors marinating, cooking) E-commerce delivery aggregators Note(s): # Unnati, Farmley, Agrowave – Tracxn FY 2019 data, Ninjacart - Tracxn FY 2020 data © 1Lattice | 27 Source(s): AgriTech players websites & apps, 1Lattice analysis Food service industry segmentation With changing consumer preferences, food service industry can be broadly divided into two main categories: dine-in restaurants and food delivery • Parent company or corporation owns & operates the restaurant or food establishment directly Company • Parent company has full control over every aspect of the -owned food business, including menu, pricing, marketing strategies, outlets and quality standards. Dine-in restaurants • Individual entrepreneurs or franchisees own and operate the restaurant under the parent company's brand and Franchisee guidelines -owned outlets • Franchisees have a degree of autonomy in managing their outlets • Restaurants with their own delivery fleets offering Restaurant in-house delivery services without relying on third-party delivery fleet delivery platforms Food delivery • Delivery aggregators aggregate menus from numerous restaurants , providing consumers with a wide selection of Delivery food options in one place while handling the ordering and aggregators delivery process Source(s): 1Lattice analysis © 1Lattice | 28 Agenda Executive summary Food & Grocery: Indian market outlook Market segmentation Growth drivers & barriers Recent trends & Government initiatives Notable investments & opportunities Food and Grocery market index of India The way ahead Growth drivers to food retail segment Rising health consciousness, rapid urbanization, innovation in packaging and Government initiatives are few of the factors driving food and grocery industry Demand side Supply side Innovation in food processing, packaging, & storage Rise of organic foods and health & wellness segment • Innovations lead to the creation of new products, improved • According to National Health policy 2017 report, two-thirds of packaging and preservation methods , and enhanced supply the diseases caused are due to the unhealthy lifestyle chain efficiency • Increase in awareness has led to people looking for healthier • Developments according to consumer preference in the alternatives in food to incorporate health in daily consumption sustainability practices , packaging and storage has enriched Rapid urbanization and population growth the consumer experience • Rising urbanization (35.8%) in India along with higher Government initiatives and policy population densities create greater consumer demand for • Government & industry organizations create policies around convenience foods, restaurant dining, & online grocery various aspects of the business environment , from food safety, shopping labeling to agricultural support and trade facilitation • Growing population at a rate of ~ 0.8% , creates higher demand • Policies and programs include the Farm-Table Traceability for products , stimulating market growth and providing Program, One District One Product, and food safety and opportunities for food producers and retailers standards laws Technology and digitalization Affordable private label brands • Increasing acceptance of UPI due to digitalization (at least in • Retailers offer private label or store brand products often the metro cities, practically every store takes digital payments) provide cost-effective alternatives to national brands, • Adoption of Kiranatech (any technology mechanism bringing attracting budget-conscious consumers and boosting sales efficiency to the Kirana value chain or its day-to-day • Shift to private labels as they are affordable, provide a variety functioning) in shops of choices, and assure quality New distribution models • Food delivery aggregators and cloud kitchens , have emerged, Shift towards packaged goods & more convenience providing food service businesses with alternative distribution • Packaged and convenience products cater to consumers' busy channels lifestyles for example pre-packaged meals, ready-to-eat • Quick commerce players are devoted exclusively for delivering snacks , and individually portioned items orders online and quickly to the doorstep Source(s): Deloitte India, Media reports, Investindia.gov,1Lattice analysis © 1Lattice | © 1Lattice | 30 Barriers to F&G Price sensitivity, supply chain inefficiencies, lack of infrastructure are few major challenges of the F&G industry Lack of cutting-edge infrastructure • Food processing businesses operate as SME, often lacking the resources needed to upgrade their facilities and machinery to the latest technology • E-commerce faces infrastructure challenges, such as last-mile delivery logistics, dark store connectivity , etc. Supply chain inefficiencies Reach of the e-commerce sector • Challenges arise due to • Rural India is lagging with a 41% inefficiencies and inadequate share of internet penetration capacities in the chain • Lack of information, fear of getting • Issues in managing food supply duped , and long waiting times for chains, including food safety, lack of deliveries are concerns of rural traceability, etc consumers • For example: breaks in the cold chain can lead to spoilage and safety concerns Price sensitivity among Regulatory challenges customers • Complex regulatory environment • Cost of food can fluctuate due to with numerous licenses and factors such as inflation, permits required at various levels weather-related crop failures , and of government for the F&G industry supply chain disruptions. • Navigating these regulations can • Higher food prices can strain be time-consuming and costly for consumers' budgets , particularly for businesses low-income individuals and families Source(s): Times of India, Fortune India,1Lattice analysis © 1Lattice | 31 Agenda Executive summary Food & Grocery: Indian market outlook Market segmentation Growth drivers & barriers Recent trends & Government initiatives Notable investments & opportunities Food and Grocery market index of India The way ahead Recent developments Rising health consciousness, convenience of meal kits, technology integration and growing e-commerce are the top emerging developments in F&G industry 8 Rising health consciousness Sustainability and environmental concerns 1 • Health-conscious consumers seeking out products that • Increasing conscious of sustainability and environmental align with their dietary preferences and health goals issues • Includes organic, non-GMO, gluten-free, and plant-based • Surge in demand for eco-friendly packaging, locally sourced options products, and companies pledging to reduce their carbon footprint Convenience and meal kits 7 Personalization and data analytics 2 • Fueled popularity of meal kit delivery services • Retailers are leveraging data and AI to and prepared foods owing to busy lifestyle personalize marketing efforts and • Consumers moving towards more convenient recommendations options requiring minimal preparation • This helps in tailoring offers and promotions to individual customer preferences Recent Technology and automation 3 developments 6 Global flavors and ethnic foods • Increasing adoption of technology by grocery • Increased exploration of diverse and global stores to enhance the shopping experience cuisines by consumers • Includes the use of mobile apps for ordering • As a result, grocery stores are expanding and payments, self-checkout kiosks, and their offerings of international and ethnic even cashier-less stores where customers foods to cater to diverse tastes can grab items quickly E-commerce and online grocery shopping 4 Robot kitchen assistants 5 • Significant growth owing to surge in online grocery shopping • Robotic kitchen assistants aim to make cooking and meal after Covid preparation more efficient, convenient, and accessible • Increasing convenience among consumers has led to • Use of robots for meal preparation, food delivery, assembly, increased investments in e-commerce infrastructure and planning assistants and restaurant automation delivery services by grocery retailers Source(s): Nutritics, Cozymeal, MOFPI, LinkedIn, 1Lattice analysis © 1Lattice | 33 Government initiatives & reforms PLISFPI, PMFME & PMKSY are a few reform initiatives taken by the central Government to promote India’s growing food and grocery industry Major Government initiatives in food and grocery sector Production Linked Incentive Pradhan Mantri Formalization Pradhan Mantri Kisan Scheme for Food Processing of Micro Food Processing Sampada Yojana (PMKSY) Industry (PLISFPI) Enterprises (PMFME) • Proposes financial incentive to modernize • Provides support in terms of financial • Comprehensive Government scheme in and enhance competitiveness of the food assistance, training, and capacity building India aimed at modernizing and processing industry by manufacturing to micro food processing enterprises, strengthening the entire food processing specific categories of food products helping them improve their quality, value chain, from farm to market having high potential for growth in output hygiene, and market reach • Implementation period - 2016-2017 to and value addition • Implementation period - 2020-2021 to 2025-2026 • Implementation period - 2021-2022 to 2024-2025 • Expected Budget outlay - INR 11,095 Crore 2026-2027 • Budget outlay - INR 10,000 Crore • Employment benefit - ~5.4L people by year • Budget outlay - INR 10,900 Crore • Loan sanctioned - ~48,454 (till date) 2026 • Employment benefit - ~2.5L people by year • Aim is to - • Farmers benefitted - ~28.4L farmers by 2027 year 2026 • Encourage the formalization and growth of • Aim is to - small-scale food processing businesses • Aim is to - • Foster the emergence of international • Create employment opportunities, • Benefit farmers by increasing their income, leaders in food manufacturing reducing post-harvest losses, and • Promote local food products • Boost the recognition of Indian food enhancing the overall competitiveness of • Contribute to the overall development of product brands the food processing sector the food processing sector in India • Enhance non-farm employment prospects, • The key objectives and components of secure profitable pricing for agricultural PMKSY include Infrastructure Development, yields, and elevate farmers' income levels Value Addition, Quality Control, Supply chain management, Promotion of Agro-Clusters Source(s): Government of India, MOFPI, 1Lattice analysis © 1Lattice | 34 Agenda Executive summary Food & Grocery: Indian market outlook Market segmentation Growth drivers & barriers Recent trends & Government initiatives Notable investments & opportunities Food and Grocery market index of India The way ahead Recent investments Notable investments across food and grocery space in 2022-2023 BigBasket raised US$ 200M Coca-Cola India acquired a in new funding that has 15% stake in Thrive , a Burger chain boosted the valuation of Mumbai-based online food Good Flippin' the Tata ordering & delivery platform Burger Singh has Burgers has Digital-owned Curefoods , a multi-brand Licious raised US$ raised US$ 300M in raised US$ 4M in e-grocer to US$ 3.2B cloud kitchen chain in India, 150M for its fresh a Series A funding a fresh round of raised US$ 36.6M in a animal protein Reliance acquires Metro round led by Negen funding via combined equity and debt e-commerce AG's India business for US$ Capital, Lets Tanglin Venture funding platform 28.5B Ventures & others Partners JULY DEC APR MAY MAR 2022 2022 2022 2022 2022 2023 2023 2023 2023 JUNE JAN MAY MAR JUL AUG Swiggy , India’s top Jimmy’s cocktails Cafe chain EazyDiner raised Food processing Zepto raised US$ food delivery raised US$ 1.8 M Chaayos raised US$ 4.8M in a industry has made 200M in fresh startup, raised US$ through Roots US$ 53M in Series C strategic funding an investment of funding from 700M , just six venture funding led by round from DMI US$ 74.28B under U.S-based months after Alpha Wave Finance’s Sparkle the investment firms Marico expanded securing US$ 1.25B Ventures Fund production-linked StepStone Group its footprint in the incentive (PLI) and Goodwater healthy foods scheme Capital segment, picked up 54% stake in D2C brand true elements Source(s): Tracxn, Economic times, Media reports, Secondary research, 1Lattice analysis © 1Lattice | 36 Recent investments Notable investments across food and grocery space in 2022-2023 Indian tea cafe chain startup Chaayos Exclusive I BigBasket raises $200 million Marico Expands Footprint In Healthy Foods from Tata Digital, others; valuation hits Segment, Picks Up 54% Stake In D2C Brand raises $53 million for business $3.2 billion True Elements expansion Jimmy’s Cocktails maker expands product range, raises $1.3 million Gurugram: Radiohead Brands, makers of Jimmy’s Cocktails and Sparkling Mixers, has introduced an energy drink ‘Hustle’ Energy drink, with the aim to disrupt the Energy Drinks category. Food processing industry invests ₹7,427 crore COCA-COLA INDIA BUYS 15% STAKE IN FOOD Swiggy turns decacorn, raises $700 under PLI scheme so far: Govt DELIVERY STARTUP THRIVE mn from Invesco, others Coca-Cola India's investment in Thrive marks the FMCG's first startup Zepto raises $200 million at $1.4 billion investment in India, offering Thrive a headstart to challenge Zomato and Swiggy's duopoly in the food ordering business valuation, becomes first Indian unicorn in nearly a year Source(s): Economic times, Media reports, Secondary research, 1Lattice analysis © 1Lattice | 37 Opportunities for other sectors Growth of the food and grocery sector holds the potential to create significant opportunities and challenges across a wide range of industries Real estate Logistics Technology Education Financial & Transportation & Software & Training services • Opportunities • Growing need for • Since F&G sector • With the growth of • Financial created for real efficient benefits from F&G industry, institutions estate developers, transportation, & technology training and providing loans property owners, logistics facilities solutions for education and capital to and investors who for higher inventory programs related businesses in the strategically align customer management, to food safety, F&G sector may their investments satisfaction with supply chain culinary skills, & see increased with this sector the expansion of optimization, & nutrition may see activity as the food & grocery customer higher enrollment businesses seek • Growth in F&G sector engagement & demand for their funding for industry leads to services expansion rise in retail space • Logistics • Technology & demand for companies to see software • People may want • More investment warehousing, cold a surge in companies that to learn and serve opportunities for storage, demand for their provide these further leading to investors available restaurants , etc. services solutions can growth in with the growth of thrive and a good hospitality & industry opportunity for service sector them is created Source(s): Media articles, secondary research, 1Lattice analysis © 1Lattice | 38 Agenda Executive summary Food & Grocery: Indian market outlook Market segmentation Growth drivers & barriers Recent trends & Government initiatives Notable investments & opportunities Food and Grocery market index of India The way ahead Market index methodology Market index methodology Objective Methodology for quarter-wise and annual data • To assess the industry's • Prepared a list of leading • Evaluated quarter-wise • Calculation of the market overall health by closely 25 listed companies in and annual financial index based on revenue, monitoring the performance the food and grocery indicators including: EBITDA and PAT of the 25 of 25 major food companies segment in India - Revenue listed companies in India - PAT • Examined the company - EBITDA wise quarterly growth rates of revenue and PAT List of 25 key companies Note(s): Only the food segment financial data for all the companies is included in the index; PAT- profit after tax, EBITDA- earnings before interest tax depreciation and amortization © 1Lattice | 40 Source(s): 1Lattice analysis Annual revenue, EBITDA & PAT A good recovery has been observed in food and grocery segment, post Covid; An increase of ~15% observed in FY23 in the overall revenue of top 25 companies Annual revenue saw a sharp growth of ~25% in EBITDA YoY growth rate grew steadily from ~10% to FY21-22 ; growth in FY22-23 slowed down but was still ~18% in FY21-23; PAT YoY growth rate became 2x positive (~15%) from ~10% to ~20% Annual revenue of top 25 listed F&G companies in Annual EBITDA and PAT of top 25 listed F&G Annual EBITDA and PAT of top 25 listed F&G India (INR B) companies in India companies in India (INR B) (INR B) YoY CAGR ~14% growth CAGR ~ 15% 2,342 15% 236 YoY growth 2,039 25% 200 190 181 1,634 158 144 FY2021 FY2022 FY2023 FY2021 FY2022 FY2023 Annual revenue EBITDA PAT Note(s): CAGR calculated from FY21-FY23 © 1Lattice | 41 Source(s): Money control, Company annual reports, 1Lattice analysis Quarterly revenue, EBITDA & PAT While comparing FY23Q1 and FY24Q1, a growth in quarterly revenue (~6%), Profit after Tax (~13%) and EBITDA (~11%) is seen Quarter-wise revenue, EBITDA & PAT of 25 listed food and grocery companies (INR B) 250 After the sharp increase due to the 610 festival season from Q2 to Q3 in FY23, 602 FY23Q4 saw an overall decline as sales decreased 600 594 200 592 590 583 150 580 570 100 561 63 60 560 55 54 50 49 47 550 43 40 38 540 - FY23Q1 FY23Q2 FY23Q3 FY23Q4 FY24Q1 Quarterly EBITDA Quarterly PAT Quarterly revenue Source(s): Money control, Company annual reports, 1Lattice analysis © 1Lattice | 42 Quarterly revenue for 25 companies While the majority of companies saw a decline in revenue during FY23Q4, Balampur Chini Mills stood out with a substantial 52% increase in its quarterly revenue Quarter on Quarter growth in revenue for the leading 25 food companies in India Company Company FY23Q2 FY23Q3 FY23Q4 FY24Q1 FY23Q2 FY23Q3 FY23Q4 FY24Q1 name name KRBL 7% 16% -17% 10% Venky's -20% 8% 1% -6% -6% Hindustan Unilever Bikaji 38% -12% -9% 4% 4% -1% 3% 0% 0% Limited Marico -3% -1% -10% 8% Brittania 19% -6% -4% 2% 2% 2% I TC 10% - 1% 2% 4% 4% Nestle 14% -7% -13% -4% -4% Tata consumer 3% 1% 1% 1% 4% Sapphire Foods 3% 6% -5% 15% 15% Dabur 4% 1% 1% 1% -16% 21% Jubilant foodworks 4% 2% -5% 5% 5% LT foods 1% -17% 5% 3% Devyani 6% 4% -4% 14% 14% Mrs. Bectors 15% 6% -6% 8% International Restaurants Prataap snacks 23% -5% 5% -3% 9% 0% -1% 16% 16% brand Asia Adani Wilmar -1% -11% -12% -8% Barbeque Nation -1% 5% -16% 16% 16% Patanjali foods 18% -7% -1% -1% GRM overseas -17% 28% 9% -17% -17% Dhampur -27% -8% -22% 17% Sugar Mills Zomato 4% 1% 1% 18% 18% Balrampur 3% -12% -52% -7% DMart 6% 9% -9% 12% 12% Chini Mills High Low Source(s): Money control, Company annual reports, 1Lattice analysis © 1Lattice | 43 Quarterly PAT for 25 companies Sapphire Foods, Prataap Snacks,& Balrampur Chini Mills experienced substantial PAT growth from FY23Q3 to FY23Q4, while BBQ Nation saw a significant decline Quarter on Quarter growth in PAT for the leading 25 food companies in India Company Company FY23Q2 FY23Q3 FY23Q4 FY24Q1 FY23Q2 FY23Q3 FY23Q4 FY24Q1 name name Venky's KRBL 30% -4% -43% 65% -142% -180% 53% -23% Hindustan Unilever Bikaji 143% -32% 24% 22% -15% 36% -4% -19% Limited Marico -14% -24% -20% 50% Brittania 53% 56% -27% -21% ITC 31% 8% 3% -4% 30% -6% 17% -5% Nestle Tata consumer -1% 3% 6% 14% Sapphire Foods -30% 31% 330% -81% 13% 0% -41% 62% Dabur Jubilant Foodworks 18% -26% -46% 58% LT foods 10% -8% 93% -41% Devyani -11% 10% -21% -32% Mrs. Bectors 72% 33% 2% 24% International Prataap snacks Restaurants -136% 14% 532% -38% -42% -16% 119% -10% brand Asia Adani Wilmar -83% 686% -63% -163% Barbeque Nation -50% -56% -615% -36% Patanjali foods -53% 140% -2% -67% GRM overseas -42% 57% -46% 77% Dhampur -70% 331% 26% -22% Sugar Mills Zomato -108% 426% 195% 52% Balrampur -369% -242% 465% -72% DMart -7% -12% -21% 38% Chini Mills High Low Source(s): Money control, Company annual reports, 1Lattice analysis © 1Lattice | 44 Agenda Executive summary Food & Grocery: Indian market outlook Market segmentation Growth drivers & barriers Recent trends & Government initiatives Notable investments & opportunities Food and Grocery market index of India The way ahead Future outlook Future of the F&G sector to be shaped by technology, sustainability, & consumer preferences along with the companies embracing these upcoming trends [1/2] Way ahead in the food & grocery sector in India Automation & robotics Plant-based & alternatives Micro-retail Food processing plants to Driven by concerns about Smaller and more increasingly employ animal welfare, health, and localized retail formats like automation and robotics sustainability, shift towards mobile and pop-up stores to streamline production, plant-based & lab-grown to emerge, targeting reduce labor costs, meat alternatives specific demographics enhance food safety & for and neighborhoods smart packaging Circular economy E-commerce dominance Personalization Food processing Online grocery shopping to Retailers to leverage data companies to adopt grow along with and AI aiming to provide circular economy innovations like highly personalized principles , aiming to automated fulfillment shopping experiences, minimize waste, optimize centers and rapid delivery from product resource use, and reduce services recommendations to environmental impact customized meal planning Source(s): Company website, Media reports, 1Lattice analysis © 1Lattice | 46 Future outlook Future of the F&G sector to be shaped by technology, sustainability, & consumer preferences along with the companies embracing these upcoming trends [2/2] Way ahead in the food & grocery sector in India Cloud kitchen concept Blockchain technology Carbon neutrality Cost-effective concepts Provide consumers with Companies have started like cloud kitchen to real-time access to committing to reduce their proliferate which information about the carbon footprint and exclusively prepare food origin and journey of their achieve carbon neutrality , for delivery or takeout food products while both in food production ensuring safety and and distribution transparency Hybrid dining experience Zero waste initiatives Combination of in-person Food retail and services dining with virtual businesses to adopt elements , such as zero-waste practices , augmented reality menus from reducing single-use or live-streamed plastics to repurposing restaurant kitchen food waste into new products Source(s): Media articles, Industry reports, 1Lattice analysis © 1Lattice | 47 We are here for you Let us know how we can meet your business requirement? Connect now Ashish Dhir Executive Vice President Vaishnav Kumar Rai 1Lattice Manager – Corporate Communications E: ashish.dhir@1lattice.com E: communications@1lattice.com M: +91 962 522 6702 M: +91 782 794 4925 Gurugram Bengaluru New Delhi Mumbai www.1lattice.com Disclaimer: This material has been prepared by 1Lattice, which is the trade name of Lattice Technologies Private Limited (“1Lattice”, “we” or “our”) with the intent to showcase our capability and disseminate learnings to potential partners/clients. This material can be referred to by the readers on the internet but should be referenced to 1Lattice, if reused or adapted in any form, or medium and on any forum. The frameworks, approaches, tools, analysis and opinions are solely 1Lattice’s intellectual property and are a combination of the collection of the best data we could find publicly, and the 1Lattice team’s own experiences and observations. Any information provided herein is only for informational purposes and you are advised to perform an independent analysis of the same before making any decision based on such information. The information does not constitute any business advice or guidance and is to be construed as a general summary based upon the publicly available information and our interpretation of the same using our resources. For this material, we may have relied upon different sources of information which may be primary sources, publicly available information, and relevant information available with us. We make no representation or warranty, expressed or implied, that such information is accurate or complete, and nothing contained here can be construed as definitive predictions or forecasts. Before reading further, the Recipient expressly agrees that this might not address any and all risks and challenges facing the Recipient, its business, and the markets within which it operates, nor all possible market conditions. Any use of the information provided herein by the viewer shall be at the sole risk of the viewer and 1Lattice or its business partners, affiliates, agents, officers or employees shall not be liable for any unintended or adverse effect or outcome from the use of such information by the reader. 1Lattice does not have any duty to update or supplement any information in this document. 1Lattice shall not be responsible for any business or commercial loss sustained by any person who relies on any information provided herein. Any and all logos of companies used in the information provided herein have been published for information purposes only and 1Lattice does not hold any liability in connection therewith. 1Lattice We enable better decision making. Technology-backed business support that helps you ENABLE BETTER 200+ 30% annual engagements faster to outcomes DECISIONS Deep on-ground insights that you can act on 8 600+ practices years domain expertise 4 offices, deep experience across geographies – India, the USA, Europe, MEA, and SEA regions 130+ 98%+ team members accuracy One-ness of data and people networks to harness the collective power of data, network, and technology 100+ 2.5M towns & cities panel members Multi-faceted teams offering a stack of consulting, advisory, and research services 15+ 40:60 languages covered she/he ratio The team at appreciates your time and support THANK YOU Enabling Better Decisions. New Delhi Gurugram Mumbai Bengaluru Unit 4, Ground Floor, Tower A, 4th Floor, DLF 102, First floor, 2734, Fourth floor, Uppal Plaza M6, District Centre Court, DLF Phase Workafella, AK Estate, HSR Layout, Sector 1, Centre, Jasola -110 025 5, Sector 42, Goregaon West, 27th Main, 16th Cross, New Delhi, India Gurugram-122 002 Mumbai - 400 062 Bengaluru - 560 102 Haryana, India Maharashtra, India Karnataka, India Registered address: Unit 4, Ground Floor, Uppal Plaza M6, District Centre, Jasola, New Delhi -110025