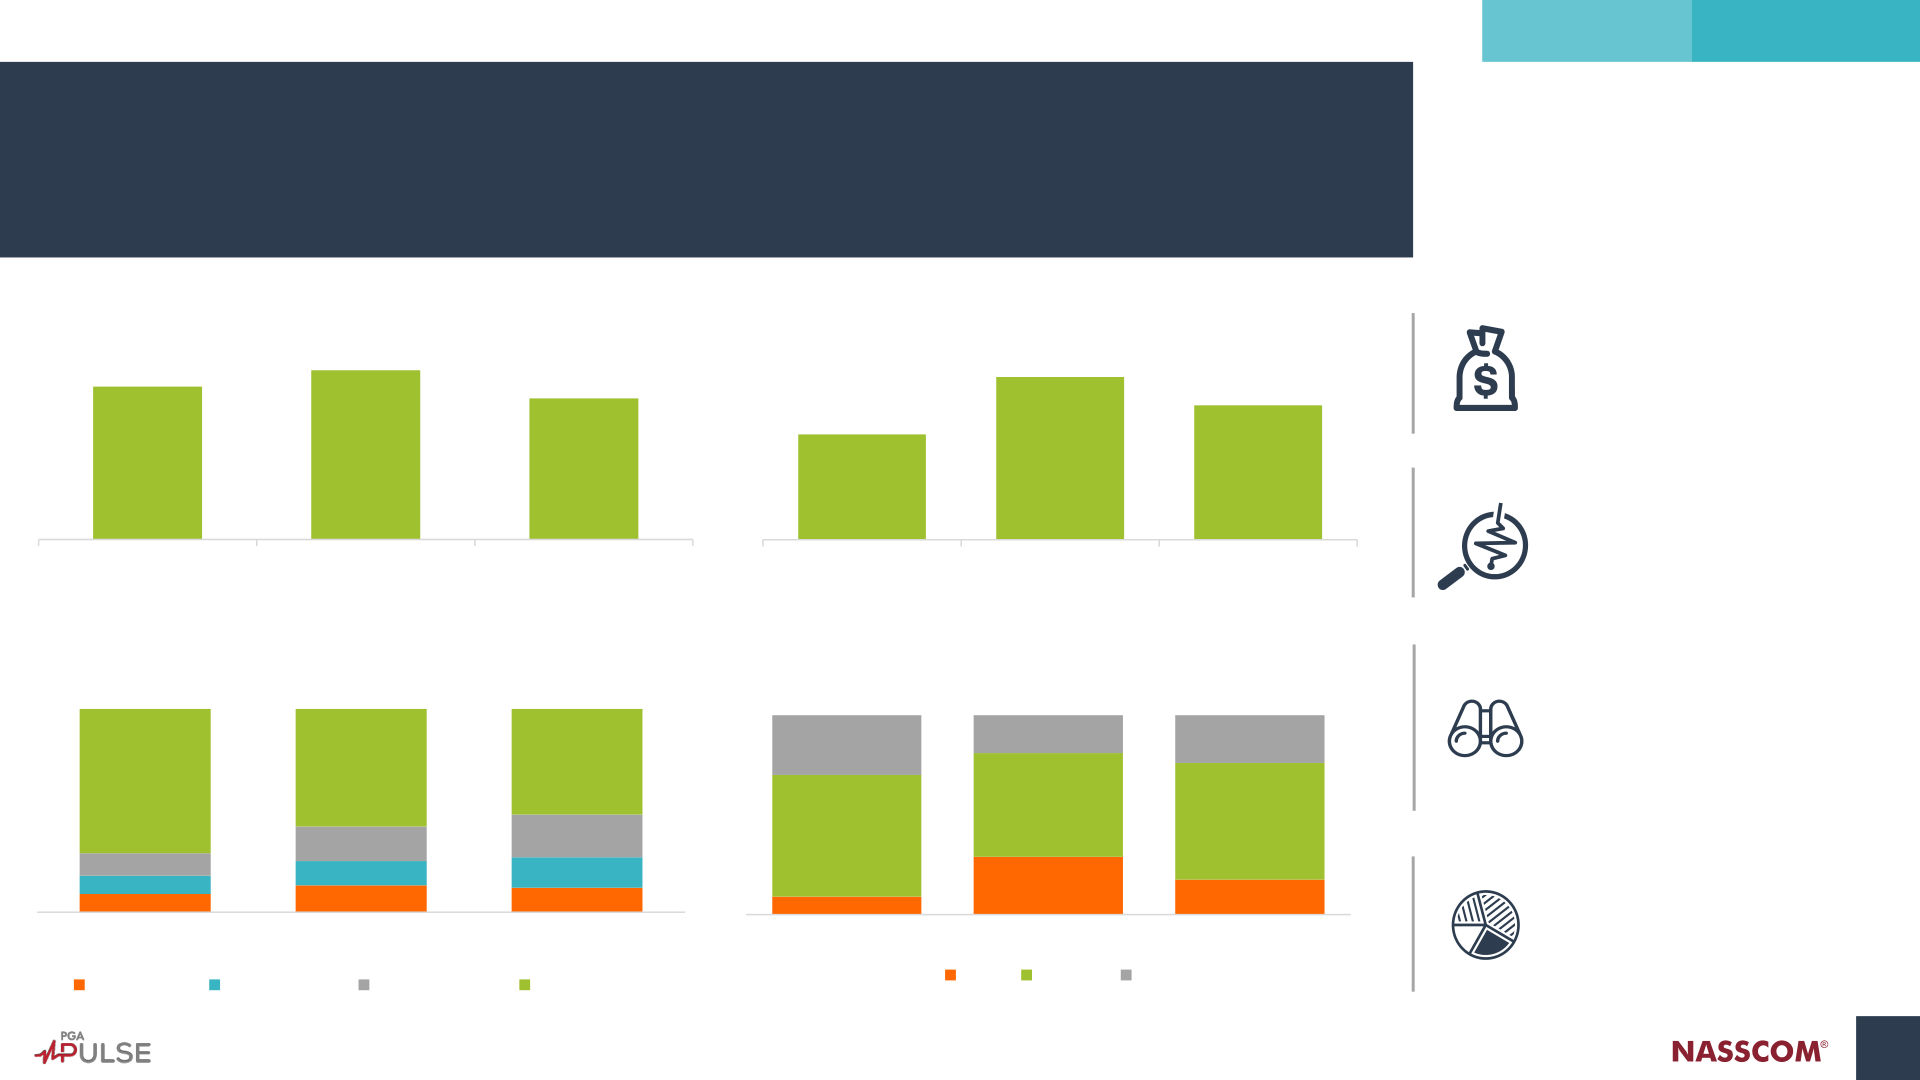
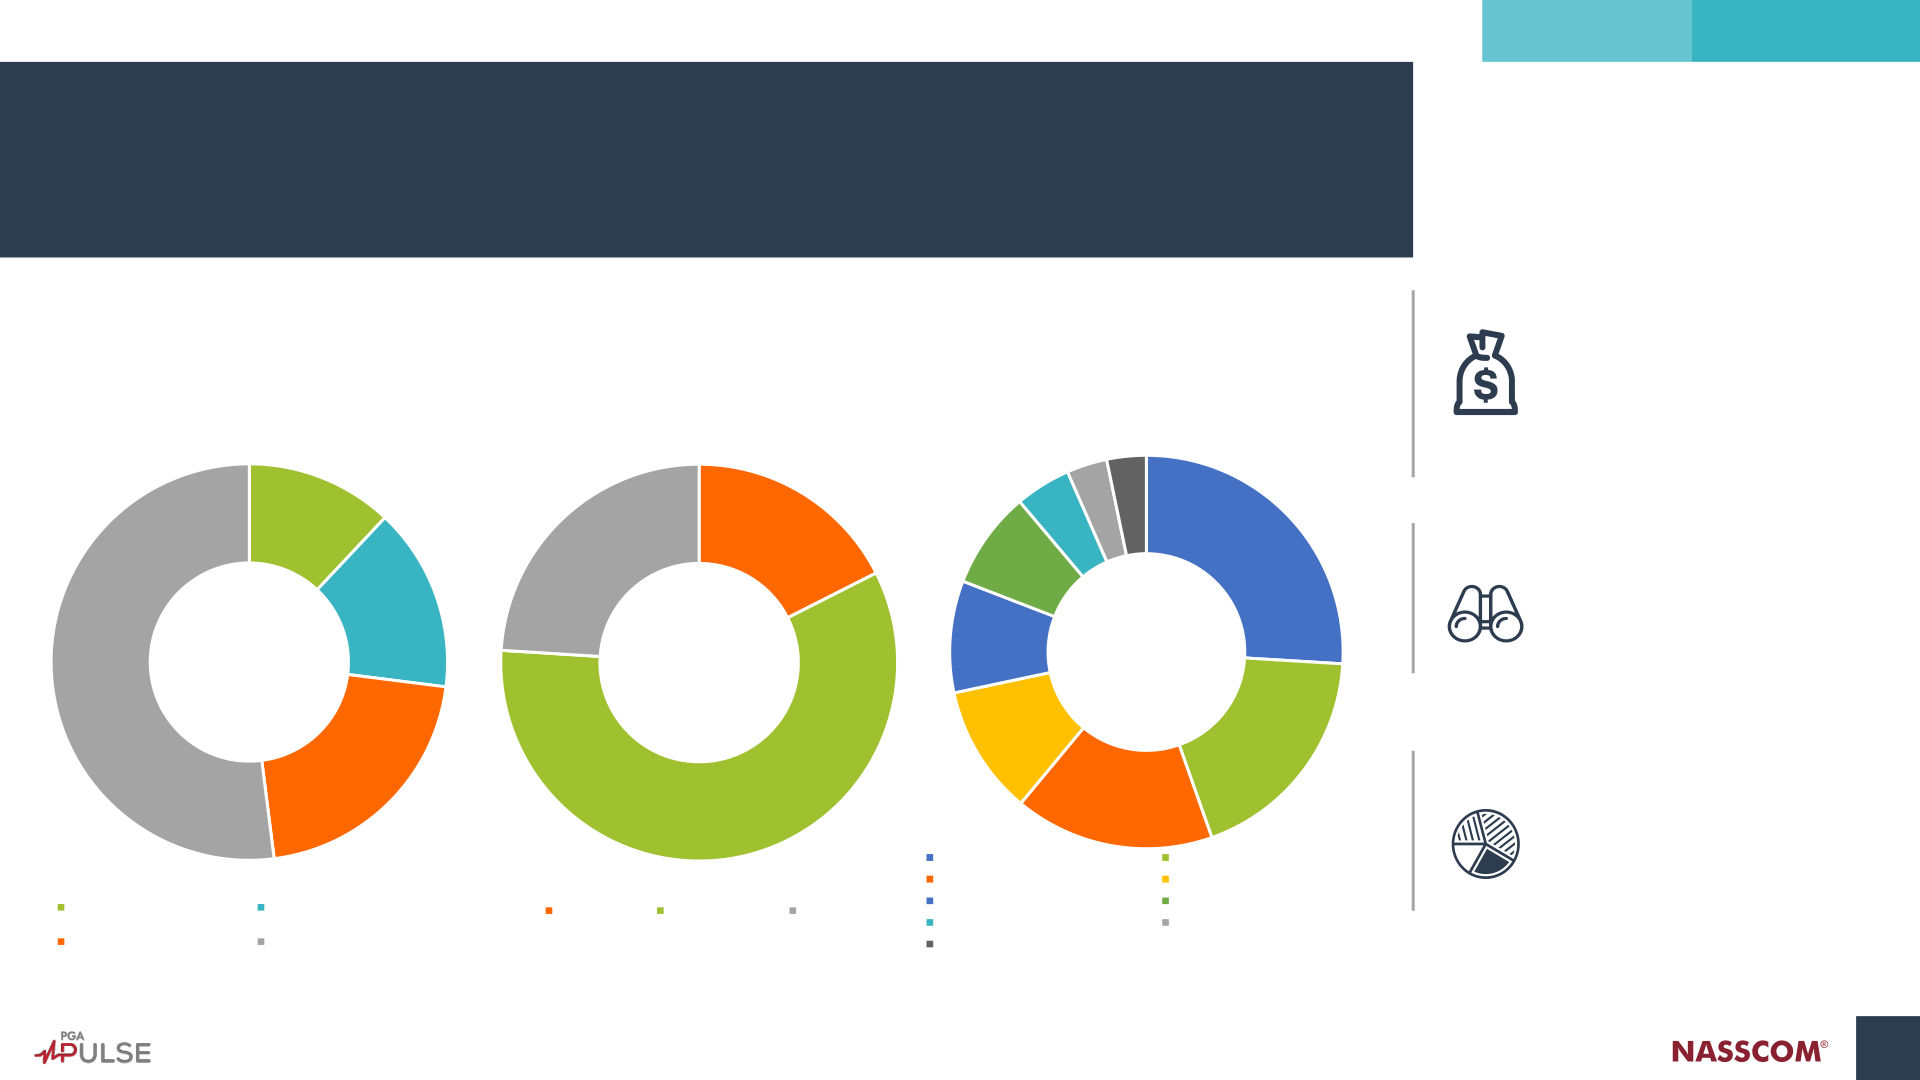
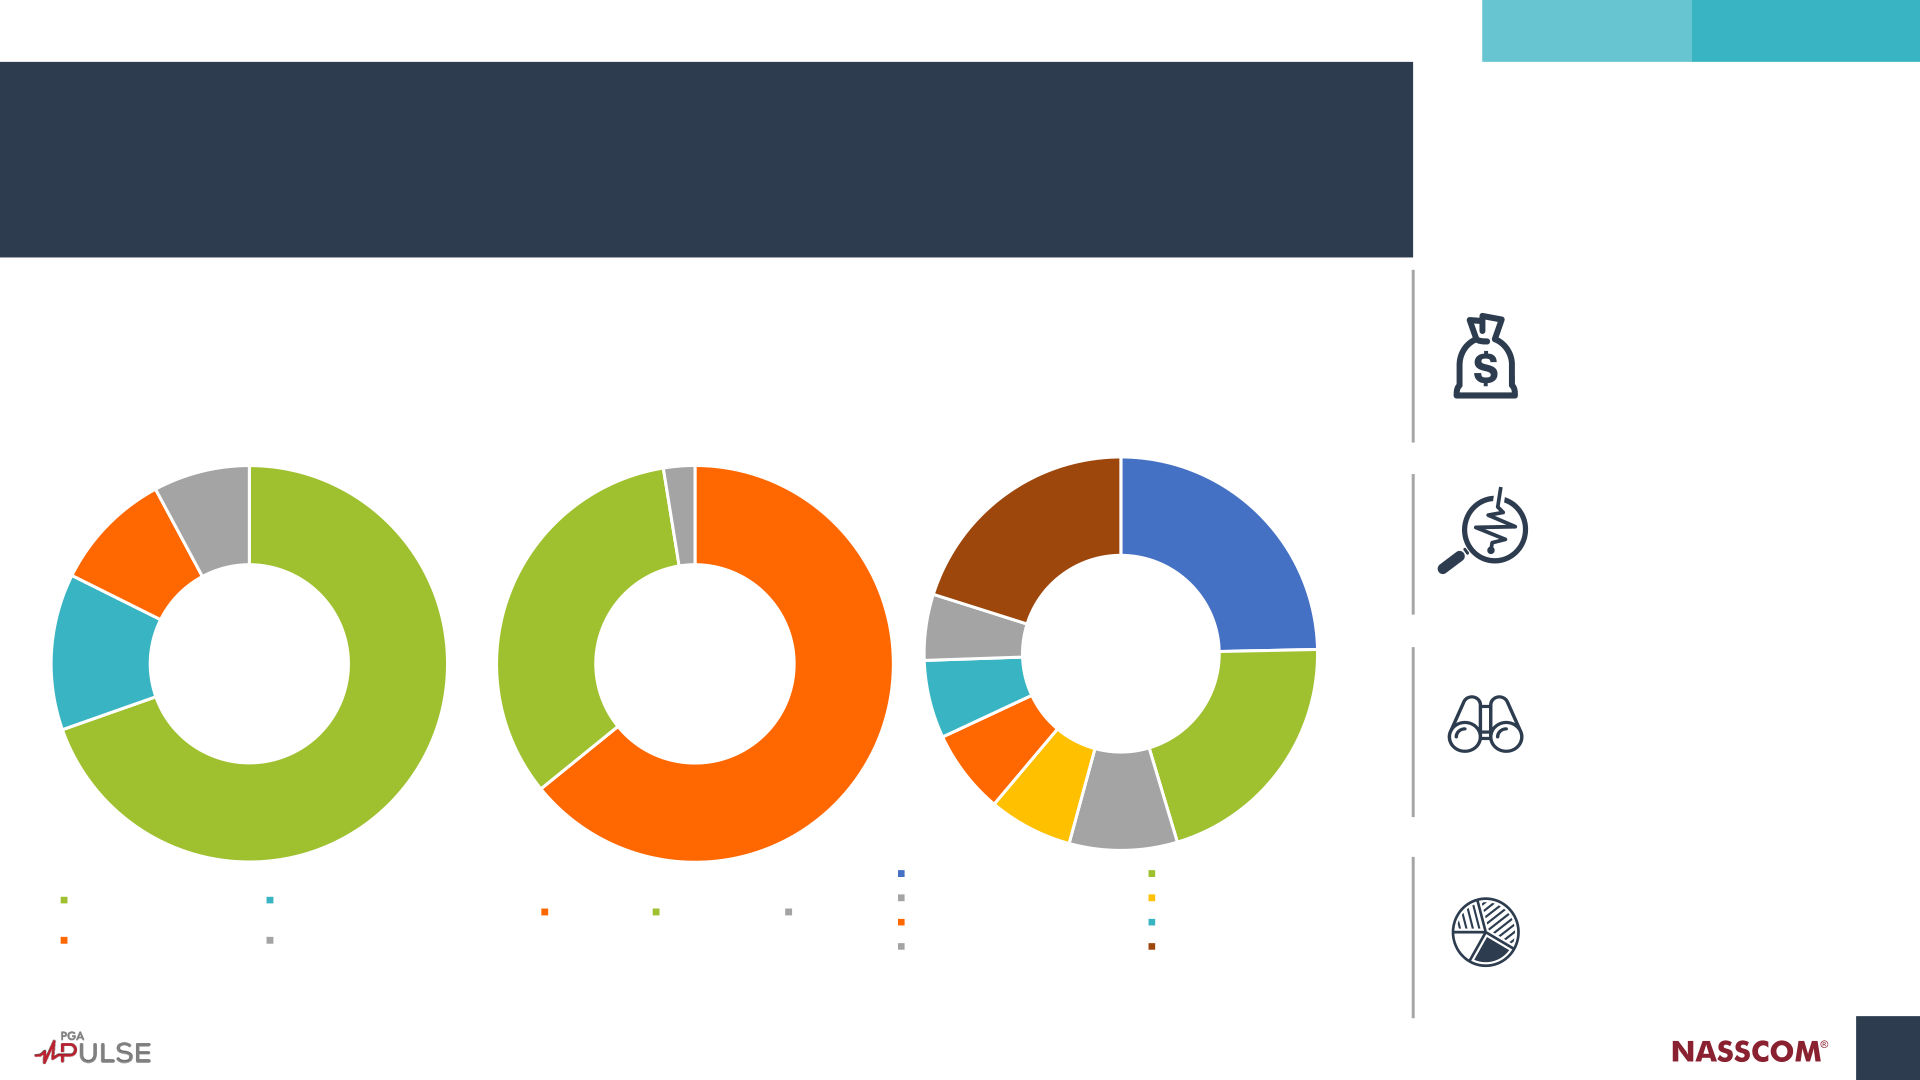
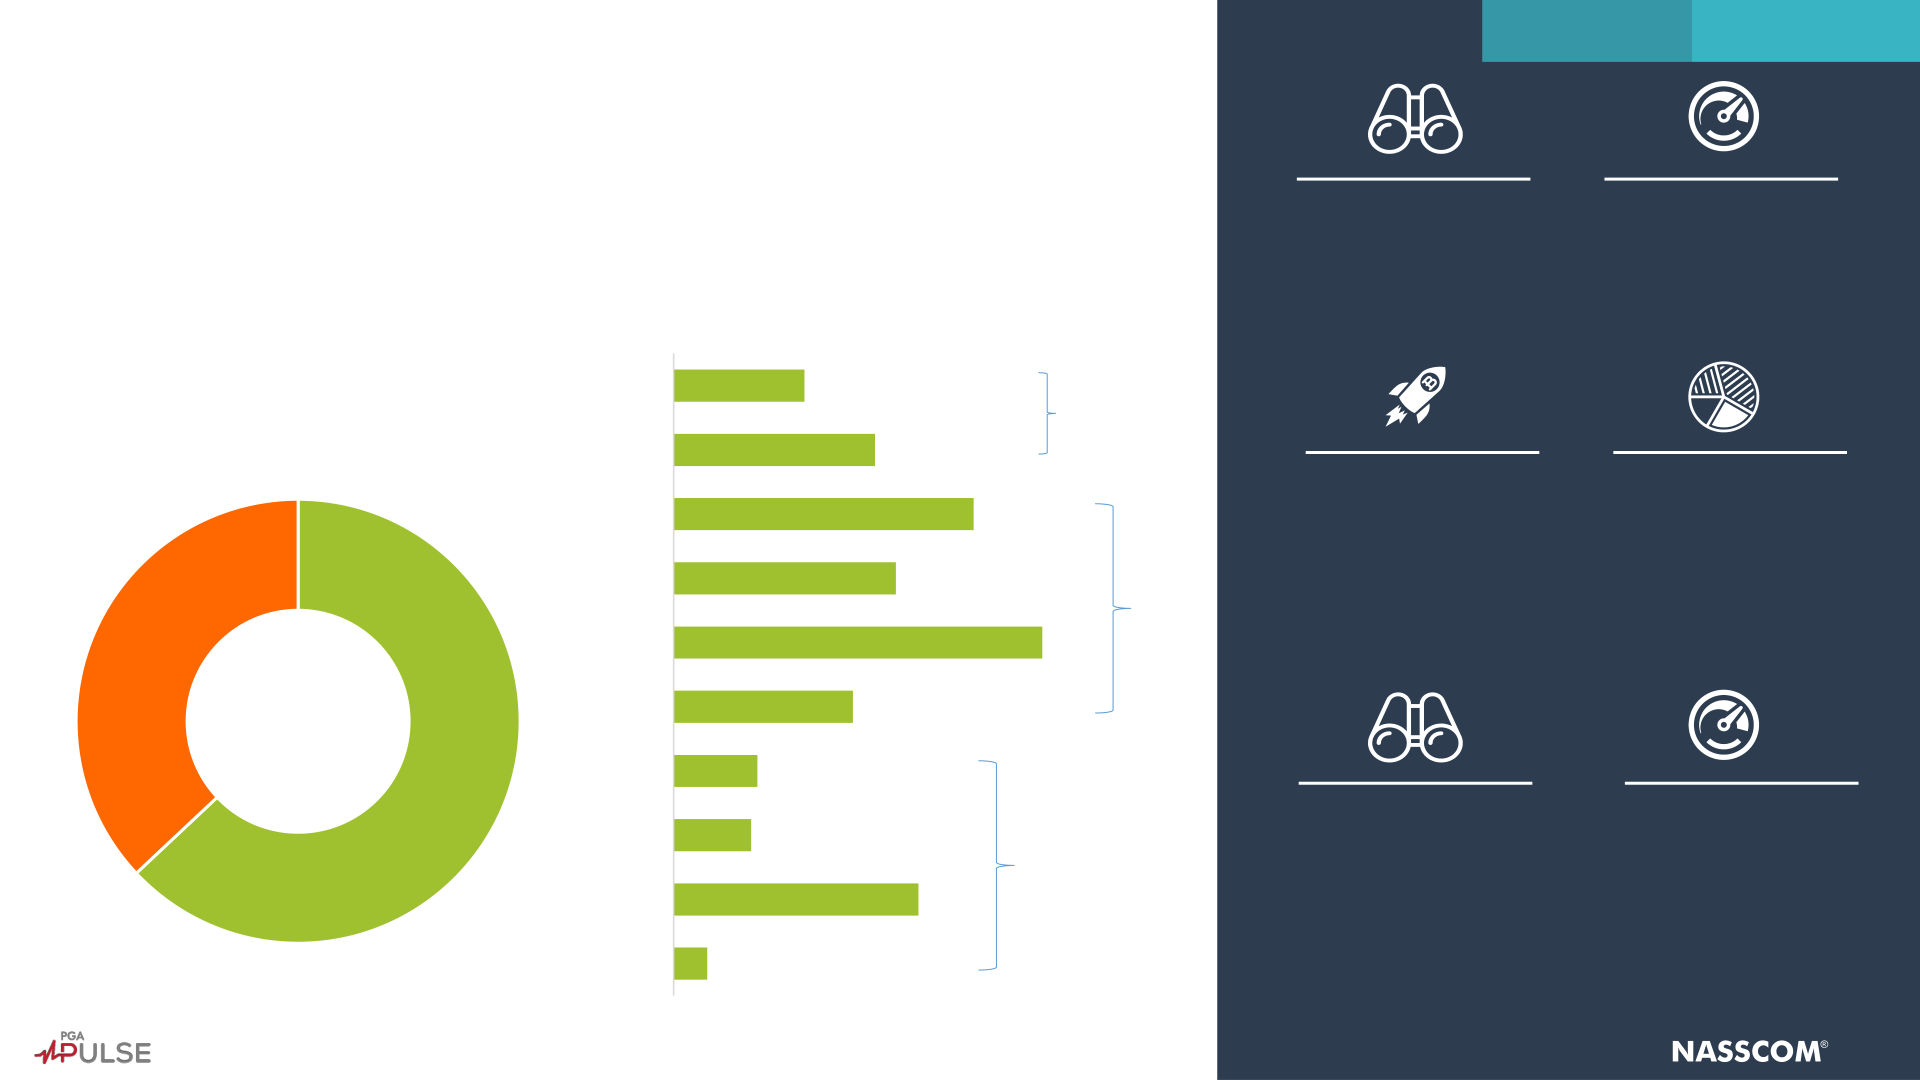
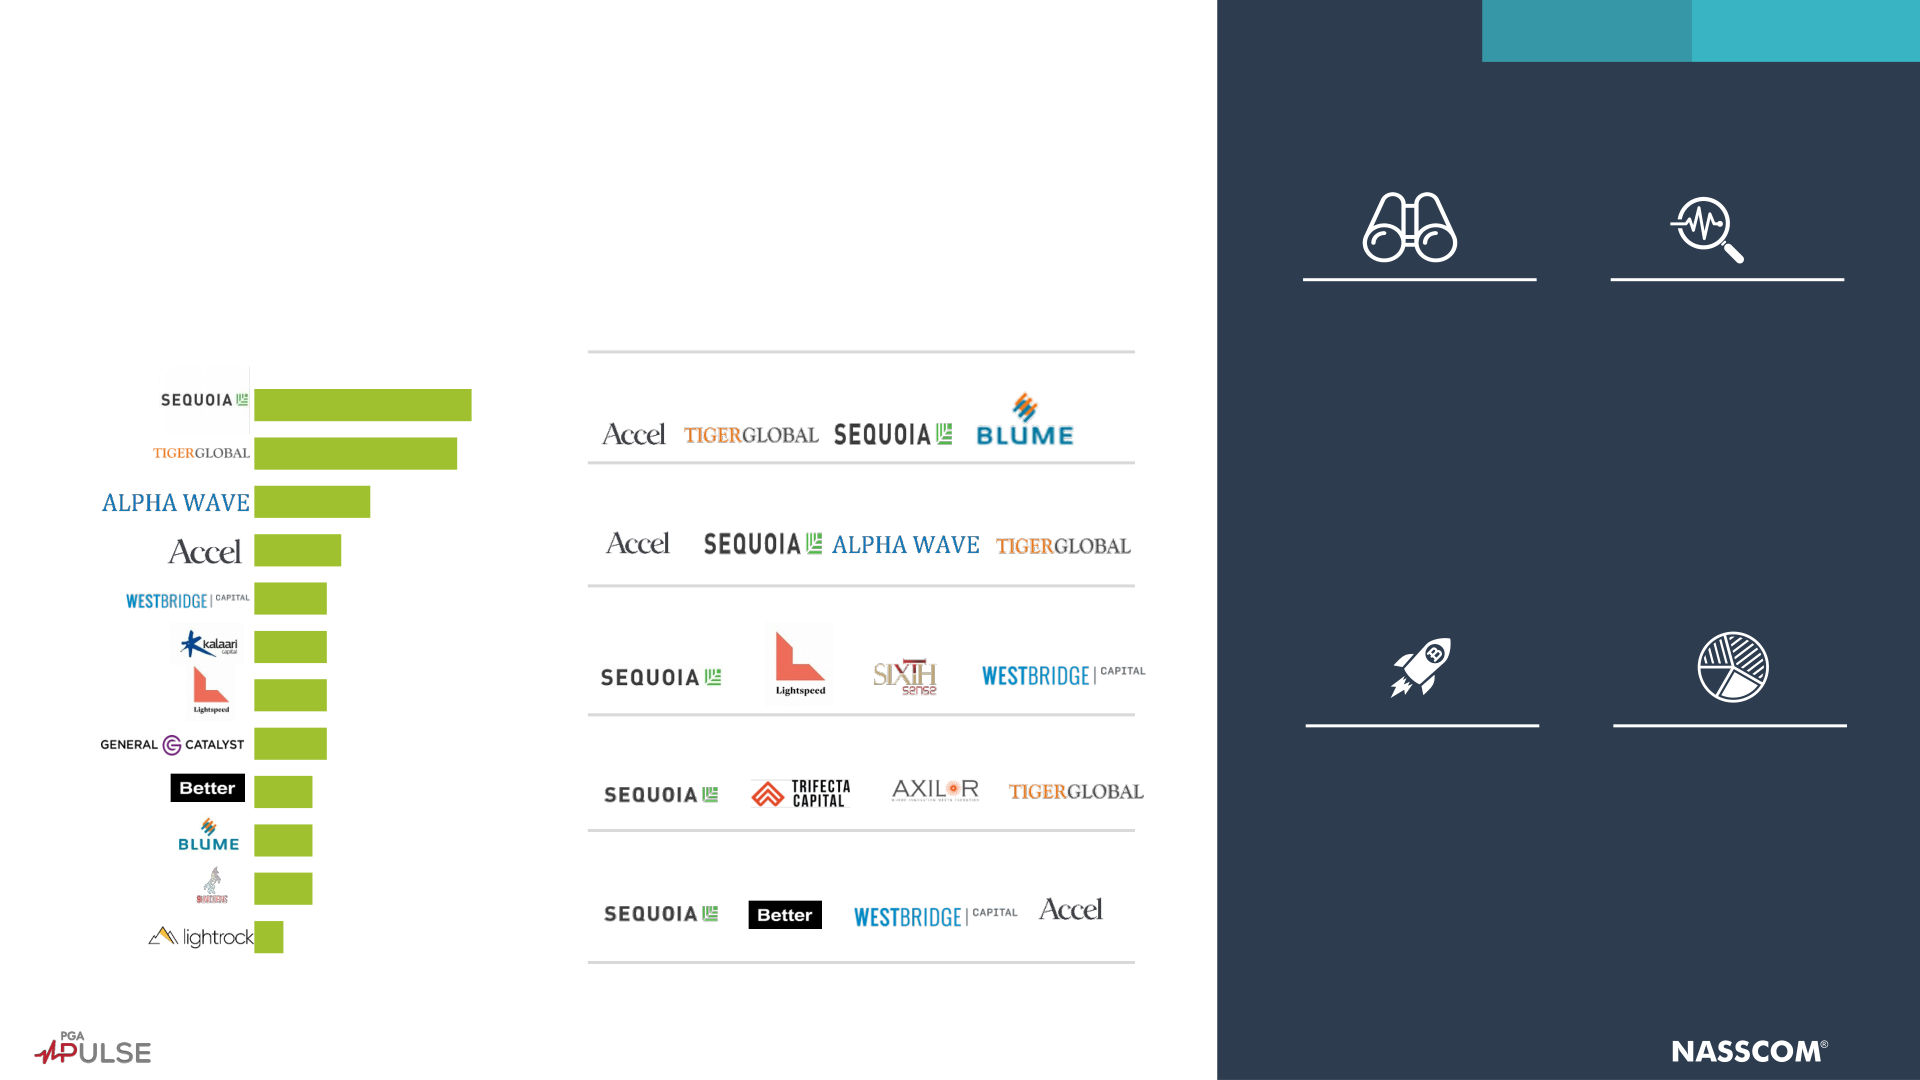
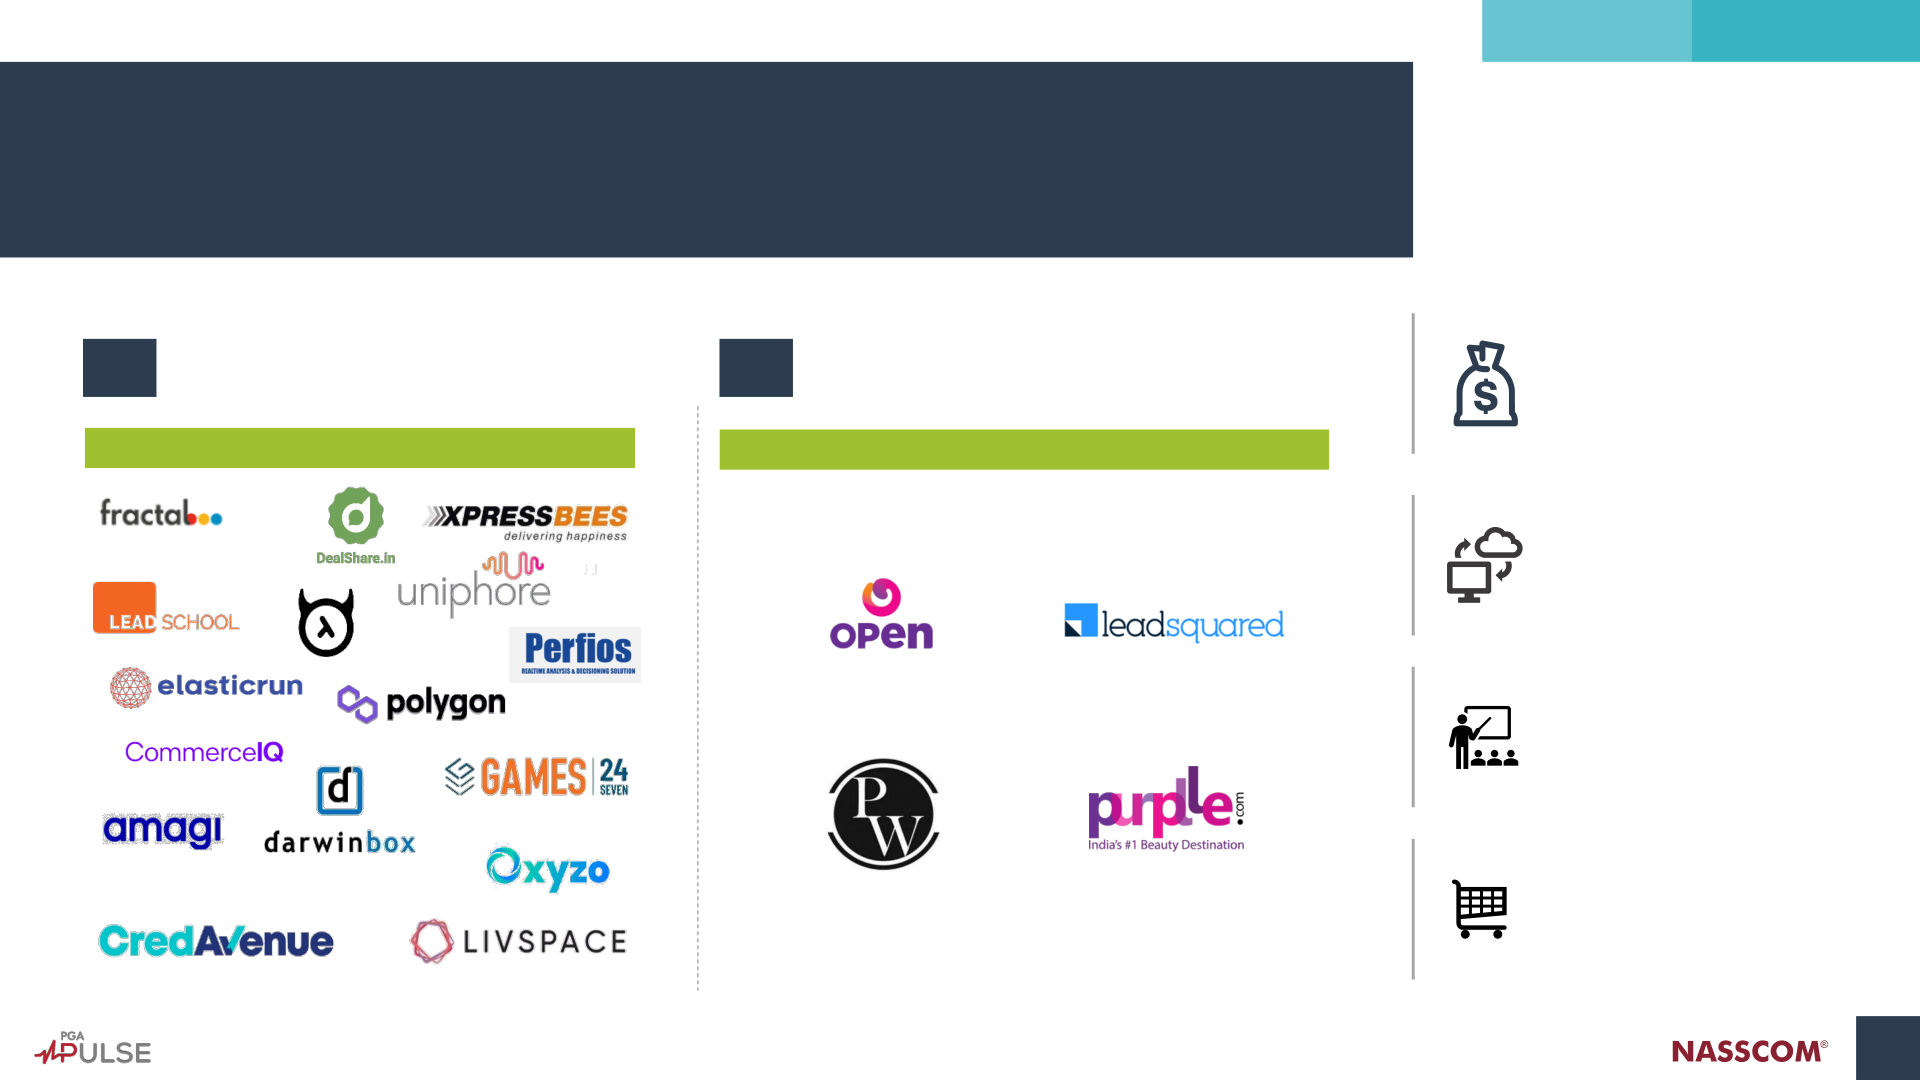
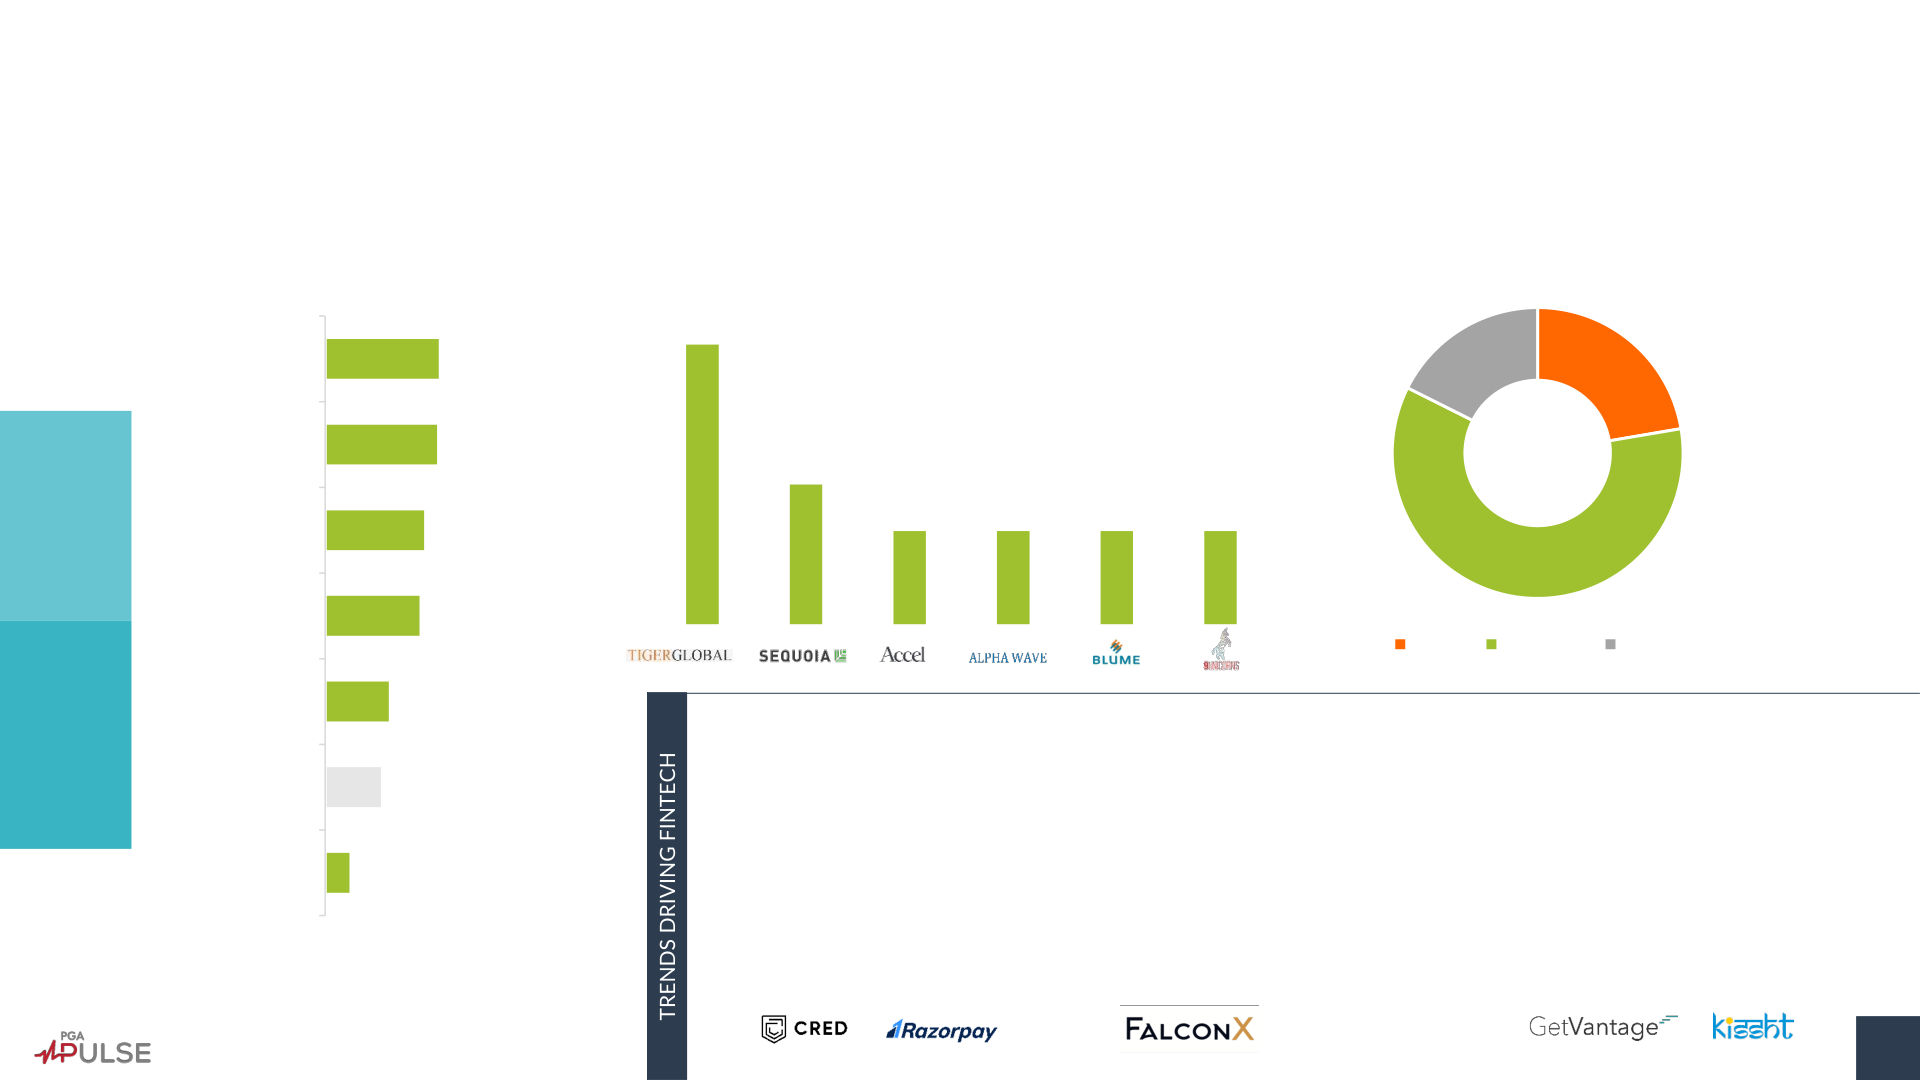
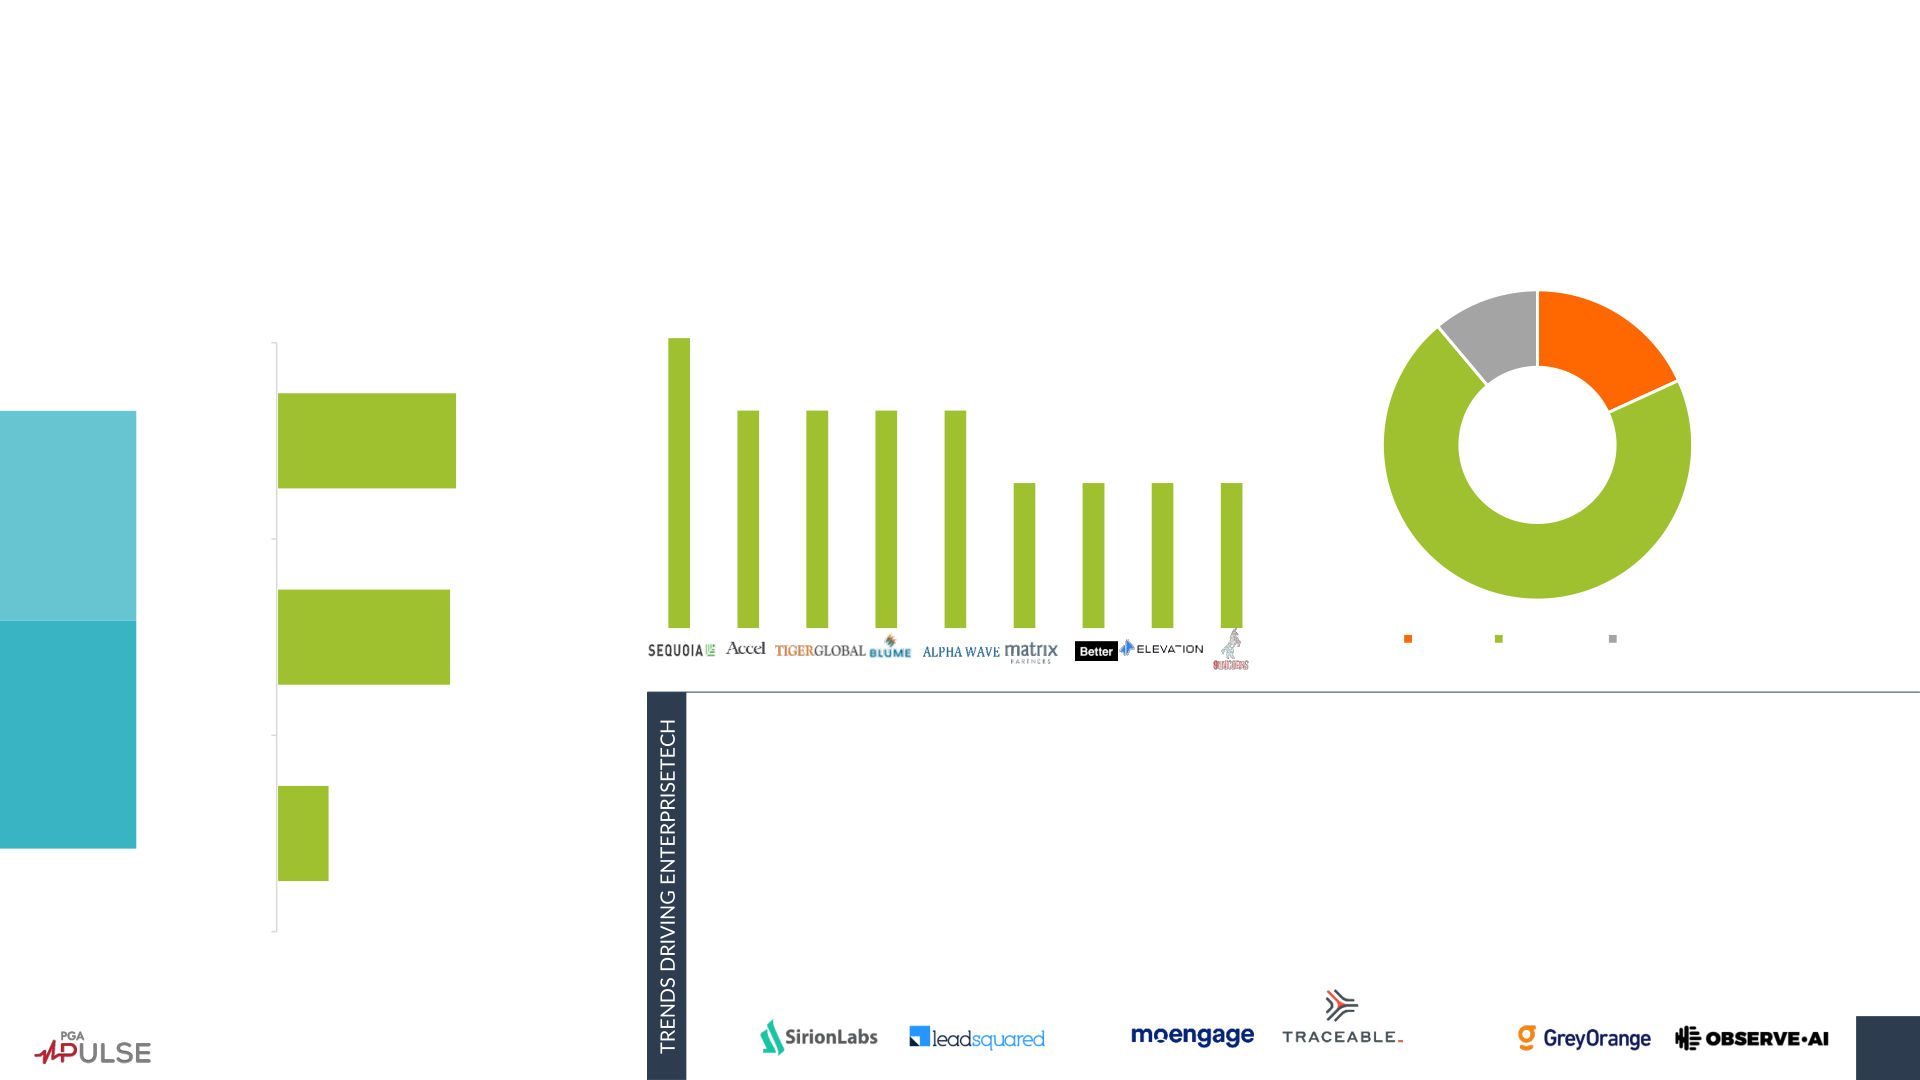
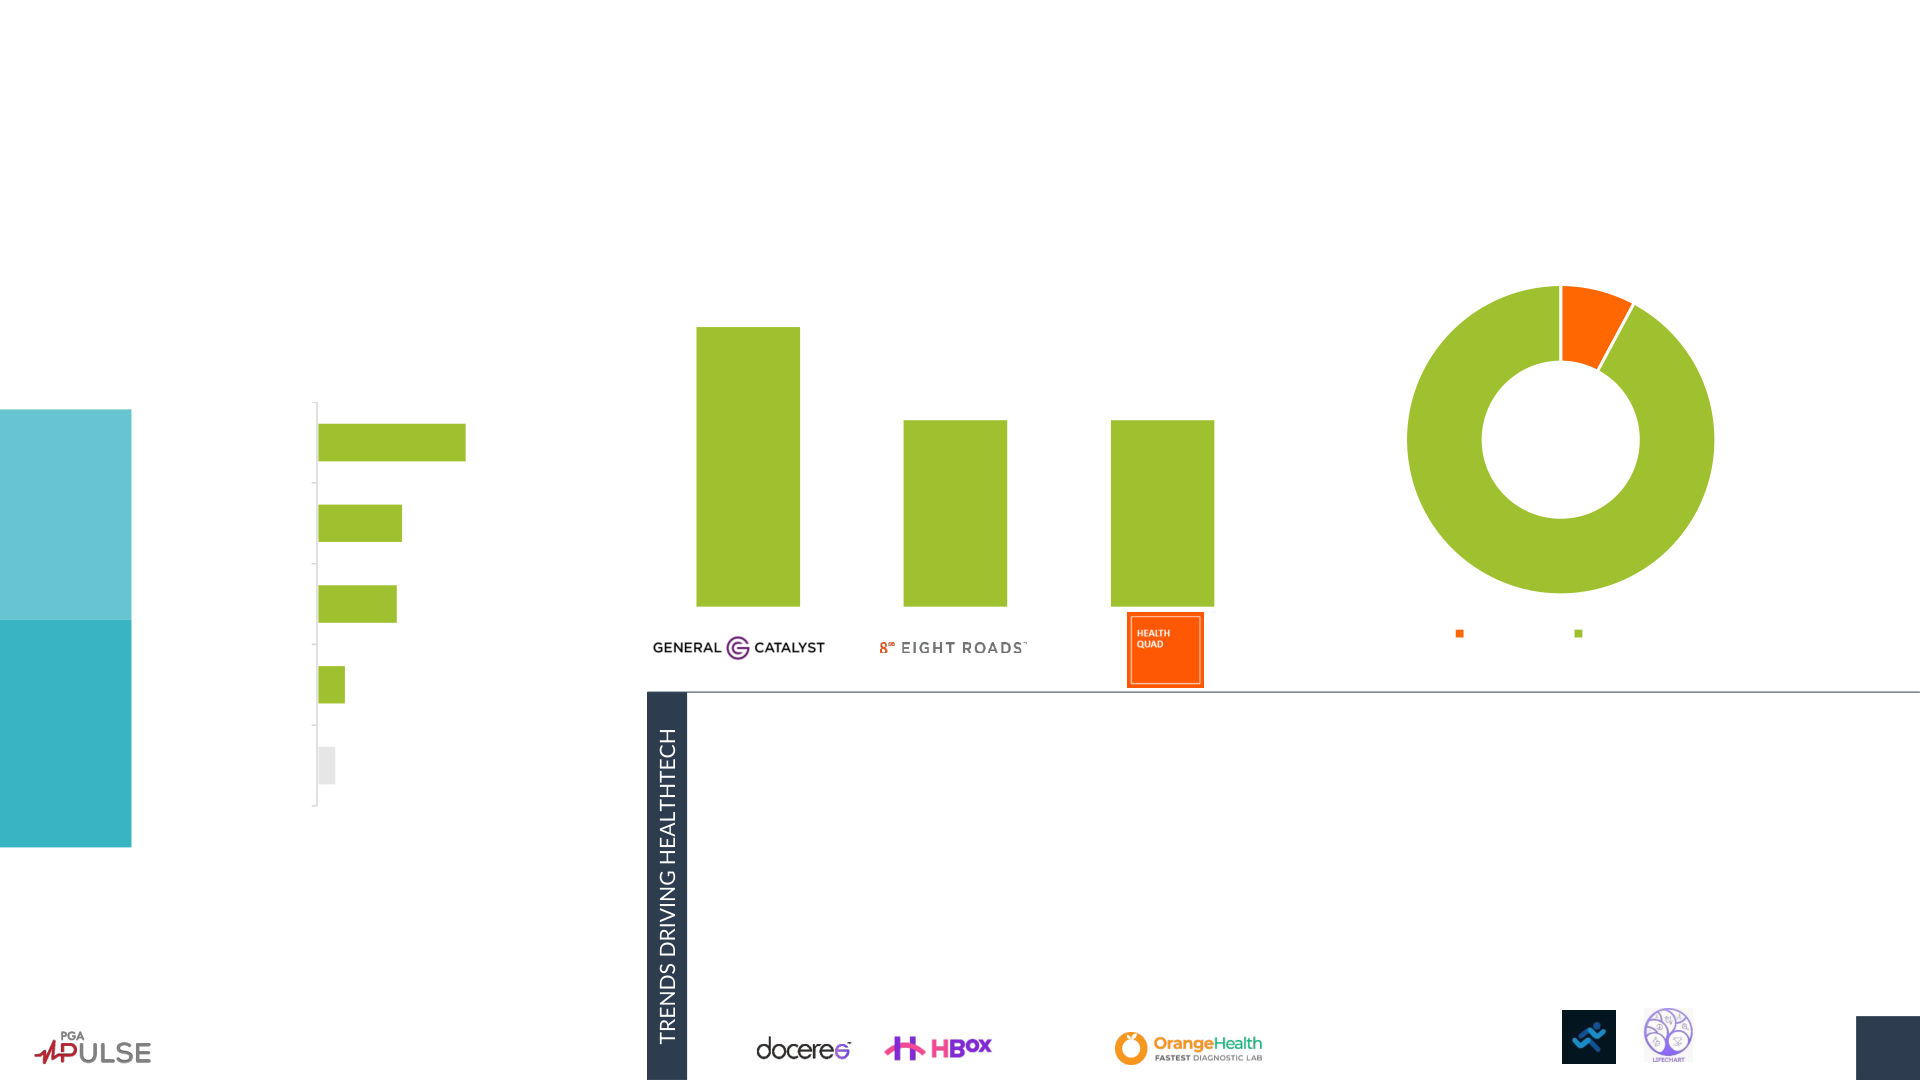
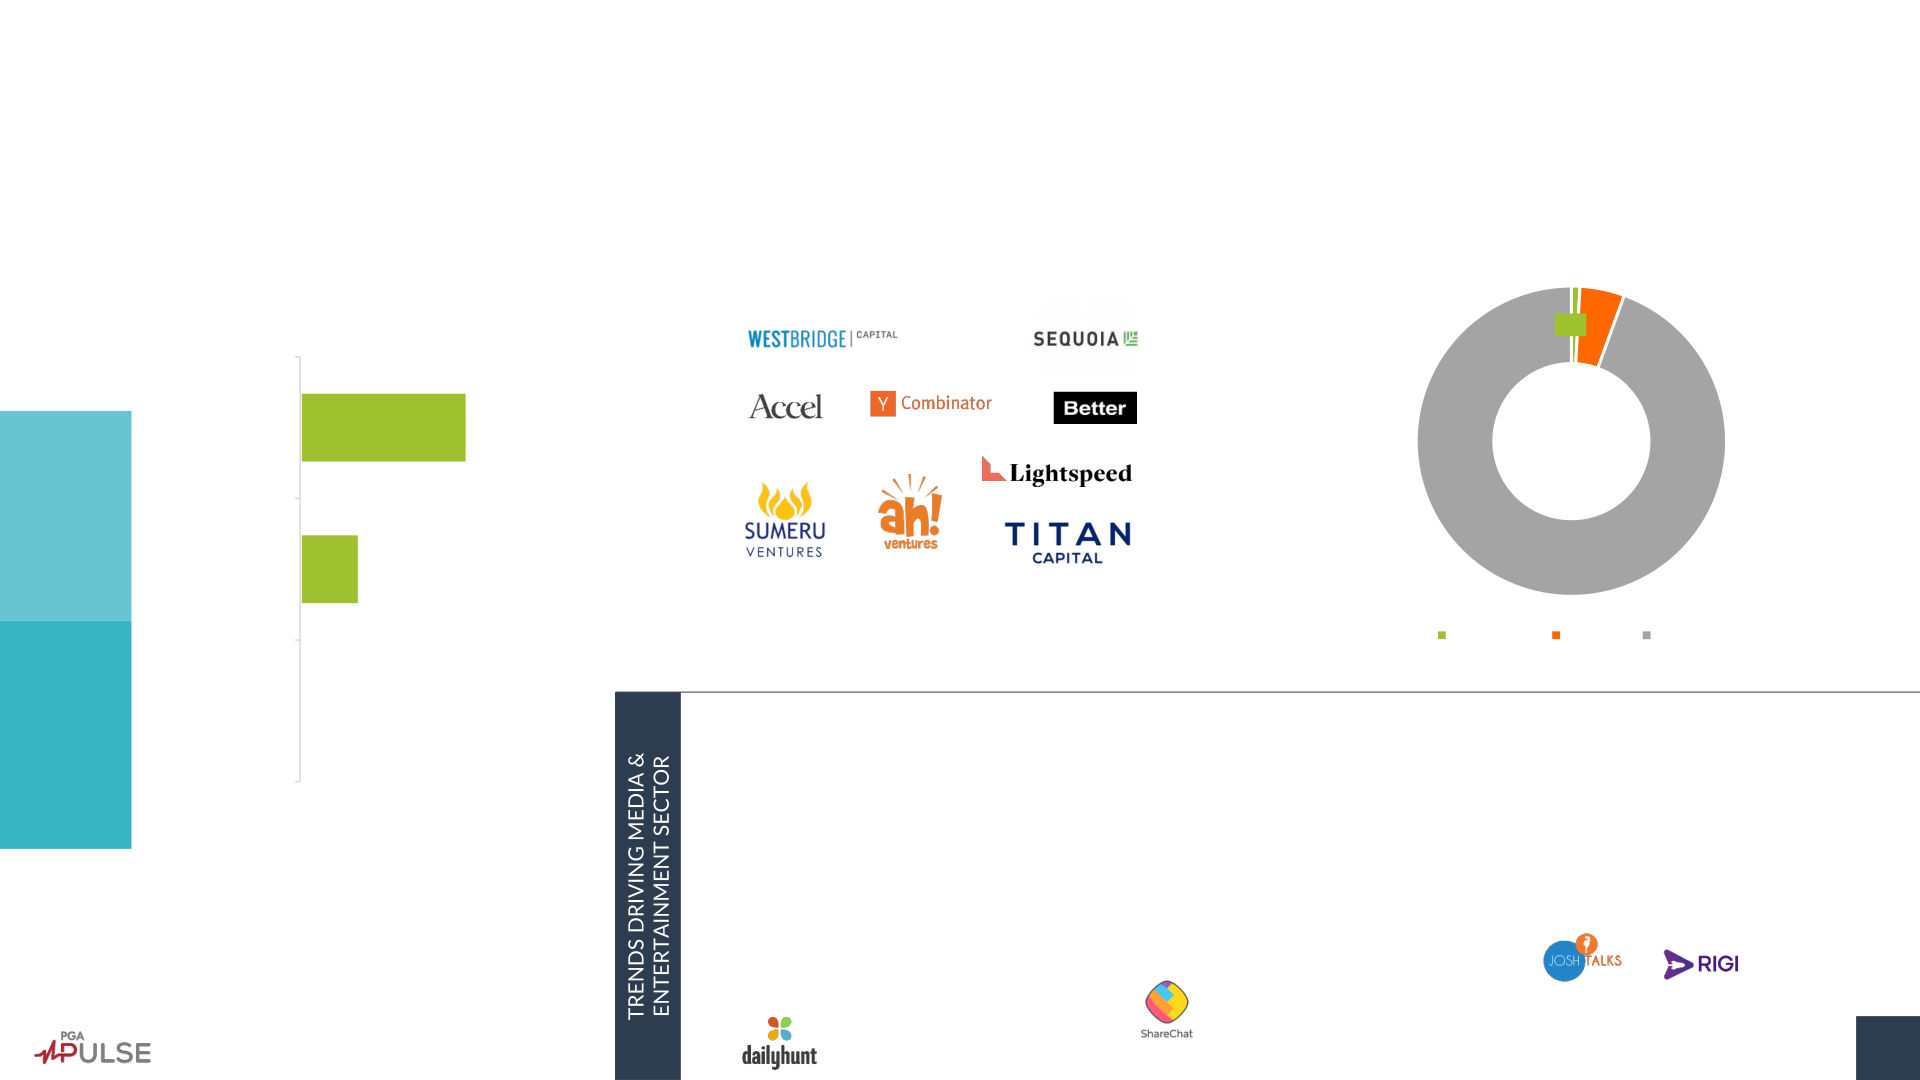
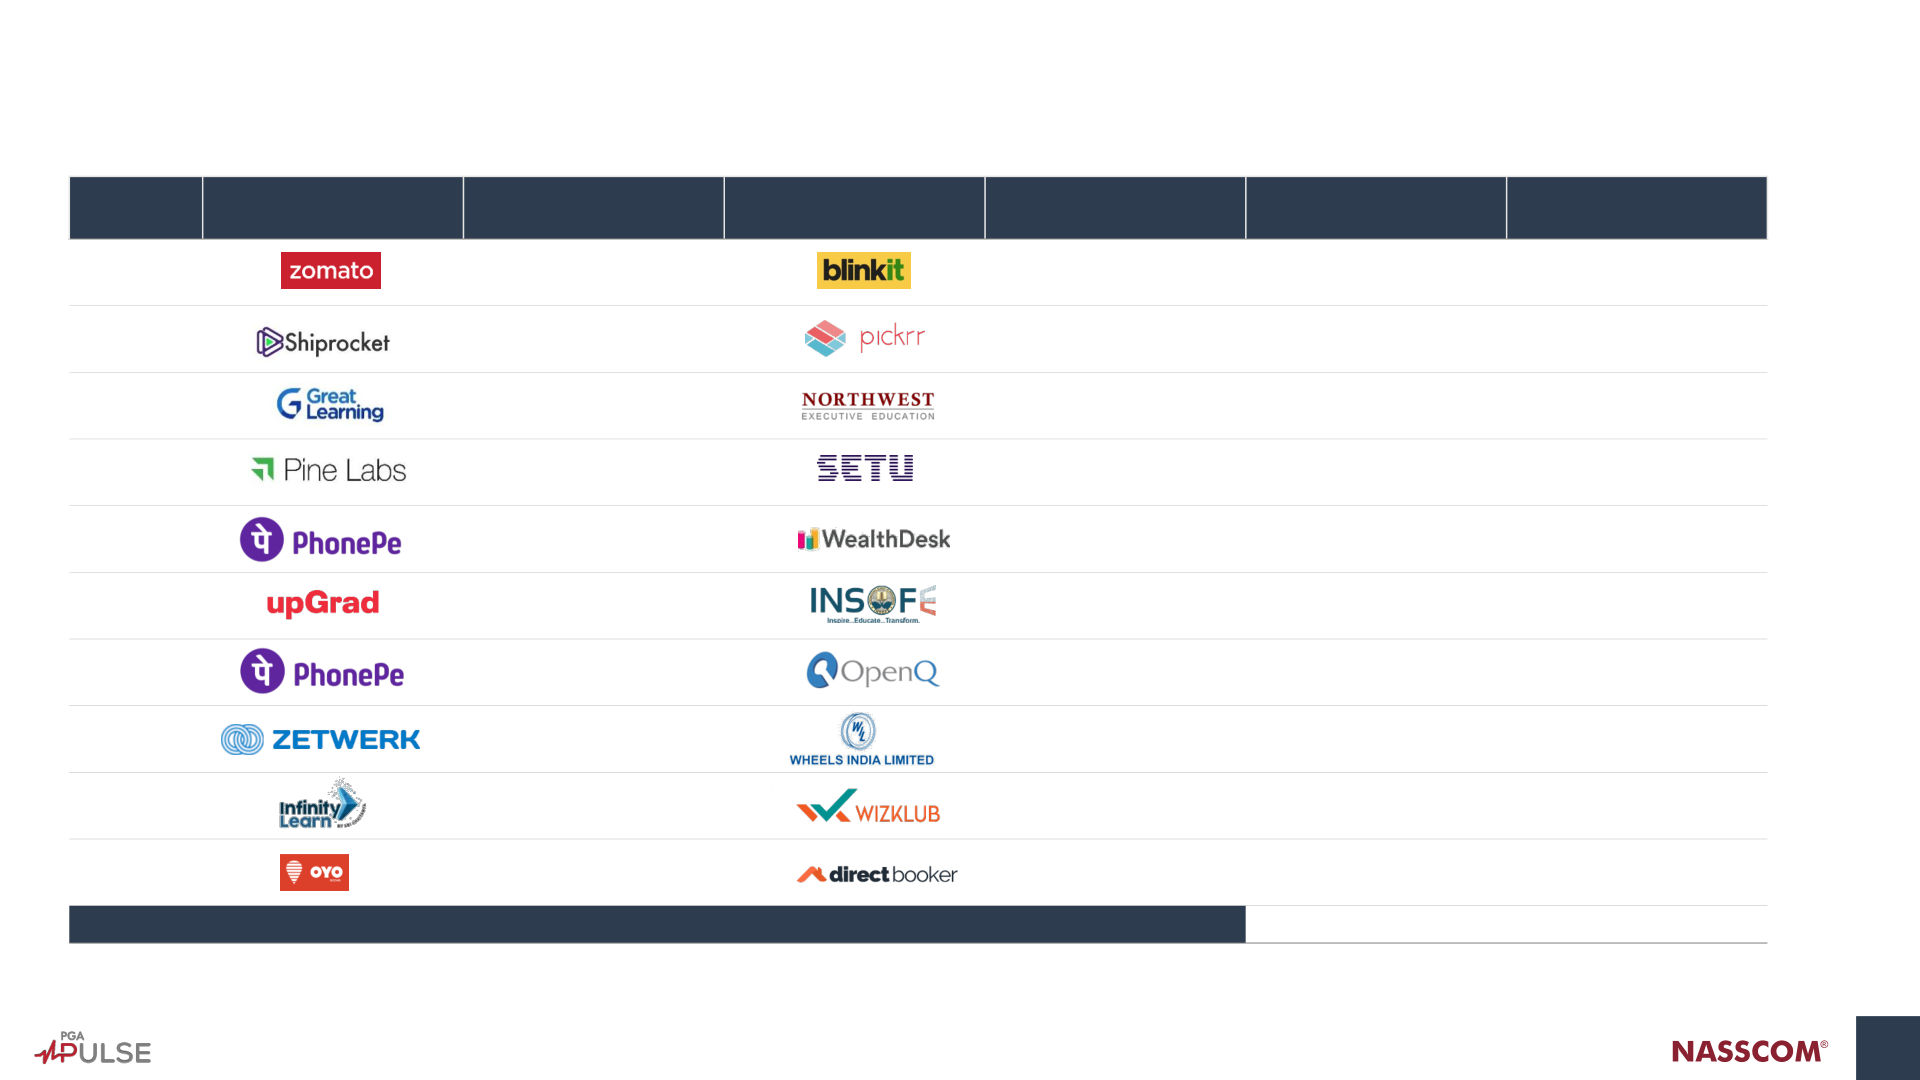
J u l y 2 0 2 2 QUARTERLY INVESTMENT FACTBOOK TECH START - UPS Q 2 CY2 2 START - UP DEAL ANALYSIS SUMMARY 03 CONTENT TECH START - UPS INVESTMENT TREND ANALYSIS 04 VERTICAL TREND ANALYSIS 1 1 HIGHLIGHT OF THE QUARTER 24 APPENDIX 2 7 2 Q2 CY22 H1 CY22 (Apr - Jun) (Jan - Jun) Funding # Deal Volume Funding # Deal Volume US $ 13.2 B 451 US $ 6 B 204 ~ 1% lower than H2CY21 Increased by ~48 % than H2CY21 Dropped by ~17% than Q1 CY22 ~17% lower than Q1 CY22 SUMMARY Unicorns Unicorns 16 Large ticket size deals helped generate a total 2 0 4 funding of ~US $ 6 B in Q 2 CY 22 Start - up ecosystem witnessed the birth of 4 new unicorns in Q 2 CY 22 , taking the tally to 2 0 unicorns in H 1 FinTech has emerged as the top funded vertical, followed by Media & Entertainment . Though the number of deals dropped as compared to previous Top Funded Vertical Most Funded Stage Top Funded Vertical Most Funded Stage quarters, it was dominated across most sectors by FinTech Growth FinTech Growth growth stage, indicating the confidence the 21 % of the total funding 26 % of the total funding ~58 % of the total funding ~55 % of total funding investors continue to have in the sector . 3 TECH START - UPS Q - o - Q AND CUMULATIVE COMPARISON INVESTMENT DEAL VALUE BY LATEST QUARTER TREND ANALYSIS DEAL VOLUME BY LATEST QUARTER FUNDING BY SALES CHANNEL AND FUNDING ROUNDS TOP INVESTORS AND THEIR FOCUS SECTOR DEEPTECH DEAL FLOW UNICORNS US $ 6 B raised by Indian tech start - ups in Q 2 CY2 2 , ~ 17 % lower than Q 1 CY2 2 Q - o - Q and Cumulative Comparison TOTAL FUNDING DEAL VOLUMES (NO. OF DEALS) (US$ in B) Investment in Indian tech start - (# of deals) 7.2 247 ups fell to US$ ~6B in Q2 CY22 6.5 6.0 204 owing to macro - economic 160 slowdown The number of deals in Q2 CY22 decreased by ~17% when compared to Q1 CY22 due to Q2 CY21 Q1 CY22 Q2 CY22 Q2 CY21 Q1 CY22 Q2 CY22 dampened market sentiments FUNDING BY DEAL SIZE FUNDING BY STAGE Despite the reduction in the (% of total funding) (% of total funding) total deal value, funding in late 6.5 7.2 6.0 6.5 7.2 6.0 stage start - ups in Q2 CY22 is 19% at par compared to Q1 CY22 24% 30% 52% indicating the investors’ 58% 71% % preference for already scaled 52% start - ups 58% 21% 61% 17% 11% % 15% 12% 9% % Even though the number of 29% 18% 13% 12% 9% % 9% deals have reduced, the Q2 CY21 Q1 CY22 Q2 CY22 Q2 CY21 Q1 CY22 Q2 CY22 average ticket size (~US$ 29M) remained consistent Early Growth Late < US$ 25M US$ 25-50M US$ 50-100M >= US$ 100M Source: PGA Labs Deals Database 5 FinTech and Media & Entertainment were the top sector s in Q 2 CY2 2 attracting ~ 45 % of total funding by value Deal value by latest quarter Large ticket deals like CRED and SPLIT OF DEAL VALUE Dailyhunt resulted in overall ( US $, Apr 2 2 – Jun. 2 2 ) increase in total investments in FinTech and M&E sectors FUNDING BY DEAL SIZE FUNDING BY STAGE FUNDING BY SECTOR (contributing ~45% of total funding in Q2 CY22) 3% 3% 12% 5% 18% 24% 26% 52% funding by deal size was in 8% the ticket size of US$ 100M or 15% above with Dailyhunt and 9% ShareChat raising big rounds US$ 6 B US$ 6 B US$ 6 B 52% 11% 19% 21% Growth stage deals contributed 16% 58% of the total funding in Q2 58% CY22 as the investors backed FinTech Media & Entertainment start - ups which have already EnterpriseTech Others reached a certain scale RetailTech EdTech Less than US$ 25M US$ 25M-50M Early Growth Late HealthTech Agritech US$ 50-100M More than US$ 100M Mobility Notes(s): Others includes Gaming , Food & FoodTech , Hospitality, Advertising , Automotive , SCM and Logistics , Aerospace, Legal Tech, HRTech Source: PGA Labs Deals Database 6 70 % of deals by volume were <US$ 25M; FinTech remains most active with 25 % deals Deal volume by latest quarter Number of <US$ 25M deals SPLIT OF DEAL VOLUME have reduced from 180 to 142 ( Apr 2 2 – Jun 2 2 ) (Q - o - Q) due to increased cautiousness among investors DEAL VOLUMES BY SIZE DEAL VOLUMES BY STAGE DEAL VOLUMES BY SECTOR Even though total deals have 3% declined Q - o - Q, no. of growth - 8% 20% stage deals have held ground 25% 10% due to strong fundamentals for start - ups scaled at a certain 33% level 5% 13% FinTech & EnterpriseTech 204 204 204 6% contributed ~46% of total number of deals as these 64% 21% 7% sectors are considered as safe 70% bets due to massive market 7% 9% potential globally Despite decrease in total FinTech EnterpriseTech number of deals, number of RetailTech HealthTech Less than US$ 25M US$ 25M-50M Early Growth Late large deals (>US$ 100M) EdTech Media & Entertainment US$ 50-100M More than US$ 100M Agritech Others remained constant indicating investor preference towards already scaled start - ups Notes(s): Others includes Real estate & construction, Food & Foodtech, SCM & logistics, HR tech, Travel & Hospitality Gaming , Automotive, Manufacturing, Aerospace, Energy, Mobility, Legal Tech, Advertisement 7 Source: PGA Labs Deals Database B2C tech start - ups funding accounts for ~63% of the total ~US$ 6B Funding by sales channel and funding rounds Series D accounted Top 3 B2C funded for ~20% of total start - ups – B2 C S tart - ups accounted for 63% of Growth stage funding accounts for 58 % of deal value funding owing to Dailyhunt, UpGrad deal value deals like Zepto and and ShareChat drove SPLIT BY SERIES (%, Apr 22 – Jun 22) Rapido the B2C sector DEAL FLOW SPLIT Seed 7% (%, Apr 22 – Jun. 22) Early (18%) Series A 11% B2C start - ups raised ~ US$ Top 3 B2B funded Series B 16% 3.8B in Q2 CY22, (owing start - ups were AI and to large ticket sizes of automation enablers UpGrad, Dailyhunt etc.) such as LeadSquared, Series C 12% Observe.ai and Growth GreyOrange (58%) Series D 20% B2B, 37% Series E 10% US$ 6 B Series F 5% B2C , 63% Start - ups in growth stage Series J accounted for Series G 4% have seen investments ~13% of total funding Late rise from 52% in Q1 to owing to Dailyhunt deal (24%) Series J 58% in Q2 owing to the 13% which accounted for investors backing up ~US$ 805M in Q2 CY22 start - ups which have Buyout 2% already reached a certain scale Source : PGA Labs Deals Database 8 Sequoia and Tiger Global were the leading investors across sectors in Q2 CY22 Top investors and their focus sectors MOST PROMINENT INVESTOR IN TERMS OF DEAL VOLUME TOP INVESTORS, SPLIT OF DEAL FLOW INVESTOR DIVERSIFICATION Prominent Tiger Global has (#, Apr 22 – Jun 22) investors Sequoia more than 40% Capital, Tiger deals in FinTech EnterpriseTech 15 Global, Alpha wave sector and 20% in and Accel have EnterpriseTech 14 done 6+ deals across sectors FinTech 8 6 5 EdTech 5 5 5 RetailTech Out of all the deals ~60% of the start - 4 Sequoia has ups in which Tiger invested in, ~25% Global and Sequoia 4 is in EnterpriseTech invested are in Media & Entertainment 4 and ~20% in growth stage FinTech 2 9 Source : PGA Labs Deals Database 4 new unicorns added in the Indian tech start - up ecosystem in Q 2 CY2 2 FinTech start - up Open becomes India’s first 1 6 4 neobanking unicorn, raises US$ 50M in Series D led by IIFL UNICORNS ADDED IN Q 1 CY2 2 ( JAN - MAR ) UNICORNS ADDED IN Q 2 CY2 2 ( APR - JUN ) SaaS platform LeadSquared raised US$ 153M in a Series C funding round from WestBridge Capital to become a unicorn Edtech start - up PhysicsWallah, has raised US$ 100M in its Series A funding from Westbridge and GSV Ventures Online beauty products marketplace Purplle, has raised ~US$ 34M as a part of its Series E funding round from Paramark Ventures Source : PGA Labs Deals Database 10 KEY VERTICALS WHICH HAVE CREATED IMPACT DURING THE QUARTER VERTICAL TREND FinTech EnterpriseTech RetailTech EdTech HealthTech ANALYSIS OUTPE R FORMING VERTICAL Media and entertainment FinTech The opportunity for FinTech resides in market expansion, shaping customer behavior, and long term financial industry developments . FinTech continues to develop and grow with ~ 33 % higher deal value than the previous quarter Growth in Payments and Crypto exchange continue to keep this sector in limelight FinTech continues to 1 unicorn added: Open dominate by raising 26% of the total Q2 CY22 funding Growth - stage funding Payments and Crypto dominated funding exchange raised ~40% deals by value (~60% of total FinTech share) funding Top 3 deals in FinTech sector in Q2 CY22: CRED (US$ 200M), FalconX (US$ 150M), and CoinDCX (US$ 135M) 12 ~60% investments in FinTech are in growth stage; Payments leads within FinTech with US$ 314M investments Payments have received the highest funding Tiger Global and Sequoia Capital lead the ~60 % of total investment is in growth Split by funding (US$M) number of deals done in FinTech sector stage By # of deals 6 Payments 20% 18% 22% US$ Crypto Exchange 20% 3 1.6 B 2 2 2 2 Lending and 18% collection 60% Personal wealth and 17% finance Early Growth Late Neo Banking 11% Payments Growth in Crypto space Lending and collection • As income levels and credit card penetration • Start - ups in crypto space are growing due to • Lending and collection start - ups such as Others 10% is increasing, it has led to payments startup demand from a diverse range of institutional Kissht & GetVantage have raised US$ 80M such as Cred raising US$ 200M market customers who are looking for a & US$ 36M respectively • With increasing penetration of digital reliable execution platform in volatile crypto • These start - ups will use the funds to Neobanking 4% payments, Razorpay raised US$ 75M in Q2 markets accelerate growth, build new financial CY22 due to expansion into new sub - • GIC invests US$ 150M in FinTech star - tup products for its customers, expand and sectors like neo - banking and SME payments FalconX in Q2 CY22 improve the technology platform Source: PGA Labs Deals Database 13 EnterpriseTech EnterpriseTech start ups in India attracted ~US$ 989M in funding in Q2 CY22. This reflects a major evolution in AI, SaaS & IT space. EnterpriseTech has aided businesses of all sizes and scale in exploring uncharted territory, reinventing their industries, and realizing their full potential. EnterpriseTech sector 1 unicorn added: raised ~16% of total LeadSquared funds raised in Q2 CY22 Fastest - growing Growth - stage funding trends in dominated funding by EnterpriseTech space value (~71% share) are SaaS & Artificial Intelligence Top 3 deals in EnterpriseTech sector in Q2 CY22: Leadsquared (US$ 153M), Observe.ai (US$ 115M), and GreyOrange (US$ 110M) 14 EnterpriseTech received a total funding of ~US$ 989M in Q2 CY22; Sequoia leads with maximum deals 71 % investments are in Growth stage SaaS & AI based tech start - ups have Sequoia Capital and Accel are the prominent investors received the highest funding in in EnterpriseTech By # of deals EnterpriseTech space Split by funding (US$M) 4 11% 18% 3 3 3 3 ~ US$ SaaS 44% 2 2 2 2 989M 71% AI 43% Early Growth Late SaaS players emerging Increased focus on cloud AI space is booming in within EnterpriseTech integration EnterpriseTech • AI and ML will transform businesses by reducing • Cloud - based start - ups are attracting • SaaS platforms present a global opportunity costs, managing risks, streamlining operations, investments as It is the backbone for many for investors to bank on. Leadsquared raised IT-BPM 13% accelerating growth, and fueling innovation companies riding the megatrends that are US$ 153M in Q2 CY22 with B2C services • Investors like Softbank Vision Fund, BlackRock, shaping the investment landscape emerging and thrive in the South Asian Mithril Capital Management are investing in AI • Start - ups such as MoEngage & Traceable have market based start ups such as Observe.ai (US$ 125M) raised US$ 77M & US$ 60M respectively in this • SaaS start up Sirion Labs has also raised US$ & GreyOrange (US$ 110M) quarter 85M in Q2 CY22 Source: PGA Labs Deals Database 15 RetailTech RetailTech is booming with spaces like social commerce, quick commerce, etc gaining traction . The shopping experience for consumers has undergone a significant transformation as a result of the advent of cutting edge technologies and digital disruption RetailTech continues to see good momentum with ~ 9 % of the total Q 2 CY 22 funding . RetailTech companies Tiger Global, Sequoia raised ~US$ 554M in and RiSo have been Q2 CY22 active in this space B2C Vertical Growth - stage funding Marketplace & B2B dominated funding Marketplace raised deals by value (~88% ~82% of total share) RetailTech funding Quick commerce is increasingly gaining traction with Zepto raising US$ 200M in this quarter and Blinkit getting acquired by Zomato 16 Vertical e - commerce start - ups dominated Q2 CY22; ~88% investments in RetailTech are in growth stage B2C marketplace platforms have Several investors have been involved in 88% of investments are in Growth received the highest funding the deals in the RetailTech sector stage Split by funding (US$M) 12% B2C vertical 49% marketplace US$ 554M B2B marketplace 33% 88% Others 11% Early Growth B2C Horizontal 5% marketplace Social commerce attracting Quick commerce B2B marketplaces are capturing early stage investments becoming mainstream investor interest Social Commerce 2% • Quick commerce companies are gaining • Orders placed on B2B marketplace platforms • Social commerce players have evinced traction with evolving consumer preferences tend to be bulky in nature which is one of the interest from masses owing to increased • Zepto raised US$ 200M from existing main reasons why the B2B digital market is digital connectivity investor Y Combinator Continuity Fund growing rapidly • Social commerce platforms ApnaKlub and along with new investors, Kaiser • B2B start - ups such as Arzooo & Fashinza raised Frendy have raised US$ 10M & US$ 3M in Permanente, at a valuation of US$ 900M significant funding in this quarter (US$ 70M & Series A rounds respectively • Zomato acquired Blinkit in a proposed all US$ 60M respectively) because of the high stock deal for INR 4,447 crores conversion rates and order values. Source: PGA Labs Deals Database 17 EdTech The growth surge in this industry is largely driven by K 12 & online certification start - ups . In response to opening of physical centers post covid, Edtech players such as Byjus, Unacademy, etc are concentrating on a hybrid model and are in the process of building an offline presence Strong growth potential 1 unicorn added: in EdTech, with a PhysicsWallah funding of ~US$ 482 M (8% of total funding) in Q 2 CY 2 2 Online certification Growth - stage funding and K12 raised ~82% dominated funding of total EdTech deals by value (~74% funding share) Top 3 deals in EdTech sector in Q2 CY22: UpGrad (US$ 225M), PhysicsWallah (US$ 100M), and LeapScholar (US$ 75M) 18 ~74% of EdTech funding is towards start - ups in the growth stage; Online certification leads within EdTech with US$ 233M investments Online Certification has received the Sequoia is the prominent investor in the EdTech sector 74% investments are in Growth stage highest funding in EdTech with 2 deals Split by funding (US$M) By # of deals 2 26% Online Certification 48% US$ 1 1 1 1 482 M 74% K12 34% Early Growth Education advisory 16% platform Rise in E - learning within Edtech Product offerings by start - ups Increasing presence of K12 start - ups • As people are shifting to online courses to • With offline classes resuming, EdTech • K12 and Test Prep companies are becoming Test Prep 2% improve their skills and stay relevant, the players such as Unacademy, Byjus etc. are horizontal players with presence across K12 global e - learning market is expected to reach all in the process of creating hybrid models – curricular and non - curricular space and Test US$ 325B by CY25 and large institutions have to cater to both online and offline market Prep. The strategy is to extract a higher LTV already started to move to take advantage of • Counselling and study abroad EdTech from the students by addressing their needs this growth scenario companies gaining traction since students starting from school exams to other tests • Unacademy raised US$ 225M from Lupa are reconsidering international study options • WestBridge invested US$ 100M in a K12 Systems, ETS, ArcelorMittal and Temasek in startup - Physicswallah in Q2 CY22 which is Q2 CY22 emerging with a Star Teacher model Source : PGA Labs Deals Database 19 HealthTech Rise in investors’ interest in HealthTech segment can be owed to increasing healthcare awareness and consciousness among people HealthTech start - ups dealing in B 2 B marketplace and Diagnostics sectors are gaining traction as they are solving problems and simplifying processes for all stakeholders HealthTech continues to General catalysts and Eight develop and grow with Roads Ventures have been total funding of US$ 275M active in HealthTech space Healthcare service and 92% investments in the B2B Marketplace have HealthTech sector are in raised ~65% of total growth stage start - ups; HealthTech funding followed by early stage (8%) Top 3 deals in HealthTech sector in Q2 CY22: MedikaBazaar (US$ 65M), Redcliffe Labs (US$ 61M), and Loop Health (US$ 25M) 20 HealthTech start - ups secured investments of US$ 275M in Q2 CY22; General Catalyst was the major investor Healthcare services has received the General Catalyst is the major investor in 92 % investments are in Growth stage highest funding HealthTech sector with 3 deals Split by funding (US$M) By # of deals 3 8% 2 2 US$ Healthcare services 41% 275M B2B marketplace 24% 92% Diagnostics 22% Early Growth Healthcare 8% Digital Transformation in Healthcare Fitness & holistic wellness platforms AI in Healthcare Others 5% • AI products are empowering healthcare • Digital transformation in healthcare is a building • Fitness & wellness apps can be of great use professionals by aiding during preventive block of a patient - focused approach to to patients and the healthcare system when screenings, disease detection, emergency healthcare. It will help healthcare providers comes to self - monitoring, self - management care enabling a seamless workflow in the streamline operations, understand what the and self - care healthcare space • Fitness & wellness start - ups such as Fitmint patient requires, build loyalty and trust and • AI based companies Doceree and Hbox.ai offer a better user experience & Lifechart raised funds ~US$ 1.6M & ~US$ have raised ~US$ 12M in Q2 CY22 • OrangeHealth raises US$ 25M in Q2 CY22 as 200K resp. in this quarter remote patient monitoring is becoming the future of delivering healthcare services Source: PGA Labs Deals Database 21 Media & Entertainment Media & Entertainment (M&E) industry is in a transformation phase as both traditional and modern models continue to coexist Interactivity, digitalization, multiple - platforms, multiple devices and globalization of services based landscape has remodeled the media and entertainment vertical over the last decade . Media & Entertainment Sequoia and Accel have industry has raised a been active investors in funding of US$ 1.1B in this space Q2 CY2 2 which is ~19% of the total funds raised Late - stage funding News and media apps dominated funding by raised ~73% of total funding in the sector value (~94% share) Dailyhunt and ShareChat were the highest funded start - ups in the sector with fundings worth US$ 805M and US$ 255M respectively 22 ~94% investments in Media and Entertainment are in late stage; News & Media apps lead within M&E with US$ 822M investments News & Media app has received the Several investors have been involved in the 94 % investments are in Late stage highest funding in Media & deals in the Media & Entertainment sector * Entertainment 5% Split by funding (US$M) 1% News and Media 73% US$ App 1.1B 94% Social Media 26% Growth Early Late Others 1% Growth of the content creator News & Media Apps flourishing Rise in the Social Media Apps in India economy • Daily hunt raised a significant funding of US$ • ShareChat raised US$ 255M in Q2 CY22 from • Platforms like Josh Talks & Rigi are becoming 805M in Q2 CY22 from CPP Investments, Ontario Google, Times Group, and Temasek. It has built increasingly specialized and community Teachers', Luxor Capital & Sumeru Ventures. diversified monetization avenues beyond oriented, engaging audiences on a more • India’s digital content is experiencing phenomenal advertising in areas like virtual gifting and video personal level with influencers growth in the fast - growing short video and local commerce and has grown to become a popular language content space short video app Note: *All investors mentioned above have been • ~70% of Indians find local language digital content involved in 1 deal each more reliable Source : PGA Labs Deals Database 23 FOCUS ON INORGANIC GROWTH : STRENGTHENING CAPABILITIES ACROSS ITS HIGHLIGHT VALUE CHAIN OF THE DIVERSIFICATION ACROSS GEOGRAPHIES AND ADJACENT MARKETS QUARTER : CONSOLIDATION THROUGH ACQUISITIONS Reasons for acquisitions by leading tech start - ups • Zetwerk acquired plant of Wheels India to strengthen its manufacturing capabilities of critical parts of power, roads and railways Strengthening • u pGrad acquired INSOFE to strengthen its data analytics courses , Infinity Learn capabilities across acquired Wizklub to augment foundation skills courses for the K12 segment value chain and Great Learning acquired Northwest to address professional skilling segment for enterprise clients • PineLabs , a leading merchant platform acquired Setu for their API capabilities & to enable broader integration with open payment platforms • Zomato acquired Blinkit to enter quick commerce by leveraging its proprietary Geographical & tech platform, vendor, brand relationships and dark stores network adjacencies • OYO acquired Direct Booker to strengthen its presence in Europe and Croatia diversification with ~9K+ homes registered on the Direct Booker platform • PhonePe acquired Weathdesk and OpenQ that cover the entire asset management and advisory value chain to foray into wealth management • Shiprocket acquired Pickrr to consolidate and acquire large customers along Consolidation with access to technology and team enabling full stack creation for ecommerce enablement • Further consolidation expected in H2 CY22 with established start - ups looking for M&A opportunities at attractive valuation to increase market share Source : Secondary research, PGA Labs Deals Database 25 Established tech start - ups are hunting for growth inorganically AMOUNT # COMPANY SECTOR TARGET SECTOR DATE (US$ M) 1 Food & Foodtech RetailTech 568 June 24, CY22 2 SCM & Logistics SCM & Logistics 200 June 15, CY22 3 Edtech Edtech 100 May 10, CY22 4 FinTech FinTech 70 June 23, CY22 5 FinTech FinTech 50 May 18, CY22 6 Edtech - 33 May 2, CY22 7 FinTech EnterpriseTech 25 May 18, CY22 8 RetailTech - 12.7 June 30, CY22 9 Edtech Edtech 10 May 27, CY22 10 Travel & Hospitality Travel & Hospitality 5.5 May 9, CY22 Total of top 10 deals 1,074.2 Source: PGA Labs Deals Database 26 TOP 10 DEALS APPENDIX SECTOR WISE TOP DEALS STAKEHOLDER INITIATIVES METHODOLOGY DEFINITIONS : STAGES / SECTORS Appendix Top deals of Q 2 CY2 2 FUNDING FUNDING # COMPANY FOUNDED SECTOR SUB - SECTOR INVESTORS (US$ M) STAGE CPP Investments, Ontario Teachers' Pension Plan News and Media 1 2009 Media & Entertainment 805 Late Board (Ontario Teachers’), Luxor Capital, and Sumeru App Ventures 2 2017 Media & Entertainment Social Media 255 Late The Times Group, Google and Temasek Holdings Lupa Systems, Education Testing Service. ArcelorMittal, 3 2015 EdTech Online Certification 225 Growth Sunil Bharti Mittal, and Temasek Holdings Pte 4 2018 FinTech Payments 200 Late GIC B2C vertical Nexus, Kaiser Permanente Ventures, Glade Brook 5 2020 RetailTech 200 Growth marketplace Capital Partners, and others Two wheeler taxi Swiggy, TVS Motor Company and existing investors 6 2015 Mobility 180 Growth aggregator Westbridge, Shell Ventures and Nexus Ventures 7 2011 EnterpriseTech SaaS 153 Growth WestBridge, Gaja Capital 8 2018 FinTech Crypto Exchange 150 Growth GIC and B Capital Kindred Ventures, Pantera Capital and Steadview Capital Management LLC, Kingsway, DraperDragon, 9 2018 FinTech Crypto Exchange 135 Growth Republic, B Capital Group, Coinbase, Polychain and Cadenza 10 2018 FinTech Neo Banking 128 Early Green Frontier Capital Total of top deals 2,431 Source ( s ): PGA Labs deal database , PGA Labs analysis 28 Appendix Sector wise top deals in Q2 CY2 2 FUNDING FUNDING FUNDING FUNDING COMPANY SUB - SECTOR INVESTORS COMPANY SUB - SECTOR INVESTORS (US$ M) STAGE (US$ M) STAGE ENTERPRISETECH FINTECH CRED Payments 200 Late GIC LeadSquared SaaS 153 Growth WestBridge, Gaja Capital Crypto FalconX 150 Growth GIC and B Capital Observe.ai AI 125 Growth SoftBank Vision Fund Exchange Kindred Ventures, Pantera Capital and Crypto CoinDCX 135 Growth Steadview Capital Management LLC, GreyOrange 110 BlackRock, Mithril Capital Management AI Late Exchange Kingsway, DraperDragon, Republic EDTECH MEDIA & ENTERTAINMENT CPP Investments, Ontario Teachers' Online News and UpGrad 225 Temasek Growth Dailyhunt 805 Late Pension Plan Board (Ontario Teachers’), Certification Media App Luxor Capital, Sumeru Ventures PhysicsWallah K12 100 WestBridge Early ShareChat Social Media 255 Late The Times Group, Google Education Steadview Capital, Sequoia Capital Leap Scholar advisory 75 Growth India, Paramark Ventures, Owl News and Way2News 16.7 Early WestBridge platofrm Ventures, Jungle Ventures Media App RETAILTECH HEALTHTECH Lighthouse, Nykaa, Bikaji Foods and Nexus, Kaiser Permanente Ventures, B2B B2C vertical MedikaBazaar 65 Growth Duroflex, Creaegis, Health Quad, Zepto 200 Growth Glade Brook Capital Partners, and marketplace marketplace Ackermans & van Haaren others B2B LeapFrog, Healthquad, Schroders, LC Arzooo 70 Growth SBI Investment, Trifecta Capital Redcliffe labs Diagnostics 61 Growth marketplace Nueva, and Growth Spark Ventures B2B WestBridge, Prosus Ventures, Accel, Fashinza 60 Growth General Catalyst Partners, Elevation marketplace Elevation, and ADQ Loop Health Healthcare 25 Growth Capital. Source ( s ): PGA Labs deal database , PGA Labs analysis 29 Appendix Digital India GENESIS Qualcomm Semiconductor IIMs launches accelerator Positive outlook for Mentorship program programs start - up ecosystem • GENESIS implies Gen next Support for • Qualcomm has partnered with Centre for • The business incubator and entrepreneurship Innovative Start - ups Development of Advanced computing (C development centre of IIM - K has launched LIVE X, is evident from • Government of India scheme launched DAC) to provide support to start - ups working an AI and ML themed accelerator program to to empower national Deeptech start - in semi - conductor space nurture the entrepreneurial journey of new - age different ups • Start - ups of semiconductor space will be start - ups stakeholder • Focused on supporting and growing provided mentorship, technical training, and • IIE, Guwahati, signed an MoU with the Incubation businesses in small towns of India industry outreach opportunities and Enterprise Support Centre of IIM - S to boost initiatives • Massive budget of Rs. 750 crore • Qualcomm will shortlist 10 start - ups in CY22 the entrepreneurial ecosystem in the North - who will be partnered with leaders for product Eastern Region planning and development Digital India Bhashini Start Up India (GoI) schemes T - Hub, AWS collaborate to launch drone - tech accelerator program • Initiative by PM Narendra Modi to boost • Venture capital scheme – provides interest • T - Hub, Telangana State Innovation Cell (TSIC), and AWS Indian start - ups free loans to meet capital requirements joined together to launch India's first drone - tech • The scheme aims to provide access to • Stand up India – Facilitate bank loans to accelerator program, AWS Dronetech Accelerator. easy access to internet and digital assist SC/ST and/or women entrepreneurs • The initiative will provide entrepreneurs with the tools & services in vernacular languages in India knowledge to accelerate the adoption of drone • Leverage language - based machine technology in India with the goal of supporting start - ups learning models to help create content in focusing on the public sector. Indian languages Source(s): Secondary research, PGA Labs analysis 30 Appendix Scope WHAT’S EXCLUDED FROM WHAT'S INCLUDED IN THE Inclusions & Exclusions THE REPORT? REPORT? • Non - tech start - ups operating in the • Only tech start - ups have been consumer space have not been considered for this report which are included in this report working towards innovation in technology , business process or • Investments from angel investors , business model incubators and start - up accelerators have been excluded • Start - ups which have received funding from private equities or venture capital • Debt investments and strategic deals firms have been considered into tech start - ups have not been considered • Founders of Indian origin with HQ or core product development in India • Start - ups at the idea stage without a prototype or minimum viable product • Start - up to have a prototype or MVP; have also not been considered idea stage start - ups are not considered 31 Appendix PRIMARY INPUT FOR THIS REPORT Methodology INCLUDES THE FOLLOWING SOURCES This pulse report has been co - developed by NASSCOM and PGA Labs through a comprehensive study to understand the tech start up landscape in India Extensive research of media articles This report analyses the following : Inc42 Mint • Current investment scenario and trends that define the Indian tech start - up Your story Business ecosystem IVCA Standard • Ecosystem enablers like Incubators/Accelerators as well as government policies Economic Times • Ecosystem enablers like Incubators/Accelerators as well as government policies • The total of all quarters is not comparable to the data published in NASSCOM’s Annual Start - up report as the definitions and criteria considered are different PGA Labs proprietary deal database Government websites Ministry of corporate affairs SEBI Sector analyst reports 32 Definitions of stages and sectors Appendix FoodTech Media & Entertainment Automotive Tech enabled companies supporting the STAGES OF FUNDINGS HAVE BEEN Provides content for entertainment across the Companies involved in production, FoodTech industry web and mobile medium MAPPED AS manufacturing, sales and services of motorized E.g., Online Food Ordering, Restaurant Management Cloud E.g., News & Media Apps, Live Streaming Apps, News vehicles Solutions, Food Discovery Platform Platforms, OTT Content, Video Intelligence Apps, etc. E.g., Electronic Engineering, System Integration, Automotive Maintenance, Electric Vehicles, Automotive marketplaces, etc. Series A and prior rounds are early stage SCM & Logistics RetailTech Enabling tech in logistics services and supply Series B,C,D and E are growth stage Companies enabling Sales of goods and product FinTech chain management online or Integration of tech in offline markets Enables financial services, banking and insurance Series F and above are late stage E.g., Logistics and Distribution Platform, Fleet Management, E.g., Products/Services cutting across several verticals Warehousing, IoT Platform for Logistics, IoT Platform for through technology Goods Transportation Marketplace, etc. E.g., Online Banks, Financial Management Apps, Payment Fashion & Lifestyle Management Platforms, Alternative Lending Platforms, Money Transfer Platform, Expense Management, Investment Gaming Marketplaces, Online grocery & Home essentials Platforms, Cryptocurrency & Trading Platforms, etc. Tech Innovation and facilitation in the Gaming platforms. Also includes Retail enablers, B2B industry marketplaces, Social commerce platforms, Rental EdTech E.g., AR/VR Gaming, Community platform Games, Fantasy platforms etc. Gaming Platforms etc. Provides learning solutions & services through technology SECTOR DEFINITIONS AgriTech Legal Tech E.g., Learning Apps, Test Preparation Tech, Education Advisory Platform, K 12/Higher education platforms, Language Learning Start ups engaged in tech enablement in the Tech based companies for Legal help to EnterpriseTech Platforms etc. Agricultural industry Individuals/Corporates E.g., Field Surveillance, Precision AgriTech, Farm infrastructure, B2B Product companies targeting Horizontal E.g., Contract Management, Brand Protection and Anti Soil Testing, Farm Input E Commerce etc. Counterfeit, Legal Services Discovery/Booking marketplaces, Travel & Hospitality solutions for Large Enterprises / SMBs etc. E.g., Data Analytics/AI/ML Platforms, Development Platforms, Tech companies engaged in supporting the travel Collaboration tools Productivity Applications, Customer Advertising & Marketing Tech and hospitality industry Services, Big Data/Cloud/Security Infrastructure, etc. Provides direct advertising and marketing E.g., Hotel Booking Services, Travel Planning, Travel Packages Portal, Travel Collaboration Community, etc. assistance through technology HealthTech E.g., Content marketing, influential marketing, Push Provides technology platform for solving notifications etc. Mobility HealthTech problems Tech - enabled companies providing simplified E.g., Medical Solutions, Marketplace for Health Services, Aerospace & Defense Transportation services to users Health Lab Aggregators, Online Pharmacies, E - Diagnostics, Tech - based companies supporting the Defence E.g., Car pooling, Self Drive Rentals, Two - wheeler taxi Ambulance Aggregator, etc. and Aviation industry aggregators, Mass Transit, Tech Enablers E.g., Military Drones, Green Propulsion Systems developers, HRTech Sensors and Platforms for security applications etc. Industrial & Manufacturing Tech - enabled companies supporting Human Engaged in manufacturing of tech - enabled Resources Activities Energy & Utilities devices or machines; Construction/Mining E.g., Applicant Tracking systems, HR Management System, Tech Enablement for Natural Resource Candidate Assistance & Sourcing, Corporate Training/Learning sector, etc. Management and Utilization and Development, Recruitment Marketplaces, etc.. E.g., IoT based Predictive Maintenance of Machines, 3D E.g., Renewable Energy products, Recycling of Resources, Printing (Manufacturing) Energy Production and Distribution, EV charging Infrastructure etc. 33 Definitions of sub - sectors Appendix FINTECH HEALTHTECH • Lending & collection: Tech start - ups dealing with financing services to • Online Pharmacy: Platforms which enables online delivery of medicines and consumers or other businesses medical products • Personal wealth & finance: Platforms enabling trading, personal wealth • B2B Marketplace: Provides healthcare products or services to other businesses planning, etc. dealing with healthcare • Neo Banking: Digital banks that does not have physical branches • Healthcare services: Tech companies which provides any healthcare services • Payments: Apps & platforms which enables payment service such as diagnostics etc. and makes healthcare accessible to consumers as well as • Crypto Exchange: Companies dealing with cryptocurrency exchange to doctors RETAILTECH ENTERPRISETECH • B2B marketplace: Companies enabling buying or selling products to other • AI: B2B companies which deal in Artificial Intelligence businesses on a single platform • SaaS: New age tech companies providing software solutions to other • Social commerce: Companies dealing with buying or selling of products via social business media / community platforms • IT - BPM: Providing IT services to other businesses • B2C horizontal marketplace: E - commerce companies that sell products directly to consumers from a large number of categories • B2C vertical marketplace: E - commerce companies that sells products directly to MEDIA & ENTERTAINMENT consumers around a specific niche • OTT content: Companies dealing with media service offered directly to EDTECH viewers via internet th • News & Media app: Comprises of news & magazine apps, print media, • K12: Education platforms dealing with providing education till 12 standard television & radio, etc. • Test Prep: Platforms enabling students for preparation of any entrance test • Live streaming app: Platforms which deals with live streaming of sports, • Online certification: Online platforms which provides any kind of events, games, etc, degree/diploma/certification • Social Media: Websites or apps that enable users to create or share • Language Learning: Platforms enabling learning new languages content in social networking • Education advisory platform: Companies dealing with helping parents/students, organizations with education planning 34 About NASSCOM is the industry association for the IT - BPM sector in India A not - for profit PGA Labs is a technology - enabled business research & intelligence services firm that organization funded by the industry , its objective is to build a growth led and specializes in driving decision from on - ground insights Our teams are multifaceted with sustainable technology and business services sector in the country with over 3100 a unique mixture of qualitative , quantitative and digital research experts . With a holistic members NASSCOM Research is the in - house research and analytics arm of approach focusing on the “ What and Why ”, we are able to extract relevant insights NASSCOM generating insights and driving thought leadership for today’s business from data employing advanced technology tools and innovative data gathering leaders and entrepreneurs to strengthen India’s position as a hub for digital approaches . technologies and innovation Our clients use our capabilities to generate competitive / market insights for the sectors they operate in, sectors they want to expand to or the sectors of interest for their USAGE OF INFORMATION portfolio companies Forwarding / copy / using in publications without approval from NASSCOM will be considered as infringement of intellectual property rights . www.pgalabs.in FOR QUERIES, PLEASE CONTACT VAISHNAV KUMAR RAI Manager , Cooperate Communications vaishnav.rai@praxisga.com +91 7827 944 925 35 PGA Labs We enable better decisions. Deep business research and intelligence that helps make 50% BETTER DECISIONS 250 + faster to annual outcomes engagements Deep on - ground insights that you can act on 98%+ 4 offices, deep experience across accuracy geographies – India, US, Europe, MEA, and 600+ SEA region years domain expertise Advanced technology tools and innovative 34 data gathering approach practices Multifaceted teams with a unique mixture of qualitative, quantitative, and digital research 100+ 40 - 60 experts team members she/he ratio DISCLAIMER The information contained herein has been obtained from sources believed to be reliable NASSCOM and its advisors & service providers disclaims all warranties as to the accuracy completeness or adequacy of such information NASSCOM and its advisors & service providers shall have no liability for errors , omissions or inadequacies in the information contained herein or for interpretations thereof . The material or information is not intended to be relied upon as the sole basis for any decision which may affect any business Before making any decision or taking any action that might affect anybody’s personal finances or business , they should consult a qualified professional adviser . Use or reference of companies / third parties in the report is merely for the purpose of exemplifying the trends in the industry and that no bias is intended towards any company This report does not purport to represent the views of the companies mentioned in the report Reference herein to any specific commercial product process or service by trade name , trademark , manufacturer , or otherwise , does not necessarily constitute or imply its endorsement , recommendation or favouring by NASSCOM or any agency thereof or its contractors or subcontractors . The material in this publication is copyrighted No part of this report can be reproduced either on paper or electronic media without permission in writing from NASSCOM Request for permission to reproduce any part of the report may be sent to NASSCOM 37 C o p y r i g h t © 2 0 2 2 NASSCOM Plot 7 to 10, Sector 126, Noida - 201303 /NasscomVideos /NASSCOMOfficial /nasscomR www . nasscom . in research@nasscom in + 91 - 120 - 4990111